

After the Fed meeting along with the release of the latest US inflation and GDP data, the dollar weakened. The US Dollar Index lost 1.6% and fell below 100.
For financial markets, the divergence between currency and bond performance is important as traders highly rely on multiple economic and market signals when assessing changing conditions. Movements in Treasury yields, inflation expectations, interest rates, as well as the dollar can provide different indications about the direction of the economy. This is particularly relevant for quantitative as well as automated trading strategies, which can process these signals simultaneously rather than relying on a single market indicator.
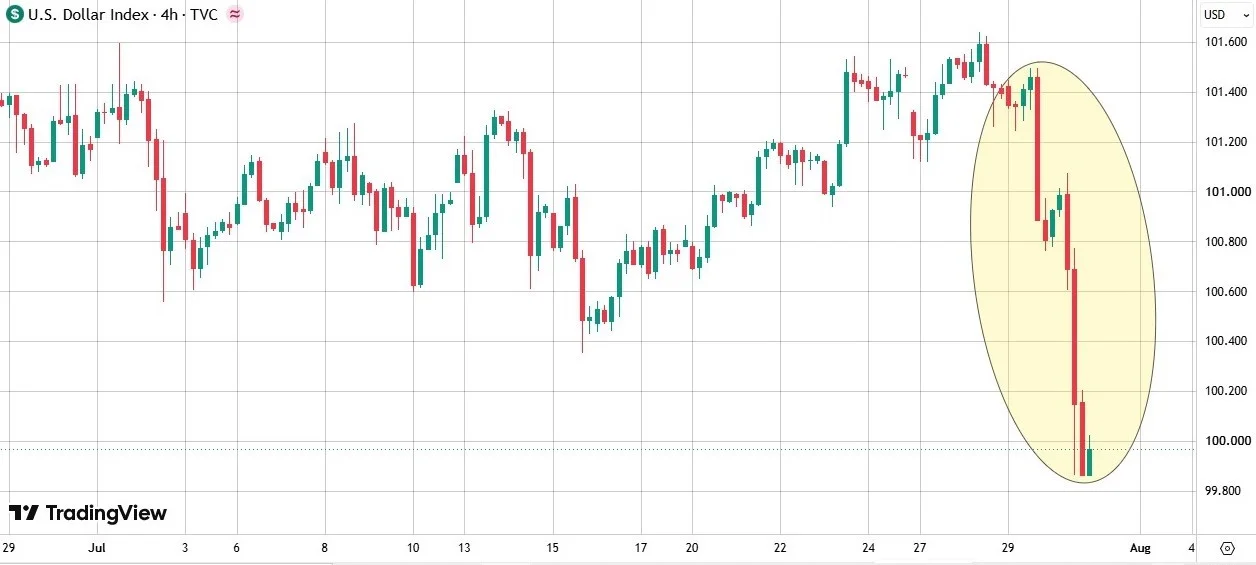
The reaction in the bond market was far less straightforward. The yield on the 30-year Treasury climbed to 5.2444%, reaching its highest level since 2007. This happened even though the Fed kept rates unchanged as well as the June inflation figures were relatively benign. Evidently, the bond market is pricing long-term risks very differently.
The divergence matters as the dollar and long-term Treasury yields respond to different parts of the economic outlook. The dollar tends to be more sensitive to near-term monetary-policy expectations, while long-duration Treasury yields can show longer-term inflation expectations, fiscal conditions, economic uncertainty, as well as the premium investors demand for holding bonds over many years. Tracking these differences can bring useful signals for market participants assessing cross-asset relationships.
Why Inflation Data Matter for Market Signals
To understand why an inflation report that initially appeared encouraging failed to reassure bond investors, it is worth taking a closer look at the details.
The distinction between monthly, quarterly, and annual inflation measures is also relevant when interpreting market signals. A single monthly reading may impact short-term expectations, while broader measures can bring a complete indication of existing price pressures. For quantitative market participants, the difference can be important as trading models may assign different weights to economic indicators depending on their time horizon as well as historical relationship with asset prices.
The monthly inflation data for June showed a clear cooling. According to the Bureau of Economic Analysis, the PCE index declined by 0.1% from May, while its annual rate slowed from 4.1% to 3.7%. Core PCE, which excludes food and energy and is taken as a more stable measure of inflationary pressure, rose by only 0.1% month over month and 3.3% year over year.
A moderation in core inflation can impact expectations for future monetary policy, which in turn can affect Treasury yields, currency valuations, as well as market volatility. These interconnected responses are particularly appropriate to algorithmic trading as automated systems can evaluate several market variables at once as well as respond according to predefined quantitative conditions.
Quarterly Inflation Provides a Broader Market Signal
So where is the problem? It becomes apparent once we look beyond the monthly data and examine the second quarter as a whole. During the second quarter:
- the PCE price index rose at an annualized rate of 5.1%;
- the gross domestic purchases price index increased by 5.7%;
- core PCE increased at an annualized rate of 3.4%.
Monthly changes compare one month with the previous one and are not annualized. Quarterly figures work differently: they compare the average level in the second quarter with the average in the first one and then express that change as an annualized rate.
This distinction is important when assessing market trends because short-term and longer-term indicators can generate different signals. A trading strategy focused on immediate market reactions may respond to the June data, whereas a quantitative strategy with a broader time horizon may incorporate the quarterly figures to determine whether inflation is genuinely moderating.
June tells us that inflation cooled toward the end of the quarter, but it does not erase the increases recorded in April and May. There is another point as well. The quarterly figures show that a large part of the current inflationary pressure is coming from volatile components, especially energy. It is a sign that the disruption in the Gulf and the crude oil market is beginning to leave scars on the economy.
Energy-price movements can add another layer to these market signals because changes in crude oil prices can influence inflation expectations, bond yields, currencies, and risk sentiment. When several of these indicators move simultaneously, quantitative models can use their relationships to assess changing market conditions and potential shifts in volatility.
Slower GDP Growth Creates a Policy Trade-Off
The GDP report was not particularly encouraging either. US real GDP grew at an annualized rate of just 1.5% in the second quarter, down from 2.1% in the first.
This helps explain the divergence between the DXY and long-term Treasury yields. The two respond to different parts of the economic outlook.
The dollar tends to respond mainly to expectations for near-term monetary policy, as well as to the gap between short-term interest rates in the United States and those in other major economies. The benign June inflation data and the Fed's decision to leave rates unchanged therefore softened the near-term policy outlook and pushed the dollar lower.
The 30-year Treasury yield reflects something different: long-term inflation expectations, economic uncertainty, and the premium investors demand for tying up their capital for many years.
As these relationships become more complex, market participants are highly relying on automated systems to monitor economic indicators and cross-asset price movements. This is contributing to the broader expansion of quantitative trading infrastructure. The algorithmic trading market is estimated to be valued at USD 3.59 Bn in 2026 and is expected to reach USD 6.68 Bn by 2033, exhibiting a compound annual growth rate (CAGR) of 9.3% from 2026 to 2033. The projected expansion show the high use of technology to process market information, identify trading patterns, as well as execute strategies across financial markets.