Electronic data interchange (EDI) removes the paper out of healthcare administration. Things such as claims, eligibility checks, as well as the authorization requests are dependent on clean data that is moving instantly between the providers, insurers, as well as the clearing houses. When a human has to intervene manually, the processing stalls as well as the administrative costs spike.
Web-based EDI software plays a major part in negating such issues as processing stalling, as it is able to coordinate the exchanges by directly linking to the billing systems as well as to the electronic health records. But to pick the right platform, it takes more than merely glancing at a clean interface. What is required is a rock-solid payer connectivity, an airtight security, as well as a strict adherence to the healthcare data standards.
These requirements underpin the expanding Healthcare EDI Market, which is estimated at USD 5.3 Billion in 2026 and projected to reach USD 8.8 Billion by 2033, growing at a CAGR of 10.4%. Meanwhile, as healthcare organizations continue to seek to simplify the claims processing as well as to improve the information exchange, web-based EDI platforms as well as managed transaction services are poised to become even more important to administrative operations.
What Are the Leading Segments of the Healthcare EDI Market?
The market breaks down across a few core dimensions covering delivery models, transaction types, and the end users running the software.
- By Component: Services and Solutions.
- By Delivery Mode: Web & Cloud-based EDI, EDI VAN, Point-to-Point EDI, and Mobile EDI.
- By Transaction Type: Claims Management (Claims Submission, Claim Status, Eligibility Verification, Payment Remittance, Referral Certification & Authorization, Claim Payments, and Others), and Healthcare Supply Chain.
- By End User: Healthcare Providers, Healthcare Payers, Medical Device & Pharmaceutical Industries, and Pharmacies.
Services claimed the largest revenue share of 53.6% in 2026 and established itself as the leading segment by component in the Healthcare EDI market. Hospitals and clinics usually do not just require the raw transaction software alone, as they also require partner onboarding, document mapping, as well as an ongoing compliance support to function seamlessly.
Web & Cloud-based EDI is projected to account for 38.8% of the market in 2026. Pushing this architecture to the cloud removes the nightmare of maintaining on-premises servers. It makes connecting with external partners vastly easier, provided the vendor actually supports strict healthcare data-security controls.
Claims Management leads the transaction category with a 54.3% share. Since claims dictate reimbursement, keeping submissions, status tracking, and eligibility checks running flawlessly is non-negotiable. The 2024 CAQH Index reported that 98% of medical claims were submitted electronically, while electronic adoption of medical prior authorization stood at just 35%. That massive gap shows exactly where the next wave of automation needs to happen.
What Is the Best Web-Based EDI Software Solutions for 2026?
The six platforms below frequently appear in software roundups, offering different strengths across partner connectivity and workflow integration. Keep in mind that not all of them are built exclusively for healthcare. The HIPAA compliance and specific payer-network coverage have to be verified before signing a contract.
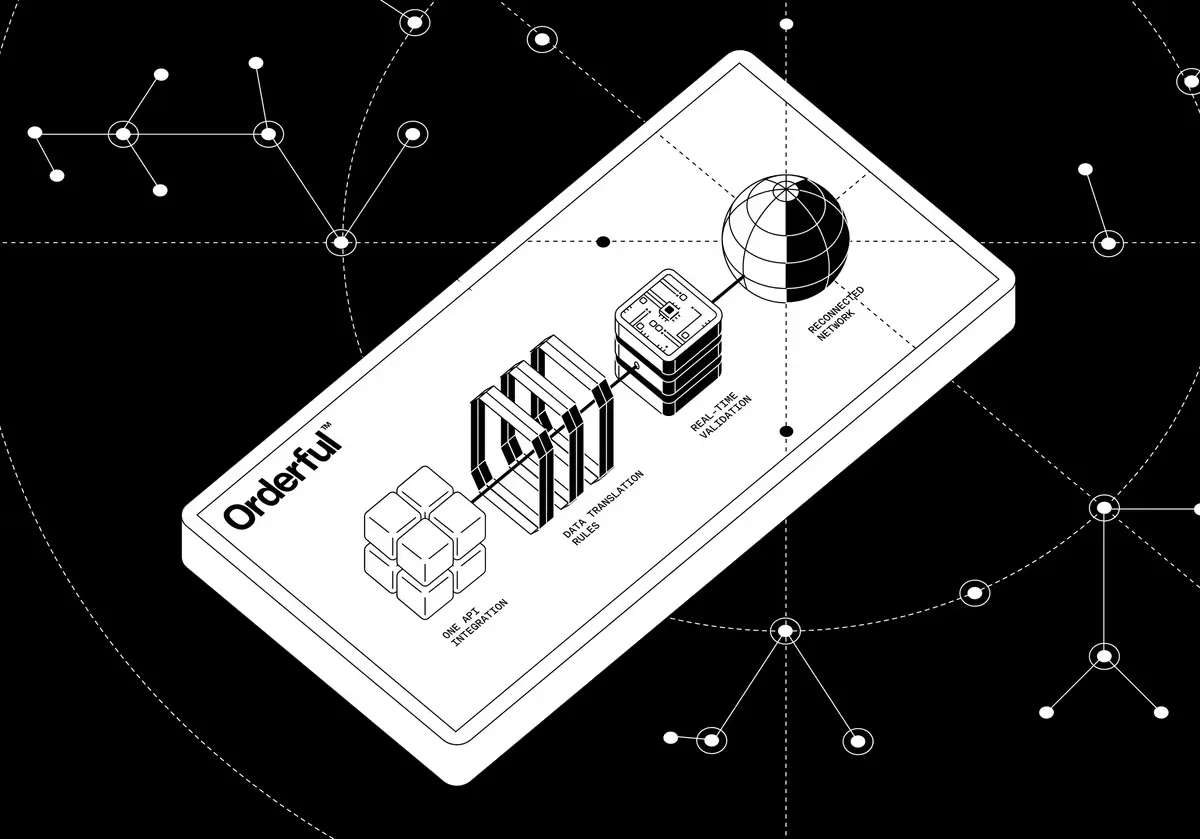
It is best for API-first integration and fast partner onboarding. Orderful uses an API-first approach to EDI, combining prebuilt trading-partner connections with real-time schema validation. Its capabilities include transaction error detection, a dashboard for monitoring exchanges, and a REST API for ERP integration. This setup fits teams looking for raw flexibility, but it is essential to test its specific healthcare capabilities against the actual daily workflows.
SPS Commerce has an extensive retail network coverage and delivers heavy EDI connectivity with a massive footprint in retail. Its platform handles document mapping, compliance, and detailed reporting. If the organization already overlaps with its supported network, this can wipe out a lot of internal admin work. Just run a hard check on its medical payer compatibility first.
TrueCommerce provides seamless commerce and supply chain integration. TrueCommerce links EDI directly to supply chain management, covering inventory and fulfillment. Deep hooks into major ERP systems help businesses coordinate complex order data across channels. For healthcare organizations managing physical inventory alongside administrative transactions, it is a strong option.
Complex B2B integration requirements are its strength. Cleo consolidates EDI, APIs, and direct file transfers into a single environment. It maps data and offers both self-service and fully managed options. This is built for organizations drowning in multiple file formats and disconnected applications.
-
IBM Sterling B2B Integrator
The large-scale transaction environments are seamlessly handled by IBM Sterling B2B Integrator. IBM Sterling handles massive B2B transaction volumes across a variety of protocols like AS2 and SFTP. It brings heavy security and compliance controls to the table. Massive hospital networks with highly complex integration needs lean on its flexibility, though the implementation scope is rarely quick or simple.
Known for cloud integration with EDI capabilities, Boomi packages EDI into a broader integration-platform-as-a-service (iPaaS) model. Its low-code environment uses prebuilt connectors to link cloud apps, internal databases, and outside partners. It works exceptionally well when EDI needs to talk directly to several other distinct cloud applications.
Which Trends Are Shaping the Healthcare EDI Market?
A few core developments are entirely changing how this software operates, and shaping the healthcare EDI market.
-
Standardized electronic claims attachments
In March 2026, the Centers for Medicare & Medicaid Services finalized the HIPAA claims attachments rule. The mandate sets strict standards for securely exchanging clinical documentation, like imaging, medical records, and lab results, alongside the actual claims. It projects roughly USD 781 million in annual industry savings. Covered entities have until May 26, 2028, to fully comply. This finally gives IT teams a hard deadline for building out electronic documentation workflows.
-
Greater interoperability between EDI and APIs
Legacy EDI still handles the bulk of standardized transactions, but modern systems have to bridge those exchanges with clinical APIs. The 2024 CMS Interoperability and Prior Authorization Final Rule requires impacted payers to implement certain provisions by 2026, with most API requirements scheduled primarily for 2027. Future-proof integration strategies have to support old-school EDI standards right alongside modern API architecture.
-
Automation beyond basic transaction submission
Getting a claim out the door electronically is easy; handling what happens next is where the friction lives. Because prior authorizations and attachments still lag heavily in digital adoption, teams need software that actually resolves exceptions. The market is demanding systems that automatically flag incomplete exchanges, surface the exact reason for a rejection, and route the file to the correct billing team member.
Where Are the Opportunities for Healthcare EDI Providers in the U.S. Market?
North America’s 42.2% share of the 2026 market stems from a deeply entrenched digital transaction infrastructure. The U.S. healthcare EDI market offers lucrative opportunities to the stakeholders due to the regulatory environment, as HIPAA forces covered entities to use standardized electronic transactions for eligibility, claims, and remittance advice.
Yet adoption is entirely lopsided. While claims submission is nearly fully digital, medical prior authorization remains stuck at that 35% mark. The recent CMS standards for electronic claims attachments open a massive door for tech providers who can bridge payer and provider systems to automate this specific documentation nightmare.
The money isn't in replacing paper anymore. The opportunity lies in automating the manual cleanup that happens after a claim bounce with authorizations, missing attachments, and endless follow-ups.
Who Are the Major Companies in the Healthcare EDI Market?
Key players in the healthcare EDI market include Optum, Dell Technologies, Emdeon, The SSI Group, ZirMed, Tallan, Quadax, and Allscripts. These companies cover everything from raw claims processing to deep revenue-cycle operations.
Recent moves prove the competition has moved past simple transaction hosting:
- The SSI Group: In June 2026, SSI and Janus Health launched an enhanced claim-status solution pulling line-level details before the electronic remittance advice even arrives, helping billing teams fix denials instantly.
- Quadax: A May 2026 partnership with SlicedHealth combined Quadax’s claims software with deep contract modeling to actively hunt down revenue leakage.
- Substrate AI: In July 2026, Substrate opened its claim-status agent via an API. Developers can now pull normalized claim-status data programmatically, blending EDI, APIs, and scraped payer-portal data to fully automate claim follow-ups.
Vendors are no longer just pipelines; they are active automation engines.
How Should Healthcare Organizations Choose the Right EDI Software?
To choose the right EDI software, it is imperative to start with the transactions and partners that an organization needs to support. Some of the key tasks are to vet the payer connectivity, ensuring that it talks to the specific EHR, and to heavily audit the security controls. Furthermore, the hidden costs, such as the subscription fees, mapping charges, and ongoing maintenance should not be ignored.
The following are some recommendations:
- A pilot must be run with a handful of high-priority partners at first.
- The error handling as well as the workflow integration must be rigorously tested before they are rolled out the billing department.
- The right software will depend on the specific trading network as well as on the internal IT bandwidth. For instance, Orderful, SPS Commerce, and Boomi all solve the problem differently.

