
Global Industrial Adhesives & Sealants Market Size and Forecast – 2026 to 2033
The global Industrial Adhesives & Sealants Market is estimated to be valued at USD 81.96 Bn by 2033, while exhibiting a moderate CAGR of 4.76% during 2026-2033, escalating from USD 59.19 Bn in 2026. Testifying to such a steady growth, in 2024, the worldwide trade of glues and adhesives of all kinds (package <1 kg) registered a 5.34% and an annualized 6.68% rise from the previous year and over the past five years, respectively, according to the Observatory of Economic Complexity (OEC).
Expansion in this sector is primarily attributed to the widening use of engineered bonding and sealing systems in automotive production, electronics assembly, packaging conversion, industrial machinery, and construction applications. It also reinforces the sector’s competitive importance, which can be illustrated by Sika's acquisition of Turkish adhesives and sealants manufacturer, Akkim, in September 2026. This decision was intended to expand Sika's product capabilities, production footprint, and access to the adhesives and sealants market across Eastern Europe, Central Asia, the Middle East, and North Africa.
Key Takeaways of the Global Industrial Adhesives & Sealants Market
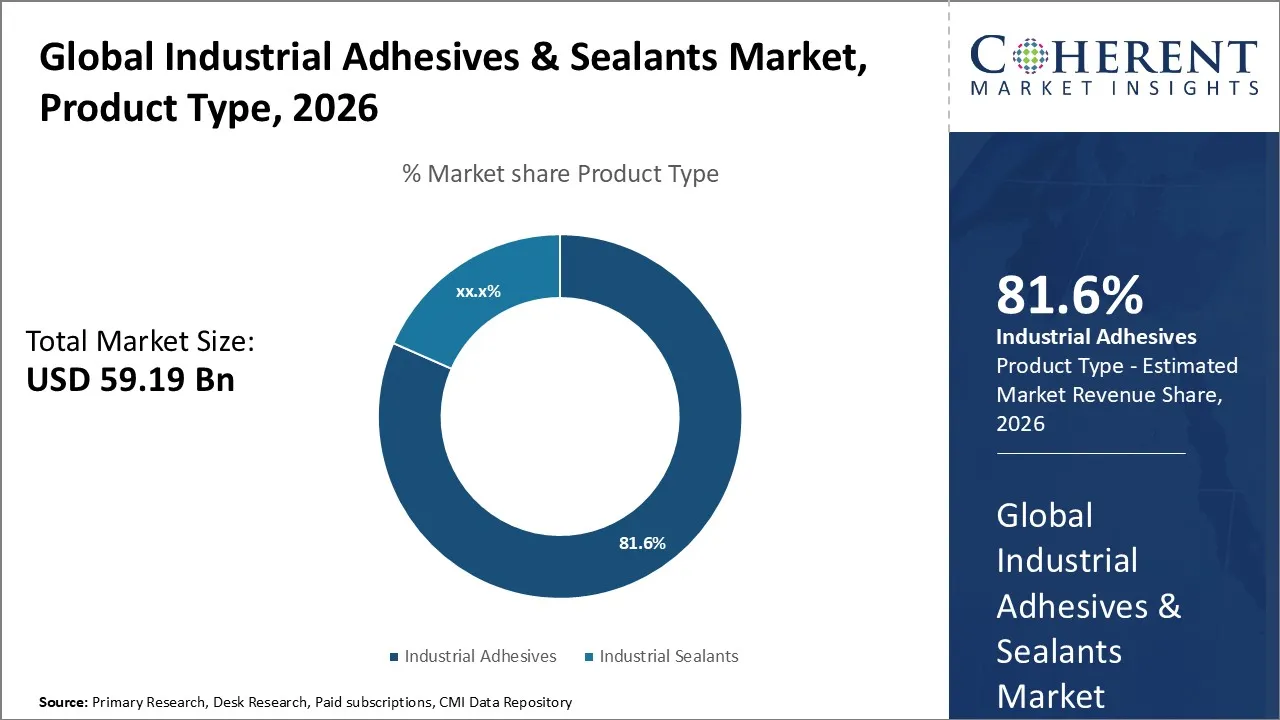
- By product type, industrial adhesives are estimated to account for the largest revenue share of 81.6% in 2026, owing to their extensive use in assembly, component bonding, lamination, and industrial production processes. In this regard, the International Journal of Adhesion and Adhesives predicted the global industry value if adhesives to surpass USD 85 Bn in 2026.
- By resin chemistry, polyurethane-based products are modeled to lead the market by capturing a 20.4% share in 2026. This is a reflection of the growing demand for flexible, durable bonding and sealing solutions, where the OEC recorded a 6.64% increase in the global trade value of adhesives based on rubber or plastic (package >1 kg) between 2023 and 2024.
- By formulation technology, water-based systems are projected to hold approximately 41.4% in 2026. This is due to growing adoption of lower-emission production technologies. Demonstrating their manufacturing suitability, Trinseo introduced a waterborne acrylic laminating adhesive, LIGOS A 9200, July in 2024 that comes with 62% solid content and 99% recovery of paper fibres.
- By end-use industry, paper, board & packaging is estimated to represent the largest application category, with a projected share of 28.6% in 2026, driven by high-volume bonding requirements in industrial packaging operations. The robust expansion of corrugated packaging industry is prominent evidence of the same.
- Asia Pacific is expected to become both the dominating and fastest-growing region in the industrial adhesives & sealants market with an estimated 39.2% revenue share in 2026. The concentration of global automotive, electronics, packaging, and general manufacturing activity in APAC is largely responsible for this leadership. It can further be confirmed by the 2024 International Journal of Adhesion and Adhesives, positioning APAC as the highest shareholder in the global adhesives industry by 2026.
Segmental Insights
Why Does the Industrial Adhesives Segment Dominate the Global Industrial Adhesives & Sealants Market?
Based on product type, the industrial adhesives sub-segment is poised to hold the largest revenue share of 81.6% in 2026. Its leading position is attributable to the widespread use of engineered bonding materials in automated assembly lines, packaging manufacturing, electronic component production, and transportation equipment. Such a substantial commercial importance is portrayed by H.B. Fuller's 2025 financial results, recording a 30% captivity of its engineering adhesives business in consolidated revenue.
Moreover, industrial adhesives are becoming highly attractive for manufacturers seeking design flexibility, especially where conventional mechanical joining methods can create additional weight, material stress, or complex assembly requirements. This favorable shift in consumer preference can be testified by the 2.06% decline in the trade of mechanical seals across the globe between 2023 and 2024, as per the OEC findings.
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Why Are Polyurethane-Based Products a Leading Chemistry in the Industrial Adhesives & Sealants Market?
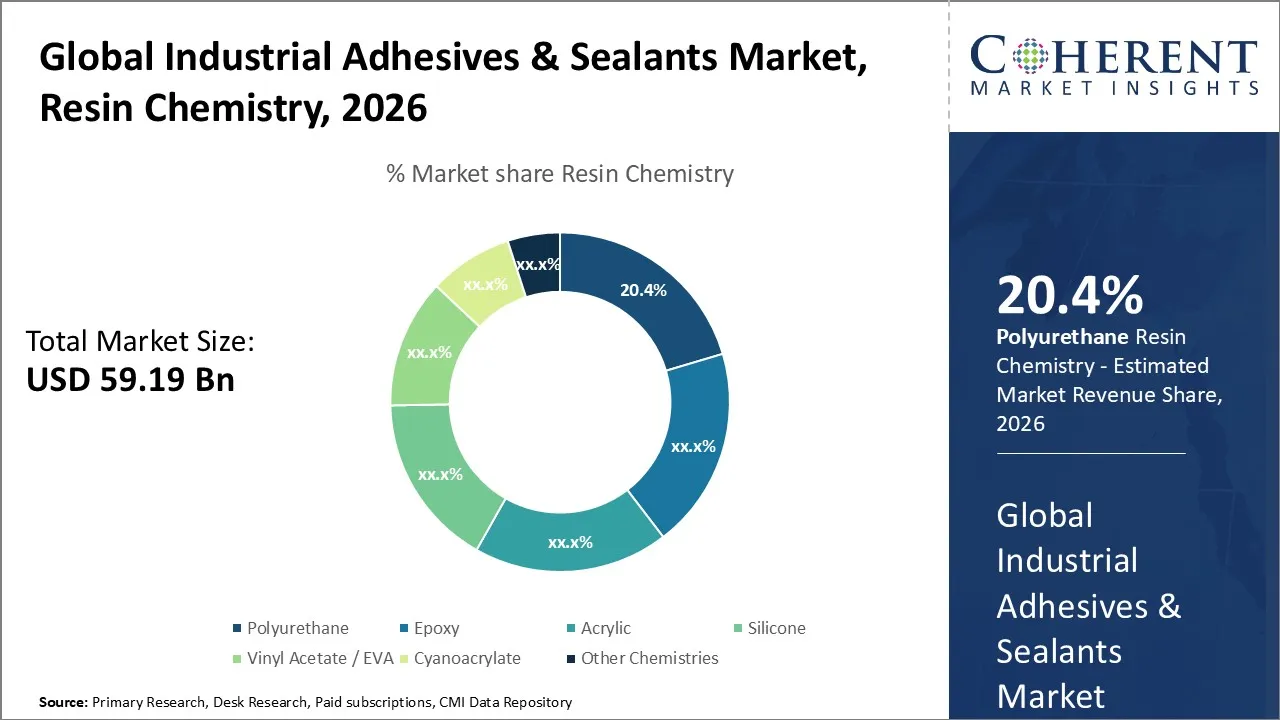
Polyurethane-based products are anticipated to represent 20.4% of the resin chemistry segment in the global industrial adhesives & sealants market by the end of 2026. The category holding largest the individuality in this sector is majorly supported by the sustained demand for materials combining elasticity, impact resistance, substrate compatibility, and reliable adhesion. The superiority of this formula in adhesion can be evidenced by a 2025 publication of the Royal Society of Chemistry demonstrating 79% increase in peel strength from polyurethane-diacrylate doping in pressure-sensitive adhesives, compared to commercially available reference models.
Polyurethane chemistry is particularly relevant for vehicle interior assembly, composite panel production, industrial flooring, insulated components, and applications requiring controlled flexibility. The breadth of industrial demand is further fulfilled through competitive innovation. For instance, in May 2026, Plexus launched three new thermomechanical polyurethane structural adhesives, DT2325, DT2430, and DT2630LD, to help engineers manage the increasing thermal and mechanical stresses found in modern assemblies.
Why Are Water-Based Systems Gaining Preference in Industrial Adhesive Formulations?
In terms of technology, the water-based sub-segment is estimated to account for 41.4% share in the industrial adhesives & sealants market by 2026. Its extensive use in paper converting, packaging production, selected woodworking applications, and industrial lamination processes support the persistent dominance, as it offers controlled application, reduced reliance on organic solvents, and compatibility with high-throughput manufacturing.
Industrial adhesive suppliers are responding to this surge by introducing new application technologies. Exemplifying the same, in May 2026, Henkel showcased water-based specialty tape technologies for electric-vehicle battery systems at the Battery Show Europe, extending its bonding portfolio beyond conventional liquid adhesives. This signal continued development of these formulations, helping the sub-segment reach broader, demanding manufacturing environments.
Why Does Paper, Board, and Packaging Remain the Largest Industrial End-Use Segment?
The paper, board, and packaging industry is modeled to capture the largest end-use share of 28.6% in 2026. As emissions and waste generation from this sector started concerning global and national environmental authorities, sustainable production goals are now more oriented around using eco-friendly ingredients and heightening the plant’s recyclability. In European Union (EU) alone, 81.5 million tonnes of packaging waste were generated in 2024, with only 67% being recycled, according to the European Commission (EC).
On the other hand, adhesive reliability directly influences production throughput, package integrity, and the ability to process different packaging substrates. It proves the importance of careful adhesive selection for associated workflows, which promotes innovation and targeted investments in this category. Participating in this wave of specified portfolio expansion, in May 2026, Henkel inaugurated its upgraded Packaging Competence Center in Düsseldorf, Germany to provide advanced testing and collaboration capabilities for packaging adhesives and coatings under industrial production conditions.
Current Events and Their Impact on the Industrial Adhesives & Sealants Market
Current Event | Description and its Impact |
EU Construction Products Regulation – January 2026 |
|
India Electronics Components Manufacturing Scheme – February 2026 |
|
Industrial Adhesives & Sealants Market Dynamics
Market Drivers
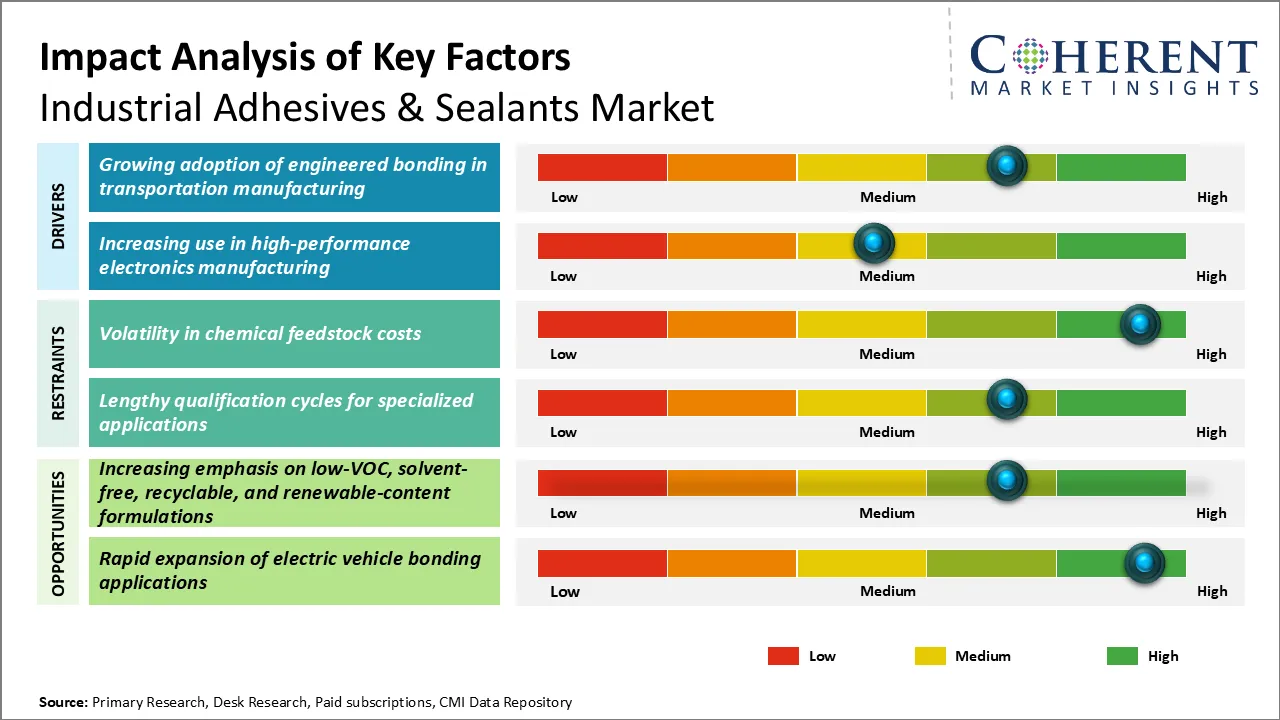
- Growing Adoption in Transportation Manufacturing: Automakers are increasingly incorporating structural adhesives and elastomeric sealants into vehicle body assemblies, composite structures, battery systems, and vibration-sensitive components to establish competitive alignment with the trend of vehicle lightweighting and electrification. For instance, according to a recently published article, Elastomeric seals are essential automotive components that ensure the performance and safety of systems ranging from engines to braking systems. This is creating a new consumer base for manufacturers in this sector, specifically those offering products with controlled curing behavior, fatigue resistance, and compatibility with metals, plastics, and composite substrates.
- Increasing Use in High-Performance Electronics: Pipelines of the industrial adhesives & sealants market are expanding their capabilities to serve electronics, thermal management, industrial protection, and mobility applications. These advancements are specifically directed towards next-generation silicone-based technologies requiring flexibility, temperature resistance, electrical insulation, and long-term environmental protection. Thus, expansion in this aspect of electronics development and production refers to a lucrative increase in consumption and innovation in this sector.
- Displaying the real-world utilization of this scope, in October 2026, Henkel launched a conductive die-attach adhesive film, Loctite ABLESTIK CDF 900, offering thermal conductivity of more than 8 W/m-K. It was developed for AI processors, high-performance computing, and next-generation telecommunications equipment.
Emerging Trends
- Increasing Emphasis on Debonding and Circular Product Design: Manufacturers are researching adhesive systems that retain their intended strength during service but permit controlled disassembly during repair, recycling, or component recovery. For instance, in 2026, Cemedine, Hakuten, and design studio we+ presented a seaweed-derived adhesive, LOOPGLUE, which can be removed using water.
- Expansion of Solvent-Free Laminating Technologies: Flexible packaging manufacturers are exploring adhesive systems that reduce drying requirements and improve compatibility with new multilayer packaging structures. Proving its relevance with this trend, in July 2025, Henkel introduced a solvent-free laminating adhesive system, Loctite Liofol LA 7837/LA 6265, for demanding retort packaging applications.
- Greater Focus on Bio-Based Industrial Adhesives: Adhesive suppliers are developing products containing renewable feedstocks while maintaining processing compatibility with established industrial equipment. Exemplifying the same, in April 2025, Jowat highlighted Jowacoll GROW 125.00, which is a surface adhesive containing 30% bio-based content under ISO 16620-4 methodology, targeting woodworking and surface-bonding applications.
Regional Insights
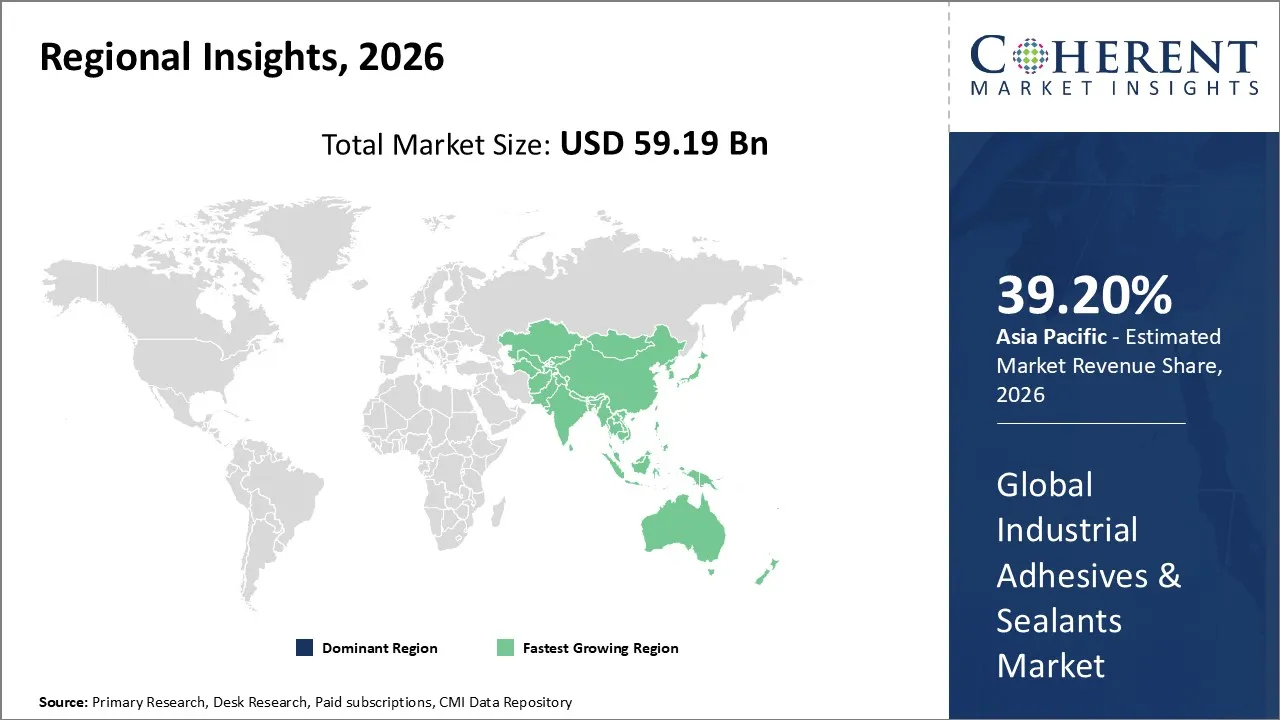
Asia Pacific is Projected to Lead the Global Industrial Adhesives & Sealants Market with an Estimated 39.2% Share in 2026
The region is also showing the fastest growth in this sector on account of its extensive chemical production networks across China, Japan, India, South Korea, and Southeast Asia. Besides, these countries are recognized as the global electronics and automotive manufacturing hubs, which generate demand for assembly adhesives, industrial sealants, laminating compounds, and specialized electronic bonding materials. This can be evidenced by China (USD 32.9 billion), South Korea (USD 12 billion), and Chinese Taipei (USD 9.9 billion) being top 3 semiconductor manufacturing equipment importers in the world till 2024.
This production concentration provides a substantial downstream demand base for adhesives and sealing technologies across assembly lines and component manufacturing plants. Subsequently, both regional and international chemical producers are heavily investing in localized product development and supply capabilities. For instance, in October 2026, Sika decided to acquire the industrial adhesives operations of Resonac Corporation across Japan, China and Taiwan, concluding the transfer of Resonac’s Goi Plant (adhesives & hot-melts), Dapumei Plant (Li-Bond Materials), and RLBT’s Minxiong Plant (polyurethane adhesive and epoxy adhesive products).
North America have Become an Important Growth Region for the Industrial Adhesives & Sealants Market
Growth opportunities within this regional territory are concentrated in aerospace, automotive engineering, electronics, industrial equipment, and technologically advanced manufacturing. As a testimony for this, in August 2026, the U.S. registered an 11.1% rise the year-on-year exports of Motor Vehicles (including their parts & accessories). This benefits domestic established industrial adhesives & sealants suppliers, specifically those fulfilling specialized customer requirements.
As a result, globally leading material manufacturers continue to expand their operations across North America. Exemplifying this, in September 2025, Henkel announced the expansion of its Brandon, South Dakota, manufacturing facility, through an investment of approximately USD 30 million. The decision was backed by an intention to double the facility's area to 70,000 square feet and strengthen its capabilities in thermal-management and adhesive solutions for electric vehicles (EVs) and electronics.
Global Industrial Adhesives & Sealants Market Outlook for Key Countries
China's Advanced Manufacturing Ecosystem is Supporting Industrial Adhesives & Sealants Demand
China is augmenting the market as a major demand center for industrial adhesives and sealants due to its extensive manufacturing base across electronics, industrial automation, transportation equipment, and component production. Displaying this leadership in the supply chain, in 2024, the country ranked among the top 3 exporters of cars, tractors, trucks & parts thereof. (USD 210 billion), industrial robots (USD 296 million), integrated circuits (USD 171 billion), and electrical machinery & electronics (USD 1.06 trillion) worldwide, as per the OEC report.
Such an incremental manufacturing ecosystem requires specialized chemical products that are capable of supporting high-speed assembly, component miniaturization, and complex material combinations, attracting lucrative capital influx towards this sector in China. For instance, in September 2025, Henkel inaugurated its new Inspiration Center for adhesive technologies in Shanghai following an investment exceeding EUR 60 million. The 33,000-square-meter facility brings together more than 500 scientists and technical specialists to develop impactful and sustainable formulations for industrial customers.
The U.S. Represents as a Key Marketplace for High-Performance Industrial Bonding Technologies
The steady growth of the U.S.-based industrial adhesives & sealants market is closed linked to the sustained local demand for specialized materials from its massive transportation, aerospace, industrial equipment, and construction-product manufacturing bases. Testifying to the same, motor vehicle production output crossed 10.24 million units in 2025, marking a 12% increase from 2021, according to the International Organization of Motor Vehicle Manufacturers (OICA).
This demonstrates the growing strength of domestic demand for material performance under demanding operating conditions and compatibility with controlled manufacturing processes. To utilize this surge, in May 2024, H.B. Fuller acquired a supplier of specialty adhesives, fastener locking products, and sealing solutions, ND Industries, to expand its capabilities in automotive, electronics, aerospace, and other engineered applications in the country.
India's Electronics Manufacturing Expansion is Creating Opportunities for the Industrial Adhesives & Sealants Market
India is emerging as an emerging marketplace for industrial adhesives and sealants manufacturers worldwide, owing to recent expansion in domestic electronic components, automotive systems, industrial machinery, and paper manufacturing. For instance, as of August 2026, 106 projects under the Electronics Components Manufacturing Scheme had been approved across 15 states, covering 30 electronics product categories with an approved investment of INR 69,548 crore.
Such efforts of localization provide opportunities for application-specific bonding materials, thermal interface products, encapsulants, and protective sealing compounds. Influenced by this ecosystem, in March 2026, Henkel opened an advanced customer application center in Bengaluru to support electronic-material development, testing, and validation. The facility enables manufacturers to collaborate on adhesive and thermal-management solutions to help India reduce dependence on overseas testing infrastructure during the product qualification process.
Germany Remains a Leader in the European Industrial Adhesives & Sealants Technology Market
Germany's regional position is backed by its strong capabilities and expertise in engineering, specialized equipment manufacturing, vehicle production, and chemical formulation. Thus, domestic industrial adhesive suppliers who operate within this manufacturing ecosystem are capitalizing on high-performance bonding materials featuring alignment with rigorous technical specifications and production-efficiency requirements. This business advantage can be illustrated by DELO's attractive financial performance, attaining an increase of 8% in its annual revenue, totaling EUR 264 million, over the previous financial year, as recorded by the company in May 2026.
Similarly, continuous spending on R&D and manufacturing expansion represent the commercial success of Germany in advanced industrial adhesive technologies. Following this pathway, in November 2025, Bolton began construction of a modern, efficient, and sustainable UHU adhesive production center in Rheinmünster, Germany. The facility is planned to become operational in 2027 and is designed for annual capacity of 170 million products.
Japan's Specialty Materials Expertise is Helping Make Progress in Industrial Adhesives & Sealants Innovation
Japan continues to play the role of a pivotal hub of consumption and product development in the industrial adhesives and sealants market. This is attributed to its superior expertise in automotive engineering, next-generation electronics manufacturing, chemical research, and precision-processing. As evidence, in 2024, the country ranked as the 2nd largest exporter of cars (USD 116 billion) and industrial robots (USD 269 million) in the world, according to the OEC survey report.
This industrial base supports requirements for structural adhesives, interior assembly bonding, gasket formation, electronic component sealing, and other technically specified adhesive materials. Portraying such a progressive business atmosphere, in June 2025, Toyochem developed the new TOYOMELT ™ P-201 Series of ultraviolet (UV) curable hot melt adhesives, offering heat resistance exceeding 100°C, for bonding steel components in automotive and electronic devices.
How Are Advanced Dispensing and Automated Bonding Technologies Creating Opportunities in the Industrial Adhesives & Sealants Market?
Adhesive application is becoming more closely integrated with digital manufacturing processes, enabling improved control over dispensing volumes, bond-line dimensions, curing conditions, and process repeatability. This trend creates opportunities for suppliers offering compatible dispensing technologies, application support, and production-line validation. These technologies are especially important for complex assemblies involving miniature electronic components, high-strength composite structures, and intricate sealing geometries.
This shift toward integrated material-and-process solutions demands availability of application-specific equipment from specialized adhesive manufacturers. To capitalize this trend, companies offering industrial bonding products are consequently expanding their services beyond formulation supply to include application engineering and process optimization. Supporting this development, in December 2025, 3M Company introduced Adhesive Mix Monitor, a technology designed to monitor the mixing quality of two-component structural adhesives during dispensing.
Company | Date | Corporate news / product innovation | Relevance to Industrial Adhesives & Sealants Market |
Nordson Corporation | July 2025 | Product Launch: Nordson introduced its VersaBlue II adhesive melter, featuring precision gear dosing, variable-speed drives, EtherCAT and OPC UA connectivity, and real-time diagnostics. The system also offers up to 10% lower energy consumption through improved thermal insulation. | Demonstrates the growing integration of digitally controlled adhesive dispensing systems with automated manufacturing lines, supporting consistent adhesive application, improved process monitoring and reduced material waste. |
DELO Industrial Adhesives | October 2025 | Product Launch: DELO introduced its ACTIVIS 330 system, combining adhesive dispensing and light activation in a single process. The compact equipment supports dispensing quantities starting at 4 µL and expands the portfolio of compatible adhesives from three to eight formulations. | Highlights the transition toward integrated material-and-equipment solutions that improve dispensing precision, curing reliability and production-line efficiency. |
Henkel AG & Co. KGaA | September 2025 | Facility Expansion: Henkel opened its North American Battery Application Center in Michigan, featuring a six-axis industrial robot for testing structural adhesives, sealants and thermal-interface materials. The center supports optimization of dispensing volume, application temperature, speed and robotic path accuracy. | Demonstrates increasing investment in robotic adhesive application, manufacturing-scale validation and application engineering services for advanced automotive assembly. |
DELO Industrial Adhesives and DATRON AG | October 2025 | Technology Collaboration: DELO and DATRON developed an automated fuel-cell sealing solution combining light-curing liquid gasket materials with high-speed dispensing equipment. The system enables adhesive application at speeds of up to 50 meters per minute, followed by curing within seconds. | Demonstrates growing collaboration between adhesive manufacturers and equipment suppliers to deliver precision sealing solutions for complex industrial geometries. |
Nordson EFD | November 2026 | Product Launch: Nordson EFD introduced its PICO Pµlse XP HV jetting system for precision dispensing of high-viscosity adhesives and silicones. The system supports deposits as small as 1 nanoliter, dispensing frequencies up to 600 Hz under specified conditions and automation-ready connectivity. | Demonstrates advancements in digitally controlled microdispensing systems for electronics, medical devices and automotive assemblies requiring high repeatability and accurate material placement. |
Coherix Inc. | May 2025 | Service Launch: Coherix introduced its CARES program, providing technical assistance, operator training and process evaluations for manufacturers using 3D vision-based adhesive dispensing inspection systems. The program focuses on improving application accuracy and production-process reliability. | Highlights the increasing importance of inspection technologies, technical support and ongoing application-process optimization in automated industrial bonding operations. |
DELO Industrial Adhesives | June 2024 | Product Launch: DELO introduced its DOT PN5 LV pneumatic jet valve for ultra-precise dispensing of low-viscosity adhesives. The system enables dispensing volumes as small as 1 nanoliter and is designed for integration into compact automated production equipment. | Supports demand for precision adhesive application technologies in miniaturized electronic components and industrial assemblies requiring controlled dispensing volumes. |
Henkel AG & Co. KGaA | September 2026 | Product and Service Innovation: Henkel announced new railway adhesive and sealant solutions alongside its application engineering services and Manufacturing Excellence Program. The company highlighted its dispensing equipment and customer support for application validation, process efficiency, scrap reduction and resource optimization. | Demonstrates the expansion of adhesive manufacturers into integrated material selection, application engineering, production-line optimization and technical validation services. |
Market Players, Key Developments, and Competitive Intelligence
Key Developments
- In September 2026, Henkel launched an isocyanate-free, polymer package-based adhesive and sealant, Teroson MS 940, which is developed for demanding elastic bonding in rail and industrial applications. Its mechanical performance exceeds the capabilities of standard silane-modified polymer (SMP) solutions in elongation and tensile strength, enabling manufacturers to replace polyurethane systems while maintaining the performance required for high safety factors and tightly constrained bondline dimensions.
- In August 2026, H.B. Fuller received an unsolicited cash acquisition proposal from Ancora Holdings Group, valued between USD 1.1 billion and USD 1.2 billion, for its Building Adhesive Solutions (BAS) business. The company's Board of Directors confirmed that it would evaluate the proposal in consultation with financial and legal advisors. The proposed transaction highlights investor interest in the industrial adhesives and sealants industry and the potential for portfolio restructuring among major adhesive manufacturers.
- In May 2026, H.B. Fuller established a new Aerospace Manufacturing Center of Excellence in Charlotte, North Carolina, which is scheduled to open in early 2027, consolidating specialized manufacturing, packaging, testing, and quality-control operations to strengthen its adhesives and sealants capabilities across aviation, space, and defense applications. The company also plans to pursue AS9100 certification and Nadcap accreditation to meet stringent aerospace quality standards.
Competitive Landscape
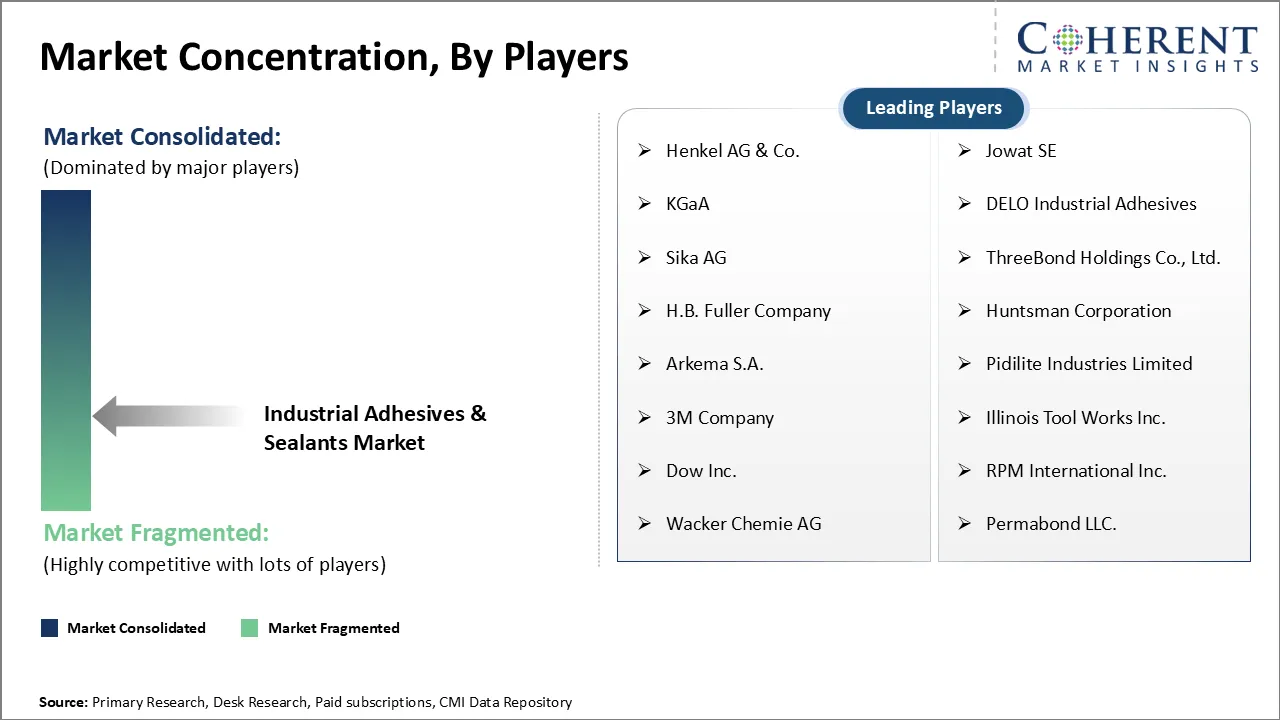
The global Industrial Adhesives & Sealants Market is characterized by a combination of multinational specialty chemical manufacturers, dedicated adhesive producers, and application-focused technology companies. Competition is increasingly influenced by formulation performance, production reliability, technical service capabilities, distribution coverage, and the ability to support specialized industrial manufacturing requirements.
Large companies such as Henkel, Sika, H.B. Fuller, Arkema, 3M, and Dow maintain broad material portfolios and international customer networks. Their strategies include selective acquisitions, regional manufacturing investment, product qualification services, and development of specialized technologies for industrial applications.
Mid-sized and technology-focused manufacturers such as Jowat, DELO, Permabond, and ThreeBond compete through specialized formulations and application expertise. These companies serve customers requiring technical performance, reliable processing characteristics, and customized bonding solutions.
Smaller and specialized manufacturers often concentrate on niche applications such as electronics encapsulation, high-temperature bonding, precision assembly, anaerobic adhesives, and industrial maintenance. Their competitive positioning depends on technical differentiation, customer relationships, and responsiveness to specific manufacturing requirements.
Leading Manufacturers and Notable Products in the Industrial Adhesives & Sealants Market
Manufacturer | Notable products / solutions | Strategic relevance |
Henkel AG & Co. KGaA | Loctite industrial adhesives, Teroson sealants, Technomelt hot-melt systems | Strong global positioning in industrial assembly, packaging conversion, electronics, and transportation bonding. |
Sika AG | Sikaflex adhesive sealants, SikaForce structural adhesives, Sikasil silicone systems | Expanding through acquisitions and regional manufacturing capabilities across construction and industrial applications. |
H.B. Fuller Company | Engineering adhesives, industrial assembly adhesives, packaging adhesives | Specialized industrial portfolio with capabilities in aerospace, electronics, transportation, and converting. |
Arkema S.A. (Bostik) | Engineering adhesives, hot melts, water-based adhesives, smart adhesive solutions | Broad industrial materials portfolio with applications in packaging, transportation, electronics, and durable goods. |
3M Company | Scotch-Weld structural adhesives, epoxy bonding systems, polyurethane adhesives | Established industrial bonding technologies for precision assembly, composites, and engineered components. |
Dow Inc. | DOWSIL silicone sealants, specialty silicone materials, encapsulation systems | Specialization in silicone chemistry and high-performance materials for electronics, mobility, and sealing applications. |
Wacker Chemie AG | ELASTOSIL silicone systems, GENIOSIL silane-based technologies | Advanced silicone and silane chemistry supporting industrial sealing and specialty bonding applications. |
Jowat SE | Jowatherm hot-melt adhesives, Jowacoll dispersion adhesives, Jowapur reactive adhesives | Strong focus on woodworking, furniture manufacturing, packaging, and industrial lamination. |
DELO Industrial Adhesives | DELO-PHOTOBOND, DELO-DUOPOX, DELO-DUALBOND | Precision adhesives and curing technologies for semiconductors, automotive components, and electronics. |
ThreeBond Holdings Co., Ltd. | Industrial sealants, anaerobic adhesives, gasketing compounds | Specialized bonding and sealing solutions for automotive, machinery, and precision manufacturing. |
Huntsman Corporation | ARALDITE epoxy adhesives, structural bonding systems | High-performance resin technologies for transportation, composite structures, and industrial assembly. |
Pidilite Industries Limited | Industrial adhesives, construction chemicals, specialty bonding solutions | Established Indian manufacturer serving industrial, construction, woodworking, and other bonding applications. |
Illinois Tool Works Inc. | Plexus structural adhesives and specialized industrial adhesive systems | Engineered adhesive products for composites, industrial equipment, and transportation applications. |
RPM International Inc. | Tremco sealants, specialty construction and industrial bonding systems | Significant presence in commercial construction, industrial maintenance, and protective sealing applications. |
Permabond LLC | Anaerobic adhesives, cyanoacrylates, epoxies, UV-curable adhesives | Specialized industrial bonding products for precision engineering and automated manufacturing. |
Market Report Scope
Global Industrial Adhesives & Sealants Market Report Coverage | |||
Report Coverage | Details | ||
Base Year | 2025 | Market Size in 2026: | USD 59.19 Bn |
Historical Data For: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
Forecast Period 2026 To 2033 CAGR: | 4.76% | 2033 Value Projection: | USD 81.96 Bn |
Geographies covered: |
| ||
Segments covered: |
| ||
Companies covered: | Henkel, Sika, H.B. Fuller, Arkema, 3M, Dow, Wacker Chemie, Jowat, DELO, ThreeBond, Huntsman, Pidilite Industries, Illinois Tool Works, RPM International, Permabond | ||
Growth Drivers: |
| ||
Restraints & Challenges: |
| ||
Key Takeaways from Analyst
- The Industrial Adhesives & Sealants Market is expected to experience increasing demand for specialized bonding and sealing technologies as manufacturers adopt advanced substrates and automated assembly methods. Suppliers offering consistent technical performance and strong application support may benefit from longer-term industrial customer relationships.
- Competitive differentiation is likely to depend on formulation chemistry, curing efficiency, product qualification capabilities, and regional manufacturing access. Manufacturers that combine material expertise with industrial process engineering may strengthen their positions in higher-value applications.
- Sustainability requirements and changing material specifications are expected to create further opportunities for low-emission, solvent-free, bio-based, and recyclable-system-compatible adhesives. However, commercial adoption will continue to depend on the ability to meet the functional requirements of individual applications.
- Regional manufacturing investment and acquisition activity may influence competitive positioning through 2033. Global suppliers are likely to prioritize facilities and technical centers located near major automotive, electronics, packaging, and industrial manufacturing customers.
Market Segmentation
- Product Type Insights (Revenue, USD Bn, 2021 - 2033)
- Industrial Adhesives
- Industrial Sealants
- Resin Chemistry Insights (Revenue, USD Bn, 2021 - 2033)
- Polyurethane
- Epoxy
- Acrylic
- Silicone
- Vinyl Acetate / EVA
- Cyanoacrylate
- Other Chemistries
- Technology Insights (Revenue, USD Bn, 2021 - 2033)
- Water-Based
- Solvent-Based
- Hot-Melt
- Reactive & Structural
- Others
- End-Use Industry Insights (Revenue, USD Bn, 2021 - 2033)
- Paper, Board & Packaging
- Building & Construction
- Automotive & Transportation
- Electrical & Electronics
- Woodworking & Furniture
- Aerospace & Industrial Equipment
- Others
- Regional Insights (Revenue, USD Bn, 2021 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC Countries
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
- North America
- Key Players Insights
- Henkel AG & Co.
- KGaA; Sika AG
- H.B. Fuller Company
- Arkema S.A.
- 3M Company
- Dow Inc.
- Wacker Chemie AG
- Jowat SE
- DELO Industrial Adhesives
- ThreeBond Holdings Co., Ltd.
- Huntsman Corporation
- Pidilite Industries Limited
- Illinois Tool Works Inc.
- RPM International Inc.
- Permabond LLC.
Sources
Primary Research Interviews
- Industrial adhesives and sealants manufacturers
- Specialty chemical and polymer formulation manufacturers
- Industrial adhesive R&D and product development heads
- Automotive and transportation bonding specialists
- Electronics assembly and semiconductor packaging engineers
- Industrial packaging and lamination manufacturers
- Adhesive dispensing and automation equipment manufacturers
- Construction adhesive and sealant application specialists
- Industrial adhesives distributors and procurement professionals
- Structural bonding, surface treatment, and material testing experts
Stakeholders
- Global industrial adhesives and sealants manufacturers
- Specialty resin, polymer, and chemical suppliers
- Automotive OEMs and component manufacturers
- Electronics and semiconductor manufacturers
- Paper, board, and flexible packaging converters
- Aerospace and industrial equipment manufacturers
- Woodworking and furniture manufacturers
- Construction material producers and contractors
- Industrial adhesive distributors and technical service providers
- Adhesive application equipment and automation companies
Application Areas
- Structural bonding and industrial assembly
- Automotive body, battery, and interior bonding
- Electronics assembly, encapsulation, and thermal management
- Paperboard packaging, carton sealing, and lamination
- Industrial gasketing and joint sealing
- Aerospace and composite material bonding
- Woodworking, furniture, and panel lamination
- Construction joints, façades, and industrial flooring
- Precision dispensing and automated bonding
- Low-VOC, bio-based, and recyclable adhesive applications
Regulatory and Government Bodies
- U.S. Environmental Protection Agency (EPA)
- European Chemicals Agency (ECHA)
- European Commission (EC)
- U.S. Department of Energy (DOE)
- U.S. Occupational Safety and Health Administration (OSHA)
- Ministry of Electronics and Information Technology (MeitY), India
- Bureau of Indian Standards (BIS)
- Central Pollution Control Board (CPCB), India
- Ministry of Industry and Information Technology (MIIT), China
- Ministry of Economy, Trade and Industry (METI), Japan
- European Committee for Standardization (CEN)
- International Organization for Standardization (ISO)
Databases
- Observatory of Economic Complexity (OEC)
- UN Comtrade Database
- Eurostat
- U.S. Census Bureau
- Federal Reserve Economic Data (FRED)
- International Organization of Motor Vehicle Manufacturers (OICA)
- World Bank Open Data
- OECD Data Explorer
- European Chemicals Agency (ECHA) Database
- WIPO PATENTSCOPE
- U.S. International Trade Commission DataWeb
- National industrial production and manufacturing statistics databases
Magazines and Industry Publications
- Adhesives & Sealants Industry (ASI)
- Adhesives & Bonding
- Chemical & Engineering News
- European Coatings Journal
- Chemical Week
- Packaging Europe
- Automotive Manufacturing Solutions
- Manufacturing Engineering
- Chemical Processing
- Plastics Technology
- CompositesWorld
Journals
- International Journal of Adhesion and Adhesives
- The Journal of Adhesion
- Journal of Applied Polymer Science
- Polymer Engineering & Science
- Progress in Organic Coatings
- Materials & Design
- ACS Applied Polymer Materials
- Journal of Materials Processing Technology
- Polymers
- Journal of Industrial and Engineering Chemistry
- RSC Advances
Associations
- The Adhesive and Sealant Council (ASC)
- FEICA – Association of the European Adhesive & Sealant Industry
- American Chemistry Council (ACC)
- European Chemical Industry Council (Cefic)
- Chemical Industries Association (CIA)
- Japan Adhesive Industry Association
- Society of Plastics Engineers (SPE)
- SAE International
- European Polymer Federation (EPF)
- Association of European Automotive and Industrial Manufacturers
Public Domain Sources
- Industrial adhesive and sealant manufacturers' annual reports
- Corporate product catalogs and technical datasheets
- Manufacturer press releases on product launches and innovations
- Corporate acquisitions, investments, and manufacturing expansion announcements
- Industrial adhesive and sealant performance testing publications
- Government manufacturing output and international trade statistics
- Automotive production, vehicle lightweighting, and EV manufacturing reports
- Electronics and semiconductor production statistics
- Industrial packaging production and recycling statistics
- Government chemical safety and environmental regulations
- Construction material performance standards and regulatory publications
- Peer-reviewed polyurethane, epoxy, acrylic, and silicone adhesion research
- Bio-based, low-VOC, and solvent-free adhesive technology publications
- Automated adhesive dispensing and industrial bonding technology studies
- Publicly available industrial adhesive patents and formulation research
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of Information for the Last 10 Years
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Frequently Asked Questions
The global Industrial Adhesives & Sealants Market is projected to register a modeled CAGR of 4.76% from 2026 to 2033.
The global Industrial Adhesives & Sealants Market is estimated at USD 59.19 Bn in 2026 and is projected to reach approximately USD 81.96 Bn by 2033 under the preliminary forecast model.
Increasing adoption of engineered bonding technologies, expansion in industrial manufacturing applications, and investments in specialized adhesive and sealant formulations are major market growth drivers.
Raw material cost volatility and extended technical qualification requirements for specialized industrial applications are important challenges affecting market expansion.
Industrial adhesives are estimated to dominate the market with a modeled revenue share of 81.6% in 2026.
Major participants include Henkel, Sika, H.B. Fuller, Arkema, 3M, Dow, Wacker Chemie, Jowat, DELO, ThreeBond, Huntsman, Pidilite Industries, Illinois Tool Works, RPM International, and Permabond.
Asia Pacific is expected to lead the global Industrial Adhesives & Sealants Market, with a preliminary modeled share of 39.2% in 2026.