

Urea Cycle Disorder Treatment Market Size and Forecast – 2026 to 2033
The Urea Cycle Disorder Treatment Market is anticipated to grow at a CAGR of 4.2% with USD 528.7 Mn share in 2026 and is expected to reach USD 640.7 Mn in 2033. Advances in genetic testing, wider adoption of orphan drugs, greater investment in rare disease research, improved access to specialized healthcare, and continuous development of innovative gene and enzyme replacement therapies further accelerate market growth. According to DCAT Value Chain Insights, orphan drugs have represented over 50% of new drug approvals in the past five years.
Key Takeaways
- Sodium Phenylbutyrate hold the largest market share of 37.9% in 2026 owing to its increasing diagnosis of urea cycle disorders. In India, the estimated incidence of urea cycle disorders with hyperammonemia is approximately 1 in 53,717 live births (about 1.9 per 100,000 live births).
- OTC – Ornithine Transcarbamylase expected to hold largest market share of 42.2% in 2026 owing to the improved early diagnosis through newborn screening. According to the National Institutes of Health, Ornithine transcarbamylase deficiency is an inherited metabolic disorder and the most common Urea cycle disorder.
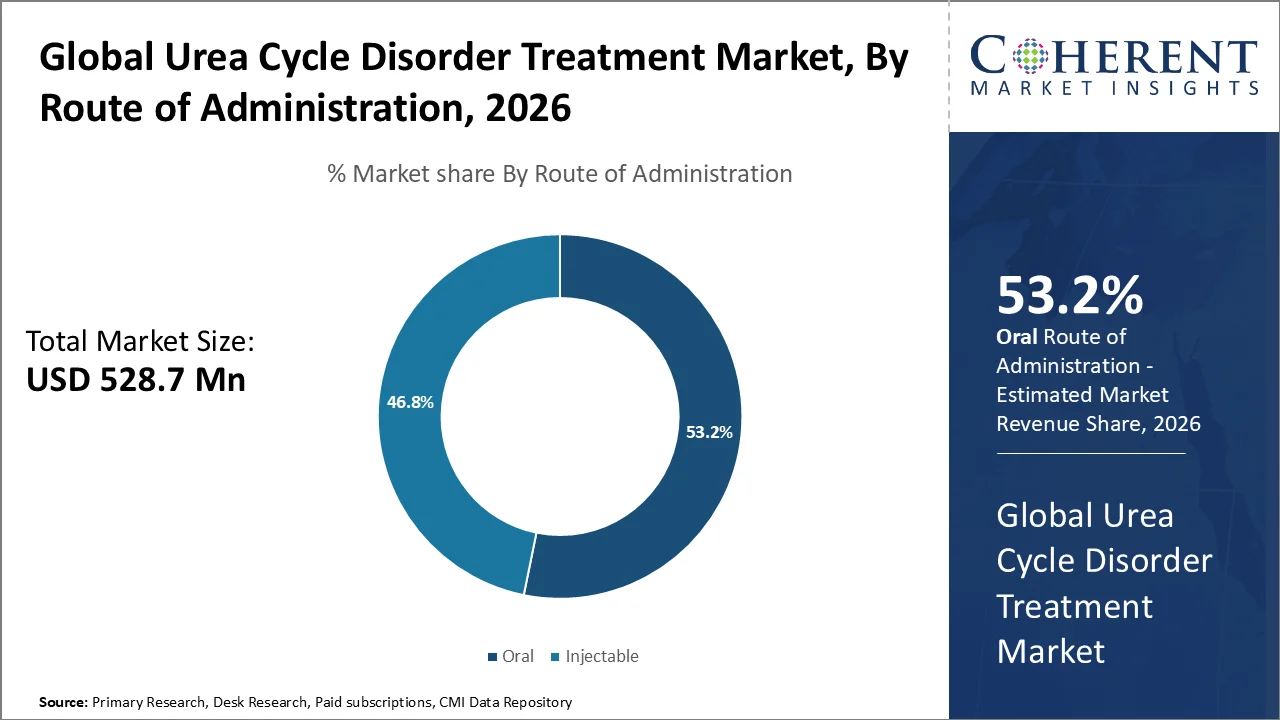
- Oral acquired the largest market share of 53.2% in 2026 owing to the preference for long-term home-based therapy.
- Hospital Pharmacies captures the largest market share of 41.9% in 2026 owing to the high rate of hospital-based diagnosis and treatment initiation.
- North America is expected to acquire the dominant share of 39.2% in 2026 owing to the high awareness and early diagnosis. The estimated incidence of Urea cycle disorder in the United States is approximately 1 in 35,000 live births, resulting in about 113 new cases annually across all age groups.
Current Events and Their Impact on the Urea Cycle Disorder Treatment Market
Current Event | Description and its Impact |
Continued Expansion of Orphan Drug Incentives is Accelerating UCD Drug Development (United States) |
|
FDA's Orphan Drug Designation Activity is Expanding the UCD Pipeline |
|
Segmental Insights
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Why is Sodium Phenylbutyrate Acquiring the Largest Market Share?
Sodium Phenylbutyrate hold the largest market share of 37.9% in 2026. Sodium phenylbutyrate plays a central role in the urea cycle disorder treatment market by effectively reducing ammonia levels and enabling long-term disease management. Healthcare providers increasingly prescribe it as newborn screening programs expand, genetic testing becomes more accessible, and earlier diagnosis of inherited metabolic disorders improves. Greater awareness among clinicians, wider access to specialized metabolic centers, and favorable orphan drug policies continue to drive its adoption. Its convenient oral formulations, well-established clinical profile, and effectiveness as a maintenance therapy support consistent use in both pediatric and adult patients. For instance, Acer Therapeutics Inc. and its collaboration partner RELIEF THERAPEUTICS Holding SA announced that the U.S. Food and Drug Administration (FDA) has approved OLPRUVA™ (sodium phenylbutyrate) oral suspension in the United States for treating certain patients with urea cycle disorders (UCDs), including deficiencies in carbamylphosphate synthetase (CPS), ornithine transcarbamylase (OTC), and argininosuccinic acid synthetase (AS).
OTC – Ornithine Transcarbamylase expected to hold largest market share
OTC – Ornithine Transcarbamylase expected to hold largest market share of 42.2% in 2026 owing to the favorable orphan drug incentives. Ornithine transcarbamylase (OTC) deficiency contributes a major share of the urea cycle disorder treatment market because it represents the most prevalent form of the condition and demands lifelong care. Expanding newborn screening programs, wider genetic testing, and improved clinical awareness help clinicians diagnose the disorder earlier and initiate timely treatment. Healthcare providers increasingly use ammonia-scavenging therapies, while advances in specialized metabolic care and ongoing gene-based research further drive growth. Orphan drug support and better access to rare disease services also increase demand for OTC deficiency treatments. In January 2026, IECURE, Inc. announced that the U.S. FDA granted Regenerative Medicine Advanced Therapy (RMAT) designation to ECUR-506, its investigational in vivo gene insertion therapy for treating neonatal-onset ornithine transcarbamylase (OTC) deficiency.
Oral acquired the largest market share
Oral acquired the largest market share of 53.2% in 2026 owing to the growing early diagnosis through newborn screening. The oral segment in the urea cycle disorder treatment market grows because it supports long-term, home-based disease management. Healthcare providers increasingly prescribe oral ammonia-scavenging therapies as they enhance patient convenience, improve adherence, and boost quality of life. Expanded newborn screening and earlier diagnosis enable clinicians to start oral medications sooner. Wider availability of established drugs, improved taste-masked formulations, and a shift toward outpatient care further drive adoption. Increasing patient survival and improved access to specialty pharmacies also sustain demand for oral therapies. In October 2025, Lupin Limited launched an authorized generic version of Ravicti (glycerol phenylbutyrate) oral liquid 1.1 g/mL in the United States. It is used for the chronic management of urea cycle disorder patients who cannot be controlled through dietary protein restriction or amino acid supplementation alone.
Which Distribution Channel segment dominates the market?
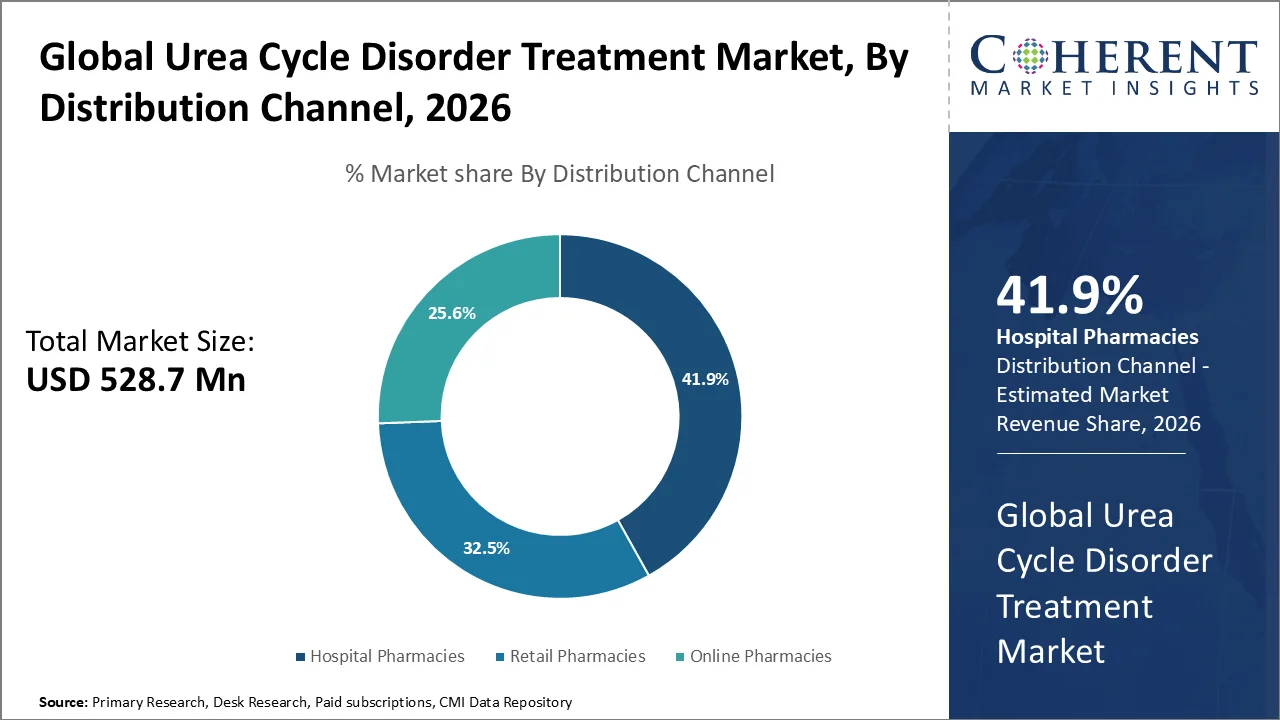
Hospital Pharmacies captures the largest market share of 41.9% in 2026. Hospital pharmacies play a key role in the urea cycle disorder treatment market by supporting both acute and long-term management of severe metabolic conditions. Healthcare providers diagnose patients in hospital settings during hyperammonemia crises and initiate immediate treatment. Expanding newborn screening and earlier referrals increase demand for hospital-based care. In January 2026, the Health Department launched the Universal Newborn Screening Programme to enable early detection of congenital disorders and reduce deaths associated with rare diseases. Specialized metabolic centers, availability of orphan drugs, and multidisciplinary treatment approaches further reinforce their importance. Growing healthcare investment, expanding transplant programs, and active clinical research within hospitals also strengthen reliance on hospital pharmacies.
Urea Cycle Disorder Treatment Market Trends
- Increasing focus on gene therapy and enzyme replacement innovations is transforming the treatment landscape. More than 2,000 gene therapy clinical trials have been completed, are ongoing, or have been approved globally, with several investigational therapies targeting rare inherited metabolic disorders, including UCDs.
- Rising utilization of liver transplantation as a definitive treatment option is supporting improved survival in severe and neonatal-onset UCD cases. According to the Organ Procurement and Transplantation Network (OPTN), pediatric metabolic disorders, including UCDs, remain established indications for liver transplantation, which restores hepatic urea cycle enzyme activity and prevents recurrent hyperammonemia.
- Early diagnosis through expanded newborn screening programs is driving treatment initiation rates. The U.S. Recommended Uniform Screening Panel (RUSP) includes argininosuccinic aciduria (ASA) and citrullinemia type I, enabling routine newborn screening for two major urea cycle disorders across participating states. Early detection significantly reduces neurological complications associated with hyperammonemia.
Regional Insights
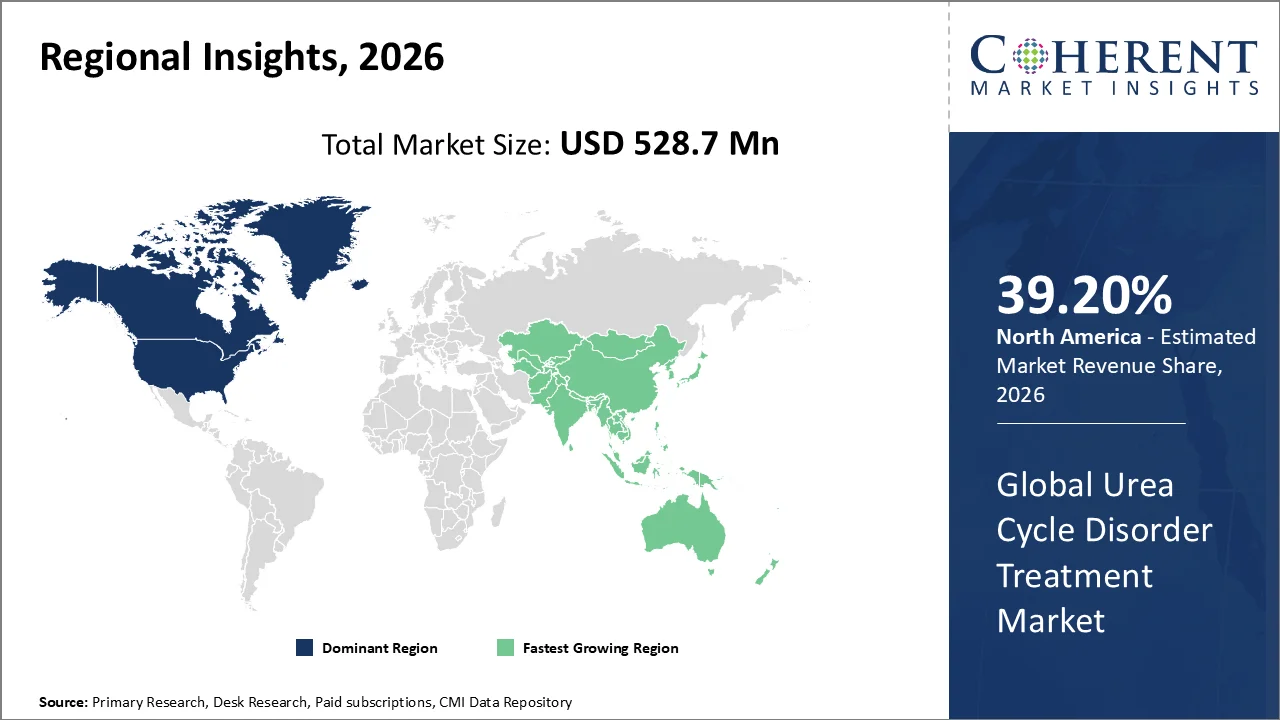
North America dominates owing to high awareness and early diagnosis through newborn screening programs
North America is expected to acquire the dominant share of 39.2% in 2026. North America’s urea cycle disorder (UCD) treatment market grows due to strong newborn screening programs, which enable early detection of patients. Healthcare providers and researchers increase disease awareness and improve diagnostic capabilities for timely intervention. Regulatory bodies support orphan drug development through incentives, while funding accelerates research into gene and enzyme replacement therapies. Biotechnology and pharmaceutical companies actively expand treatment options. Established reimbursement systems improve patient access, and specialized metabolic centers along with advocacy groups continuously promote better UCD care and innovation. In October 2025, Endo, a subsidiary of Mallinckrodt plc, launched a generic version of Amgen’s RAVICTI (glycerol phenylbutyrate) oral liquid after receiving FDA approval for its abbreviated new drug application. It is the first and only FDA-approved generic version of RAVICTI available in the U.S.
Asia Pacific Urea Cycle Disorder Treatment Market Trends
Rising awareness of rare metabolic diseases drives the Asia Pacific urea cycle disorder treatment market, while expanding newborn screening programs and improved access to genetic testing support earlier diagnosis. Healthcare providers strengthen healthcare infrastructure, and governments support orphan disease management, which increases detection rates. Rare (or orphan) diseases are estimated to affect 70–96 million people in India. Government guidelines generally classify a disease as rare if it affects fewer than 500,000 individuals in the country. Approximately 80% of rare diseases are genetic, and 50% occur in children, with many cases resulting in death before the age of 20. Pharmaceutical companies advance enzyme replacement therapies, ammonia scavengers, and liver transplantation options to improve outcomes. Ongoing pharmaceutical investment, clinical research in metabolic disorders, and growing patient support initiatives further accelerate market growth across the region.
United States Urea Cycle Disorder Treatment Market Trends
Rising awareness of rare genetic disorders drives the United States urea cycle disorder treatment market, while improved newborn screening programs enable early diagnosis. Pharmaceutical companies actively advance research and development in enzyme replacement therapies, nitrogen-scavenging drugs, and emerging gene therapies, supporting market expansion. Orphan drug incentives stimulate innovation, and favorable reimbursement policies improve patient access. Increasing clinical trials, advanced diagnostic tools, and specialized metabolic care centers further expand treatment options and enhance disease management outcomes across the country. For instance, Medunik USA announced the availability of Pheburane oral pellets, a taste-masked sodium phenylbutyrate formulation. It is used with a controlled diet for the long-term management of adults and children with urea cycle disorders involving CPS, OTC, or AS deficiencies.
China Urea Cycle Disorder Treatment Market Trends
China’s urea cycle disorder treatment market grows as healthcare providers and authorities increase awareness of rare metabolic diseases and expand newborn screening programs for earlier detection and intervention. The National Health Commission of China released a second batch of diagnosis and treatment guidelines covering 86 rare diseases. Improved healthcare infrastructure strengthens hospital capacity to manage metabolic disorders, while wider access to genetic testing supports faster diagnosis. Government policies on rare diseases and rising pharmaceutical investment in orphan drugs enhance treatment availability. Advancing clinical expertise and diagnostic integration further improve care delivery across urban and tier-two regions in China.
Who are the Major Companies in Urea Cycle Disorder Treatment Industry
Some of the major key players in Urea Cycle Disorder Treatment are Bausch Health Companies, Inc., Recordati Rare Diseases Inc., Lucane Pharma SA, Acer Therapeutics, Ultragenyx Pharmaceutical Inc., Aeglea BioTherapeutics, Arcturus Therapeutics Holdings Inc., Orpharma Pty Ltd., Selecta Biosciences, Inc., Abbott Laboratories, NESTLÉ S.A., DANONE S.A., and Mead Johnson & Company, LLC
Key News
- In May 2026, the FDA granted rare pediatric disease designation to SB-101, a cell-based liver therapy developed by Satellite Bio for the treatment of urea cycle disorders (UCDs).
Market Report Scope
Urea Cycle Disorder Treatment Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 528.7 Mn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 4.2% | 2033 Value Projection: | USD 640.7 Mn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | Bausch Health Companies, Inc., Recordati Rare Diseases Inc., Lucane Pharma SA, Acer Therapeutics, Ultragenyx Pharmaceutical Inc., Aeglea BioTherapeutics, Arcturus Therapeutics Holdings Inc., Orpharma Pty Ltd., Selecta Biosciences, Inc., Abbott Laboratories, NESTLE S.A., DANONE S.A., and Mead Johnson & Company, LLC | ||
Analyst Opinion
- Urea Cycle Disorder (UCD) treatment is fundamentally driven by clinical necessity rather than elective demand. UCDs are rare but severe, with an estimated global incidence of about 1 in 35,000 live births, and many patients present in neonatal stages with life-threatening hyperammonemia, making immediate intervention critical rather than optional. This creates a structurally non-discretionary treatment base across healthcare systems.
- Pharmacologic management remains the backbone of long-term survival, with nitrogen-scavenging therapies such as sodium phenylbutyrate and glycerol phenylbutyrate widely used to control ammonia levels. Clinical practice data shows that without prompt treatment, acute hyperammonemic crises can result in mortality rates exceeding 50%, underscoring how survival outcomes are directly tied to rapid therapeutic access rather than gradual disease progression trends.
- Liver transplantation continues to be a definitive curative option for severe UCD cases, with reported long-term survival rates exceeding 80%–90% in transplanted patients. However, limited donor availability and the complexity of pediatric transplants create a persistent treatment gap, reinforcing continuous demand for pharmacological and emergency metabolic management solutions across both developed and emerging healthcare systems.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- By Treatment Type (Revenue, USD Mn, 2021-2033)
- Amino Acid Supplements
- Sodium Phenylbutyrate
- Glycerol Phenylbutyrate
- Sodium Benzoate
- Others (Low Protein Diet, Carglumic acid, etc.)
- By Enzyme Deficiency Type (Revenue, USD Mn, 2021-2033)
- OTC – Ornithine Transcarbamylase
- AS – Argininosuccinate Synthetase (citrullinemia)
- AG – Arginase
- AL – Argininosuccinate Lyase
- CPS1 – Carbamoyl Phosphate Synthase
- NAGS – N-acetylglutamate Synthase
- By Route of Administration (Revenue, USD Mn, 2021-2033)
- Oral
- Injectable
- By Distribution Channel (Revenue, USD Mn, 2021-2033)
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- By Region (Revenue, USD Mn, 2021-2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Rest of Latin America
- Europe
- Germany
- U.K.
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- South Africa
- Central Africa
- North Africa
- North America
Sources
Primary Research interviews
- Interviews with endocrinologists, hepatologists, metabolic disorder specialists, and pediatric neurologists
- Discussions with hospital procurement managers and clinical research coordinators
- Inputs from caregivers and patient advocacy groups for urea cycle disorder management insights
Databases
- PubMed / MEDLINE biomedical literature database
- ClinicalTrials.gov for ongoing and completed clinical studies
- WHO Global Health Observatory data repository
- National and regional rare disease registries
- Government health ministry epidemiology datasets
Magazines
- Rare disease-focused medical magazines and healthcare industry publications
- Clinical practice and hospital management magazines covering metabolic disorders
- Biotechnology and pharmaceutical industry magazines reporting on orphan drugs
Journals
- Journal of Inherited Metabolic Disease
- Molecular Genetics and Metabolism
- Orphanet Journal of Rare Diseases
- American Journal of Medical Genetics
- Pediatrics and hepatology clinical research journals
Newspapers
- Leading national newspapers covering healthcare policy and pharmaceutical developments
- Financial newspapers reporting on drug approvals and rare disease treatments
- Health sections of mainstream newspapers reporting clinical advancements
Associations
- National rare disease patient associations
- International metabolic disorder and inborn errors of metabolism societies
- Pediatric hepatology and liver disease associations
- Orphan drug and rare disease advocacy organizations
Public Domain sources
- World Health Organization (WHO) publications and reports
- National Institutes of Health (NIH) resources
- Government health department publications and white papers
- Open-access epidemiological datasets and public health reports
- Regulatory authority drug approval announcements (e.g., FDA, EMA)
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of information for last 10 years
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Urea Cycle Disorder Treatment Market is anticipated to grow at a CAGR of 4.2% with USD 528.7 Mn share in 2026 and is expected to reach USD 640.7 Mn in 2033.
Rising prevalence of urea cycle disorders and increasing number of pipeline products are expected to drive growth of the market.
Sodium Phenylbutyrate segment is estimated to hold major market share in the market during the forecast period, owing to various companies focusing on research and development of urea cycle disorders treatments.
OTC – Ornithine Transcarbamylase segment is estimated to hold major market share in the global urea cycle disorders treatment market during the forecast period, owing to various key players focusing on research and development for the treatment of OTC – Ornithine Transcarbamylase deficiency.
Oral segment is estimated to hold major market share in the market during the forecast period, owing to major players focusing on research and development of orally administered drugs such as (Glycerol phenylbutyrate) for treatment of urea cycle disorders.
Hospital Pharmacies is estimated to hold major market share in the market during the forecast period, owing to major players focusing on conducting special awareness programs and financial assistance programs for the treatment of urea cycle disorders through healthcare facilities.