
Gear Reducer Market Size and Share Analysis – 2026 To 2033
The Global Gear Reducer Market size is anticipated to grow at a CAGR of 6.6%, from USD 10.39 Bn in 2026 to USD 16.26 Bn by 2033. The key drivers of growth are rising industrial automation, growing demand for energy-efficient power transmission systems, expanding manufacturing activities, increasing adoption of robotics, and rising investments in renewable energy and heavy machinery. Moreover, increasing adoption of gear reducers in automotive manufacturing, material handling equipment, wind turbines, and industrial machinery are expected to fuel the market growth during the forecast period. The International Federation of Robotics (IFR) reported that some 542,000 industrial robots were installed globally in 2024, with the global operational stock reaching 4.66 million units, a 9% increase from the previous year.
Key Takeaways
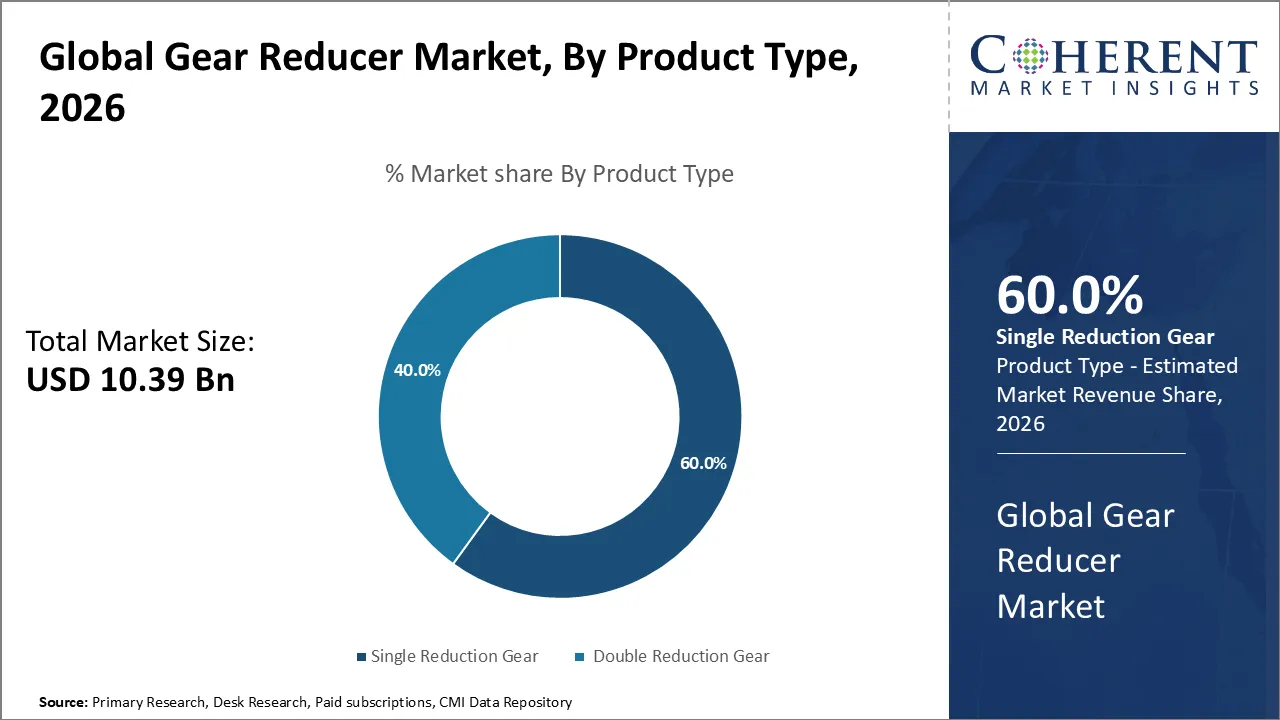
- The single reduction gear segment is expected to continue to hold a major market share of 60% in 2026. The segment growth is attributed to its simple design, lower maintenance, cost-effectiveness and its wide application in automotive and industrial machinery. The International Organization of Motor Vehicle Manufacturers (OICA) reports that the global production of motor vehicles rose 3.9% to 96.4 million units in 2025, boosting demand for automotive manufacturing equipment and associated power transmission systems.
- The commercial cars segment is projected to hold an estimated 34.5% share of the Global Gear Reducer Market in 2026. The segment’s growth can be attributed to the rising production of vehicles, increasing demand for efficient power transmission systems, growing adoption for automated vehicle manufacturing, and advancements in automotive drivetrain technologies. The European Automobile Manufacturers’ Association (ACEA) said new registrations of EU trucks grew 9.8% to 171,933 units in the first half of 2026 while van registrations climbed 1.9% to 742,759 units. The figures show recovering demand in the commercial vehicle industry.
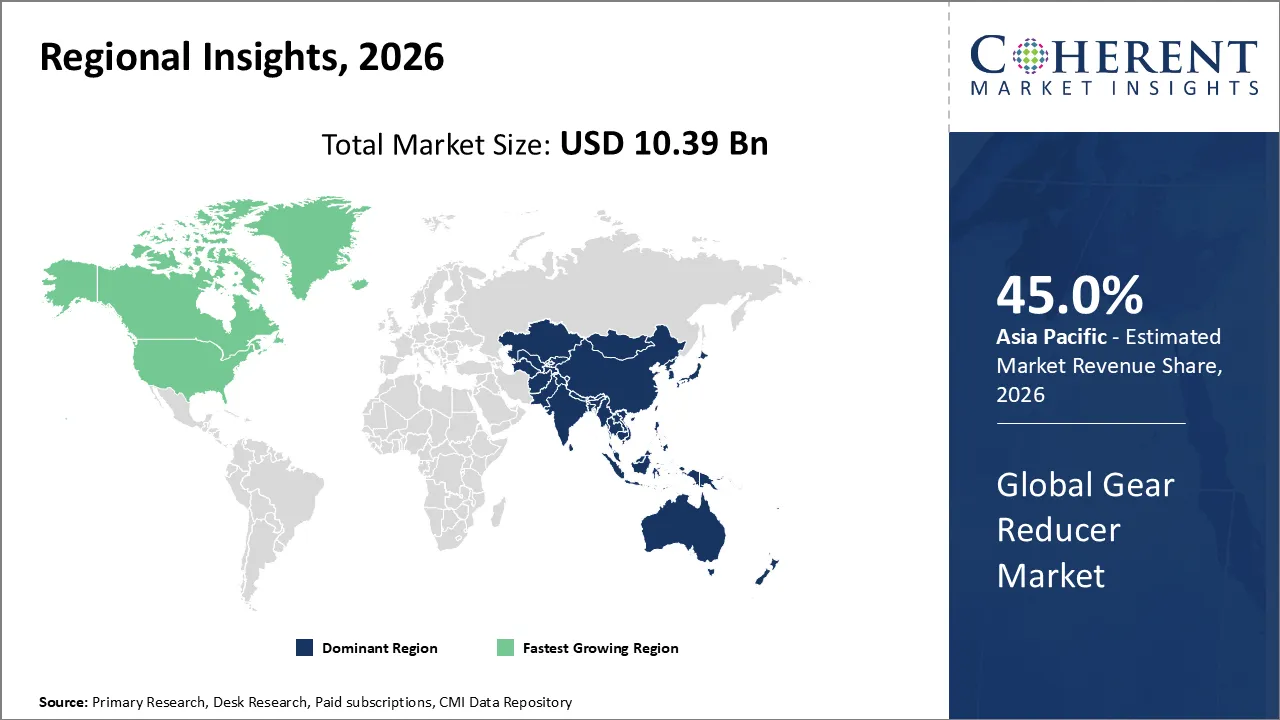
- The Asia Pacific region is expected to lead the Global Gear Reducer Market, holding an estimated market share of 45.0% in 2026. The growth of the region is attributed to the growing automotive production, industrial manufacturing, rising investments in renewable energy equipment, and rising adoption of automated machinery in China, India, Japan, and South Korea. According to a March 2026 UNIDO report China's manufacturing output saw its strongest growth in the fourth quarter of 2025 relative to the rest of Asia Pacific, showing that industrial activity continued across the region.
Market Drivers
Rising Industrial Automation and Robotics Adoption is Driving the Gear Reducer Market
The global market for gear reducers is growing steadily owing to the increasing use of industrial automation, robotics and sophisticated manufacturing equipment. Gear reducers are essential in managing speed, improving torque, and facilitating accurate motion in robotic arms, conveyor systems, and automated manufacturing lines. With the increasing demand for efficient and reliable machinery, industries are turning to precision gear reduction systems.
The International Federation of Robotics (IFR) reports that in 2025, worldwide industrial robot installations increased by 11% to over 600,000 units and the total number of industrial robots in operation worldwide grew by 9% to around 5 million units compared to the previous year.
In September 2026, IFR also reported China’s installations of industrial robots grew by 20% in 2025 to 354,000 units, or 59% of the world’s installations. The growth of industrial robotics in leading manufacturing countries is creating a demand for small, high torque, precision gear reducers.
Growing Demand for Energy-Efficient Machinery and Wind Power Equipment is Supporting Market Growth
Another key driver of the global gear reducer market is the increasing emphasis on energy efficiency and renewable energy development. Industries are adopting energy-efficient motors and power transmission systems to reduce electricity consumption, improve machinery performance and reduce operational costs. Gear reducers are often used in electric motor driven equipment such as pumps, conveyors, mixers and many other industrial machines where desired speed and torque must be attained.
According to the International Energy Agency (IEA), industrial electric motor systems account for around 60% of global industrial electricity demand and about 25% of total global electricity consumption.
Current Events and Their Impact on the Gear Reducer Market
Current Event | Description and its Impact |
European Commission Initiates Review of Electric Motor and Variable Speed Drive Efficiency Regulations (2025–2026) |
|
U.S. Department of Energy Establishes New Electric Motor Efficiency Compliance Requirements (2025–2029) |
|
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Segmental Insights
Why is Single Reduction Gear Expected to Hold a Prominent Market Share?
On the basis of product type, the single reduction gear segment is expected to hold a prominent share of the Global Gear Reducer Market 60% in 2026. The segment is growing due to its simple design, cost effectiveness, compact structure and low maintenance requirements. These benefits make it ideal for applications in conveyor systems, industrial machinery, material handling systems and automotive applications.
According to the United Nations Industrial Development Organization (UNIDO), world manufacturing production was up by 1.5% in the second quarter of 2026, with the output of higher-technology manufacturing rising by 2.0%. This expansion is expected to increase the demand for mechanical power transmission components such as single reduction gear systems.
In August 2026, SEW-EURODRIVE launches the PxG Economy planetary servo gear unit series with the P1.G, P2.G and P3.G models. The new products are targeted to provide cost-effective gear reduction solutions for packaging machinery, material handling systems, assembly equipment and industrial automation.
Why is Commercial Cars Expected to Hold a Significant Market Share?
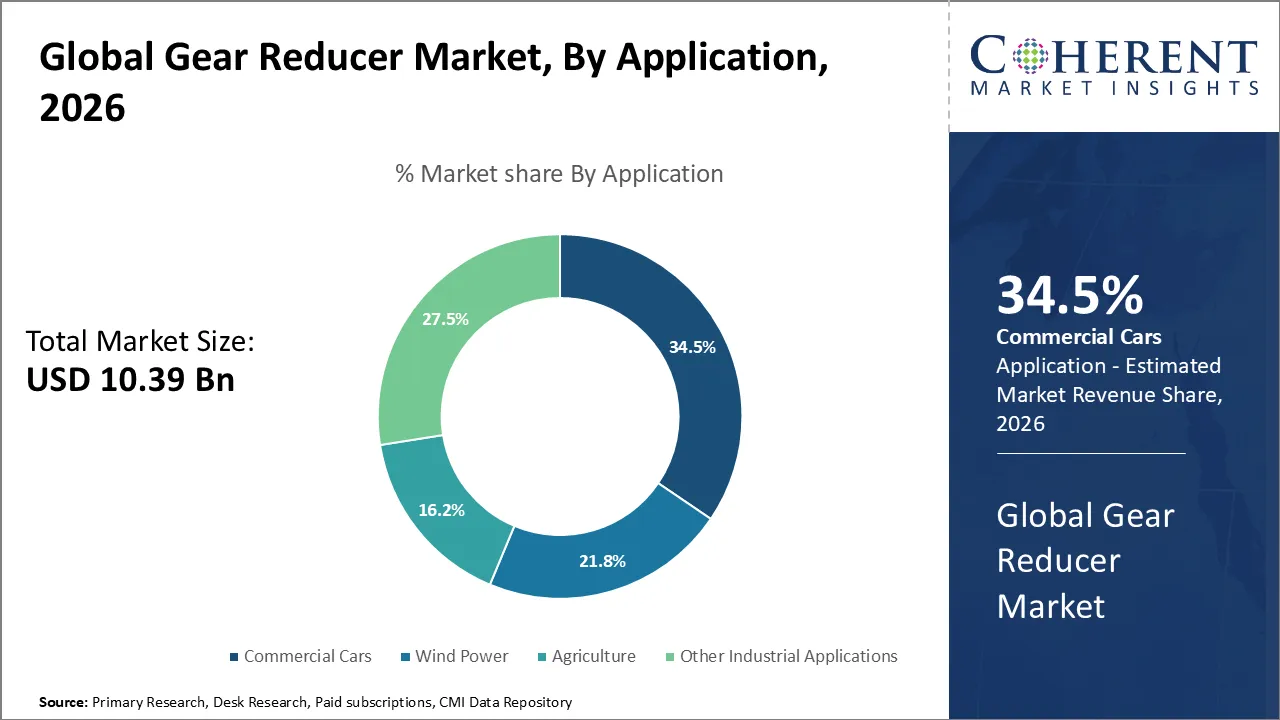
Based on application, the commercial cars segment is projected to lead the Global Gear Reducer Market by accounting for 34.5% share in 2026. Factors such as adoption of electric commercial vehicles, demand for efficient vehicle power transmission systems, commercial vehicle manufacturing and drivetrain development are likely to support the growth of the segment.
According to data from the European Automobile Manufacturers' Association (ACEA), electric vans made up 11% of all newly registered vans in the EU in 2025. As acceptance of electric commercial vehicles grows, opportunities are emerging for compact reduction gear systems that transmit motor power to vehicle drivetrains.
Moreover, the International Organization of Motor Vehicle Manufacturers (OICA) reported in April 2026 that global motor vehicle sales increased 4.7% from 95.3 million units in 2024 to 99.8 million units in 2025. This is attributed to the continuous demand from the automotive industry that enables the gear reducer opportunities for vehicle manufacturing equipment and power transmission applications.
Gear Reducer Market Trends
- The increasing demand for smaller and more powerful gear reducers is driving the development of lightweight planetary gear systems for robotics, semiconductor equipment and automated machinery. Harmonic Drive Systems unveiled its FPA Series in February 2026, which combines a precision planetary gear reducer and an AC servo motor to deliver greater equipment compactness and operational accuracy.
- The increasing focus on energy efficiency is leading to the use of integrated gearmotor systems which reduce energy losses and operating costs. At LogiMAT 2026, NORD DRIVESYSTEMS showed an expanded IE5+ motor range from 0.35 to 11 kW, up from the previous maximum of 3.7 kW. These motors can be combined with NORD gear units for industrial applications.
- The increasing use of compact gearmotors in material handling, logistics and industrial automation is reducing the need for large standalone gearbox assemblies. The industry assessment on Bonfiglioli Transmissions in February 2026 mentions that integrated gearmotors and compact drive systems are gaining traction over conventional gear box configurations in material handling equipment and intralogistics.
Regional Insights
Asia Pacific Dominates Owing to Strong Manufacturing Activity and Expanding Industrial Infrastructure
Asia Pacific is anticipated to dominate the Global Gear Reducer Market with an estimated market share of 45.0% in 2026. The growth in the region is driven by increasing manufacturing activity, rising demand for industrial machinery, growing investments in power transmission equipment and industrial development in China, India, Japan and South Korea.
According to the HSBC India Manufacturing PMI compiled by S&P Global, India's manufacturing PMI rose to 55.1 in September 2026 from 52.8 in August 2026, a seven-month high. The improvement was supported by stronger domestic and international demand, increased production, and rising new orders.
North America Gear Reducer Market Trends
North America is expected to witness strong growth in the Global Gear Reducer Market during the forecast period. The growth of the region is driven by the investments in industrial automation, increasing demand for high-precision mechanical components, modernization of manufacturing facilities, and rising adoption of advanced power transmission equipment.
The Association for Advancing Automation (A3) says North American companies bought 8,940 industrial robots valued at $622 million in the second quarter of 2026. Orders for robots increased by 4.3% in volume, and order value increased by 21.3% compared to the second quarter of 2025.
Further, the U.S. Census Bureau reported that new orders for manufactured goods in August 2026 amounted to USD 663.5 billion, up 0.1% from July. Continued manufacturing investment and machinery demand could provide additional opportunities for industrial gear reducer manufacturers.
Rising Industrial Machinery Orders and Manufacturing Investments are Supporting the Gear Reducer Market in the United States
The U.S. Gear Reducer Market is expected to grow with a steady CAGR attributed to increasing investments in industrial machinery, demand for efficient power transmission equipment and modernization of manufacturing facilities. The growing use of gear reducers in conveyors, packaging equipment, construction machinery and automated production systems drives the market demand.
In October 2026, the U.S. Census Bureau reported that orders for machinery rose 1.1% in August 2026 and orders for non-defense capital goods, excluding aircraft, rose 1.6%. This indicates improving business investment in industrial equipment, which could support demand for precision gear reducers and integrated gearmotor systems.
China Gear Reducer Market Trends
China is expected to witness strong growth in the Gear Reducer Market during the forecast period. The country’s growth is supported by a large industrial manufacturing base, increasing production of heavy machinery, expanding equipment manufacturing activities and rising demand for reliable mechanical power transmission systems.
In September 2026, the National Bureau of Statistics also reported that China's general-purpose machinery manufacturing output increased by 9.8% year-on-year in August 2026, while special-purpose machinery manufacturing grew by 11.4%. The expansion of machinery manufacturing is expected to strengthen opportunities for domestic gear reducer suppliers and manufacturers of industrial power transmission equipment.
Who are the Major Companies in Gear Reducer Industry
Some of the major key players in Gear Reducer Market are IPTS, Inc., NORD Drivesystems, Altra Industrial Motion Corp., Apex Dynamics, Inc., Ondrives.US Corporation, Siemens, Li Xiang Mach & Elec Co., Ltd, JVL Industri Elektronik, Boneng Transmission Co., LTD, Zhejiang Ever-Power Transmission Co. Ltd., FIXEDSTAR, and HBReducer.
Key News
- In July 2026, NORD DRIVESYSTEMS highlighted its MAXXDRIVE industrial gear unit series, designed for heavy-duty applications such as container cranes, conveyor systems, and biogas equipment.
- In April 2026, NORD DRIVESYSTEMS showcased its NORDBLOC.1 inline gear units and two-stage helical bevel gear units at MODEX 2026 in Atlanta. The product portfolio includes gear units for conveyor systems, warehouse automation and industrial processing. The two-stage helical bevel units achieve efficiencies of up to 97%.
Market Report Scope
Gear Reducer Market Report Coverage
Report Coverage | Details | ||
Base Year: | 2025 | Market Size in 2026: | USD 10.39 Bn |
Historical Data for: | 2020 to 2024 | Forecast Period: | 2026 to 2033 |
CAGR: | 6.6% | 2033 Value Projection: | USD 16.26 Bn |
Geographies covered: |
| ||
Segments covered: |
| ||
Companies covered: | IPTS, Inc., NORD Drivesystems, Altra Industrial Motion Corp., Apex Dynamics, Inc., Ondrives.US Corporation, Siemens, Li Xiang Mach & Elec Co., Ltd, JVL Industri Elektronik, Boneng Transmission Co., LTD, Zhejiang Ever-Power Transmission Co. Ltd., FIXEDSTAR, and HBReducer. | ||
Growth Drivers: |
| ||
Restraints & Challenges: |
| ||
Analyst Opinion
- The Gear Reducer Market is expected to benefit from increasing investments in advanced manufacturing equipment and industrial machinery. According to the Association for Manufacturing Technology (AMT), U.S. manufacturing technology orders reached USD 4.03 billion during January–July 2026, increasing by 37.1% compared with the same period in 2025.
- Gear reducer manufacturers are expected to benefit from government-funded industrial equipment modernization programs. In January 2026, China’s Ministry of Finance announced an equipment renewal financing policy that includes a 1.5-percentage-point interest subsidy for eligible equipment loans for a period of up to two years. This policy may encourage manufacturing companies to upgrade industrial machinery, increasing the demand for gear reducers for automated production, logistics, and heavy equipment.
- Manufacturers are focusing on productivity and equipment modernization which is expected to drive the market due to increasing demand for reliable and efficient gear reduction systems. Capital goods production in the EU was up 0.5% in July 2026 compared with June 2026, Eurostat said, while industrial production overall was down 0.3%.This indicates continued activity in capital goods manufacturing, creating potential opportunities for suppliers of gear reducers, gearmotors, and mechanical power transmission components.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- By Product Type (Revenue, USD Bn, 2021-2033)
- Single Reduction Gear
- Double Reduction Gear
- By Application (Revenue, USD Bn, 2021-2033)
- Commercial Cars
- Wind Power
- Agriculture
- Other Industrial Applications
- By Region (Revenue, USD Bn, 2021-2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Rest of Latin America
- Europe
- Germany
- U.K.
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- South Africa
- Central Africa
- North Africa
- North America
Sources
Primary Research Interviews
- Gear reducer and gearbox manufacturers
- Industrial power transmission equipment manufacturers
- R&D heads from gear reducer and gearmotor companies
- Industrial automation and robotics experts
- Automotive drivetrain and transmission engineers
- Wind turbine gearbox and renewable energy equipment specialists
- Industrial machinery and manufacturing equipment procurement managers
- Key opinion leaders (KOLs) in mechanical power transmission and industrial engineering
Databases
- World Bank
- Organisation for Economic Co-operation and Development (OECD)
- United Nations Industrial Development Organization (UNIDO)
- International Energy Agency (IEA)
- U.S. Census Bureau
- Eurostat
- National Bureau of Statistics of China (NBS)
- U.S. Bureau of Economic Analysis (BEA)
Magazines
- Power Transmission Engineering
- Gear Technology
- Machine Design
- Design World
- Manufacturing Engineering
- Motion Control Tips
Journals
- Mechanism and Machine Theory
- Journal of Mechanical Design
- Tribology International
- Engineering Failure Analysis
- International Journal of Mechanical Sciences
- Journal of Manufacturing Processes
Newspapers
- The Wall Street Journal
- Financial Times
- Reuters
- The Economic Times
- The Guardian
Associations
- American Gear Manufacturers Association (AGMA)
- American Society of Mechanical Engineers (ASME)
- International Federation of Robotics (IFR)
- Association for Manufacturing Technology (AMT)
- European Association of Automotive Suppliers (CLEPA)
- International Organization of Motor Vehicle Manufacturers (OICA)
- European Power Transmission Distributors Association (EPTDA)
Public Domain Sources
- Company Annual Reports and Investor Presentations
- Government Industrial Manufacturing and Machinery Production Statistics
- Gear Reducer and Gearmotor Manufacturer Product Catalogs
- Industrial Automation and Robotics Industry Publications
- Automotive and Wind Energy Equipment Production Reports
- Patent Databases such as WIPO, USPTO, and Google Patents
- Regulatory and Standards Publications Related to Gearboxes, Electric Motors, and Energy Efficiency
- Publicly Available Technical Research Reports on Mechanical Power Transmission Systems
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of Information for the Last 10 Years
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Global Gear Reducer Market is expected to reach USD 16.26 Bn in 2033, compared to USD 10.39 Bn in 2026.
Major players operating in the global Gear Reducer Market include IPTS, Inc., NORD Drivesystems, Altra Industrial Motion Corp., Apex Dynamics, Inc., Ondrives.US Corporation, Siemens, Li Xiang Mach & Elec Co., Ltd, JVL Industri Elektronik, Boneng Transmission Co., LTD, Zhejiang Ever-Power Transmission Co. Ltd., FIXEDSTAR, and HBReducer.
High initial investment and installation costs, rising raw material prices, increasing manufacturing expenses, and maintenance requirements are the key factors hampering market growth.
Increasing industrial automation, rising demand for energy-efficient power transmission systems, growing automotive manufacturing, and expanding use of gear reducers in industrial machinery are driving market growth.
The Gear Reducer Market is anticipated to grow at a CAGR of 6.6% between 2026 and 2033.
Asia Pacific is expected to account for the largest share of the global Gear Reducer Market in 2026, with an estimated market share of 45.0%.
A gear reducer is a mechanical device that reduces the rotational speed of a motor while increasing torque. It is commonly used in industrial machinery, automotive systems, conveyor equipment, and manufacturing applications.