
U.S. Non-oncology Biopharmaceuticals Market Size and Trends: 2026-2033
U.S. non-oncology biopharmaceuticals market is estimated to be valued at USD 252 Bn in 2026 and is expected to reach USD 497 Bn by 2033, exhibiting a compound annual growth rate (CAGR) of 10.2% from 2026 to 2033.
Key Takeaways
- Based on Product Type, the Biologics segment is expected to lead the market with 85% share in 2026, due to their widespread use across chronic and complex disease treatments.
- Based on Drug Class, the Monoclonal Antibody segment is expected to hold 40% share of the market in 2026, owing to their extensive application in autoimmune, inflammatory, and metabolic disorders.
- By Disease Indication, Diabetes is projected to account for 18% share of the market in 2026, driven by strong demand for human recombinant insulin and other biologic therapies.
Market Overview
Rising incidence of chronic diseases like diabetes, autoimmune diseases, and rare genetic disorders is fueling the demand for biopharmaceuticals that are not used in oncology in the U.S. The rising trend of using biologics like monoclonal antibodies, recombinant proteins, and insulin-based therapies is propelling the growth of the biopharmaceutical market. Constant developments in biotechnology and R&D investment have resulted in the entry of innovative drugs that have better efficacy and safety.
Current Events and Its Impacts on the U.S. Non-oncology Biopharmaceuticals Market
Current Events | and its impact |
FDA Regulatory Reform and Policy Changes |
|
Medicare Drug Price Negotiation Implementation |
|
How is Product Innovation driving the growth in the U.S. non-oncology biopharmaceuticals market?
- Next-Generation Biologics: Improvements in the manufacture of more potent monoclonal antibodies, fusion proteins, and enzyme therapies with greater safety profiles and longer dosing cycles.
- Targeted Therapies: Precision medicine targeted at specific patients with a certain genetic profile or disease fingerprint.
- Advanced Drug Delivery Systems: These include sustained release systems, prefilled pens, and automatic injectors meant to enhance patient compliance.
- Combination Therapies: Utilization of biopharmaceuticals as a combination with traditional pharmaceuticals or biologics to provide improved efficacy against chronic diseases.
- Wireless Health Integration: Devices that allow for tracking of patient response to treatment and treatment compliance.
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Segmental Insights
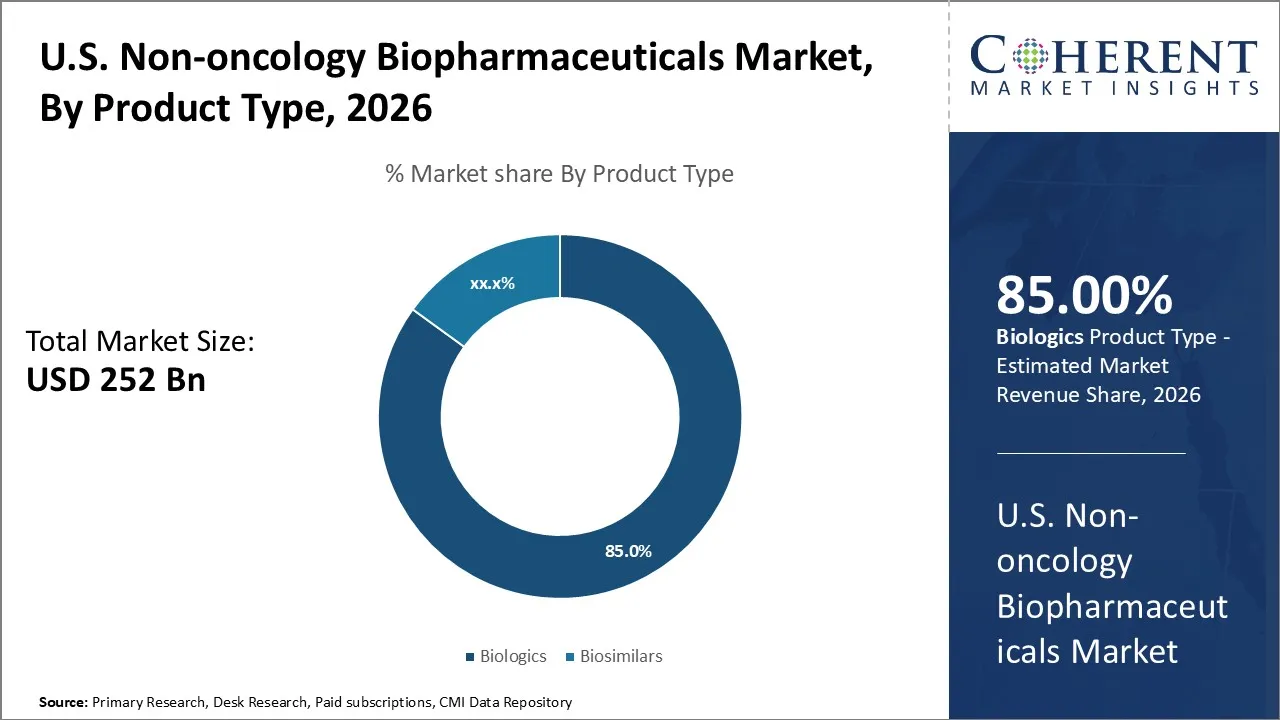
U.S. Non-Oncology Biopharmaceuticals Market Insights, By Product Type – Biologics dominate due to widespread use in chronic and complex diseases
Based on product type, the Biologics segment is projected to hold the highest market share of 85% in 2026, due to its widespread demand and application within the treatment of chronic and complex diseases. Biologics, such as monoclonal antibodies, recombinant proteins, and hormone products, form a favored class within the treatment of those diseases, in particular those with a high need for targeted and more effective and safe drugs.
For instance, in July 2025, Biocon Biologics received U.S. FDA approval for their product, “Kirsty™”, which is the “first and only interchangeable rapid-acting insulin aspart biosimilar,” a biologic, for treatment of diabetes in the United States.
U.S. Non-Oncology Biopharmaceuticals Market Insights, By Drug Class – Monoclonal Antibodies lead due to targeted applications in autoimmune and metabolic disorders
In terms of drug class, the Monoclonal Antibody segment is estimated to contribute the highest market share of 40% in 2026, owing to their widespread application in autoimmune, inflammatory, and metabolic disorders. Monoclonal antibodies are highly specific therapies that target disease-causing proteins, offering improved efficacy and reduced side effects compared to traditional treatments.
For instance, in April 2025, Johnson & Johnson achieved FDA approval for its new treatment IMAAVY™ (nipocalimab-aahu), a new monoclonal antibody that blocks the mechanism of FcRn to treat generalized myasthenia gravis (gMG) for individuals 12 years of age and older.
U.S. Non-Oncology Biopharmaceuticals Market Insights, By Disease Indication – Diabetes leads due to strong demand for human recombinant insulin and other biologics
Based on disease indication, Diabetes is expected to hold a market share of 18% in 2026, led by high demand for human recombinant insulin, GLP-1 analogues, and other biological products. The incidence rate of diabetes, awareness among patients, and advancements in devices to deliver insulin are some factors contributing to this growth.
For instance, in February 2025, the U.S. FDA approved Merilog (insulin-aspart-szjj), a new biosimilar insulin with a quick-acting indication (to Novolog), for the improvement of glycemic control in adults as well as pediatric patients with diabetes
Market Report Scope
U.S. Non-oncology Biopharmaceuticals Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 252 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 10.2% | 2033 Value Projection: | USD 497 Bn |
| Segments covered: |
| ||
| Companies covered: | Sanofi S.A., Pfizer, Inc., Johnson & Johnson, Novartis International AG, Amgen, Inc., Eli Lilly and Company, AbbVie Inc., Bristol-Myers Squibb Company, F. Hoffmann-La Roche AG, Novo Nordisk A/S, GlaxoSmithKline plc., UCB Pharma, Teva Pharmaceutical Industries Ltd., Takeda Pharmaceutical Company Ltd, AstraZeneca Plc, Mylan N.V., LEO Pharma A/S, Boehringer Ingelheim GmbH, Alexion Pharmaceuticals Inc., Merck & Co., Inc., Elusys Therapeutics, Inc., Swedish Orphan Biovitrum AB, Samsung Bioepis NL B.V., Biogen Inc., and Theratechnologies Inc. | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
U.S. Non-Oncology Biopharmaceuticals Market Driver
Rising prevalence of chronic and rare diseases
Rise in prevalence of chronic diseases like diabetes, autoimmune diseases, and rare genetic disorders in the U.S. drives the demand for non-oncology biopharmaceuticals. Patients and healthcare professionals are also demanding innovative biologic medications such as monoclonal antibodies, enzyme replacements, and recombinant proteins due to their greater potency and safety compared to conventional medications. Increasing awareness and treatment rates of such diseases also fuel the demand.
U.S. Non-Oncology Biopharmaceuticals Market Opportunity
Innovation in biologics and biosimilars
The market offers considerable growth opportunities in the next-generation biologics and biosimilars area. The launch of new therapies with optimized dosing regimens, advanced delivery platforms, or mechanism of action can help in improving patient compliance and extending the therapeutic armamentarium. Furthermore, extending the biosimilar offering can help in making the therapies more affordable, which can also be a competitive edge opportunity in the market.
Analyst Opinion (Expert Opinion)
- The U.S. non-oncology biopharmaceuticals market is undergoing a strategic shift in becoming a highly innovative segment. The monoclonal antibodies have largely become mainstream therapies in autoimmune, metabolic, and inflammatory diseases, not only due to their relevance in the respective conditions, but also owing to the pricing power they have been able to demonstrate.
- Pipeline activity and launch of products reflect that the market is shifting towards the era of precision and convenience-based treatments. Next-generation biologics are also being developed with better treatment regimen options, patient-friendly delivery methods, and combination strategies, which improve patient compliance and extend the patient base.
- Strategically, investments are happening in the arena of portfolio diversification management. Biologics continue to represent high-revenue therapeutic areas, but intelligent growth into biosimilars, niche rare diseases, and holistic digital health is a key differentiator. Today, the pharmaceutical market is no longer defined by the development of a molecule alone, but more and more by patient-oriented distribution and affordability and evidence-based outcomes.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
U.S. Non-oncology Biopharmaceuticals Industry News
- In December 2025, Emcutix Biopharmaceuticals Limited—a dermatology-focused, wholly owned subsidiary of Emcure Pharmaceuticals Ltd. unveiled SOLGLO-AZ Liposomal Serum, featuring a unique formulation powered by Lipotwin Technology and the Hyperboost Brightening Complex.
Market Segmentation
- Product Type Insights (Revenue, USD Bn, 2026 - 2033)
- Biologics
- Biosimilars
- Drug Class Insights (Revenue, USD Bn, 2026 - 2033)
- Monoclonal Antibody
- Enzyme Replacement Therapy
- Erythropoietin
- Interferon
- Colony-stimulating Factor
- Botulinum Toxin
- Fusion Protein
- Vaccines
- Human Recombinant Insulin
- Blood Factors
- Human Growth Hormone
- Others
- Disease Indication Insights (Revenue, USD Bn, 2026 - 2033)
- Diabetes
- Rheumatoid Arthritis
- Psoriatic Arthritis
- Multiple Sclerosis
- Hemophilia
- Anemia
- Age-related Macular Degeneration
- Hepatitis B
- Cystic Fibrosis
- Osteoporosis
- Crohn’s Disease
- Ulcerative Colitis
- Psoriasis
- Ankylosing Spondylitis
- Others (Cardiac diseases and others)
- Key Players Insights
- Sanofi S.A., Pfizer, Inc.
- Johnson & Johnson
- Novartis International AG
- Amgen, Inc.
- Eli Lilly and Company
- AbbVie Inc.
- Bristol-Myers Squibb Company
- Hoffmann-La Roche AG,
- Novo Nordisk A/S
- GlaxoSmithKline plc.
- UCB Pharma
- Teva Pharmaceutical Industries Ltd.
- Takeda Pharmaceutical Company Ltd
- AstraZeneca Plc
- Mylan N.V.
- LEO Pharma A/S
- Boehringer Ingelheim GmbH
- Alexion Pharmaceuticals Inc.
- Merck & Co., Inc.
- Elusys Therapeutics, Inc.
- Swedish Orphan Biovitrum AB
- Samsung Bioepis NL B.V., Biogen Inc.
- Theratechnologies Inc
Sources
Primary Research interviews
- Interviews with key executives, medical affairs specialists, and R&D leaders from leading U.S. biopharmaceutical companies such as AbbVie, Amgen, Pfizer, Johnson & Johnson, and Novartis.
- Discussions with oncologists, endocrinologists, and autoimmune disease specialists to understand treatment patterns, adoption of biologics, and patient preferences.
Databases
- U.S. FDA Drug Approvals Database (Drugs@FDA)
- ClinicalTrials.gov – registry of ongoing and completed clinical trials
- National Library of Medicine (PubMed) databases for clinical and pharmacological data
- U.S. Centers for Medicare & Medicaid Services (CMS) data for drug utilization and reimbursement trends
Magazines
- Pharmaceutical Executive
- BioPharm International
- Genetic Engineering & Biotechnology News (GEN)
Journals
- New England Journal of Medicine (NEJM)
- The Lancet
- Journal of Clinical Oncology (JCO)
- Nature Biotechnology
Newspapers
- The Wall Street Journal – Health & Pharmaceuticals Section
- The New York Times – Health & Science Section
- Reuters Health & Pharma News
- Financial Times – Healthcare & Biopharma News
Associations
- Pharmaceutical Research and Manufacturers of America (PhRMA)
- Biotechnology Innovation Organization (BIO)
- American Diabetes Association (ADA)
- American Autoimmune Related Diseases Association (AARDA)
Public Domain sources
- U.S. National Institutes of Health (NIH) publications and reports
- U.S. Food and Drug Administration (FDA) press releases
- Centers for Disease Control and Prevention (CDC) disease statistics
- U.S. Department of Health & Human Services (HHS) policy reports
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of information for last 8 years
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The U.S. Non-Oncology Biopharmaceuticals Market is estimated to be valued at USD 252 Bn in 2026, and is expected to reach USD 497 Bn by 2033.
The CAGR of the U.S. Non-Oncology Biopharmaceuticals Market is projected to be 10.2% from 2026 to 2033.
Rising prevalence of chronic diseases, growing adoption of biologics and targeted therapies, product innovation in delivery systems, and expansion of biosimilars are major factors driving market growth
High therapy costs, complex regulatory approvals, and limited patient access in certain rare disease segments are major factors hampering market growth.
The biologics segment is expected to lead the market, driven by widespread application in chronic and complex diseases.
Sanofi S.A., Pfizer, Inc., Johnson & Johnson, Novartis International AG, Amgen, Inc., Eli Lilly and Company, AbbVie Inc., Bristol-Myers Squibb Company, F. Hoffmann-La Roche AG, Novo Nordisk A/S, GlaxoSmithKline plc., UCB Pharma, Teva Pharmaceutical Industries Ltd., Takeda Pharmaceutical Company Ltd, AstraZeneca Plc, Mylan N.V., LEO Pharma A/S, Boehringer Ingelheim GmbH, Alexion Pharmaceuticals Inc., Merck & Co., Inc., Elusys Therapeutics, Inc., Swedish Orphan Biovitrum AB, Samsung Bioepis NL B.V., Biogen Inc., and Theratechnologies Inc.