The ESG data management sector has exploded from a compliance afterthought into a multi-billion-dollar strategic battleground. The drivers? Crystal clear: growing stringent regulations, investor pressure that's not going away, and stakeholder expectations that keep climbing. You need sophisticated systems to measure, report, and improve ESG performance with the same precision you'd apply to your financial data. Period.
Here's what happened. Ten years ago, sustainability reporting was mostly voluntary; something you did to look good or show off your environmental credentials. But today it's a completely different game. The EU's Corporate Sustainability Reporting Directive hits thousands of companies. Climate disclosure mandates are popping up everywhere. Financial regulators demand ESG integration in investment processes. What used to be a nice-to-have checkbox exercise has become the essential infrastructure you can't operate without.
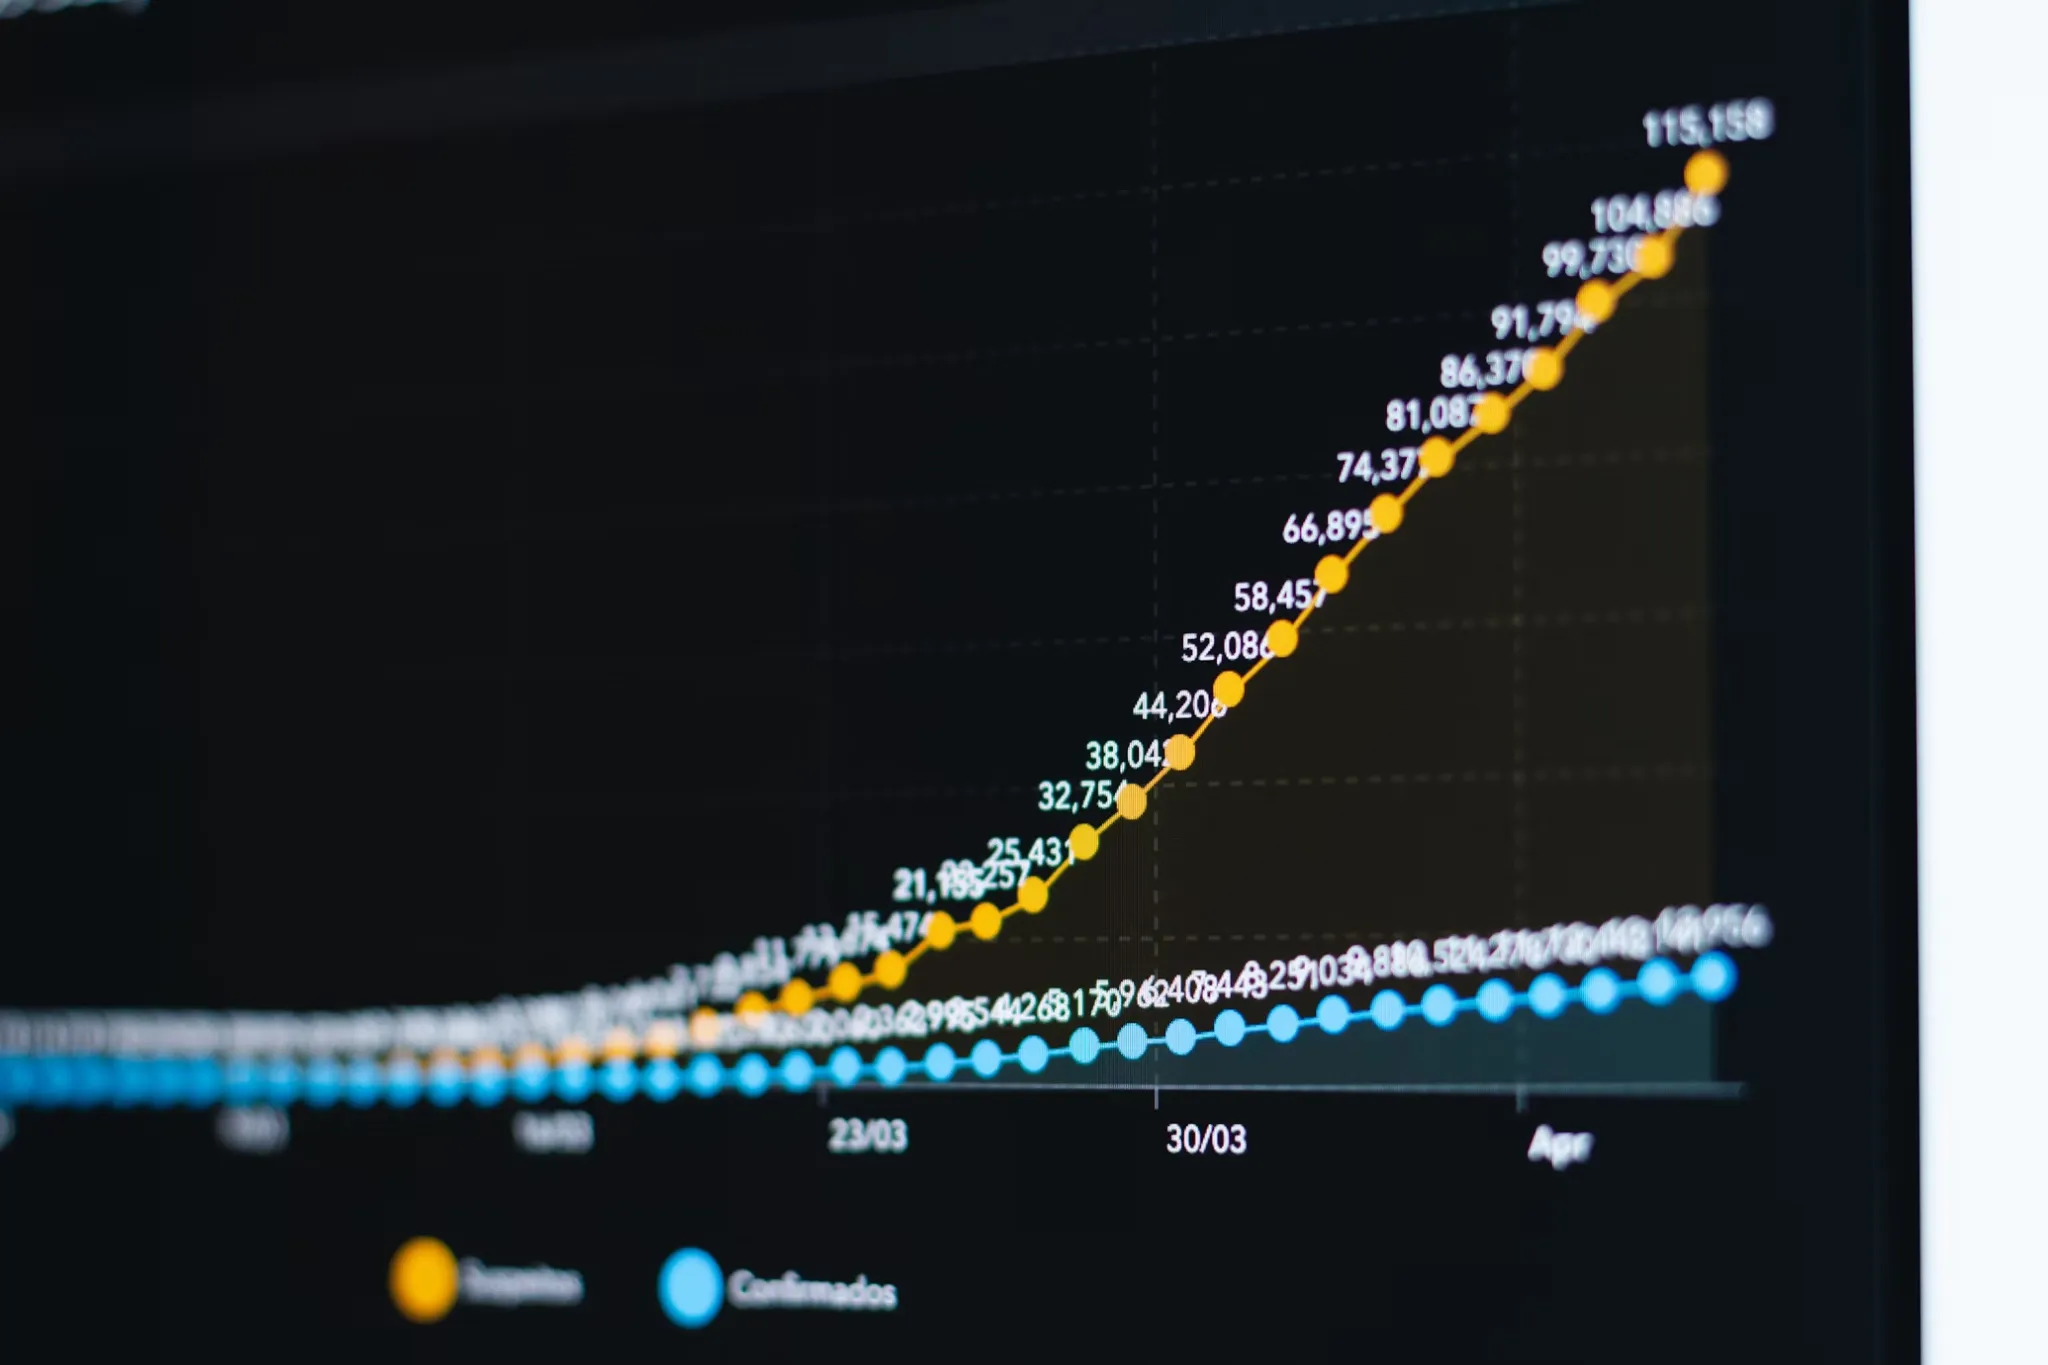
The next stage of this shift is unfolding in the ESG reporting software market, where compliance requirements are driving demand for platforms that do far more than generate annual sustainability reports. According to Coherent Market Insights, the global ESG reporting software market is estimated to be valued at USD 1.51 billion in 2026 and is expected to reach USD 3.97 billion by 2033, growing at a CAGR of 17.4 %. That trajectory reflects a fundamental change in how organisations treat sustainability information.
That distinction matters because ESG data management and ESG reporting software solve different parts of the same problem. Data management platforms focus on gathering, validating, and organising information across environmental, social and governance metrics, while reporting software transforms that structured information into disclosures that satisfy regulators, investors, lenders, and customers. As disclosure frameworks become more demanding, companies increasingly expect these capabilities to work together rather than operate as separate systems, making integration a competitive advantage for software providers serving enterprise sustainability programs.
Provider Landscape and Market Segments
Here's the reality about ESG data management: it's an absolute nightmare. You're dealing with water consumption, trash output, energy use, biodiversity impacts, and carbon emissions across various scopes just for environmental metrics alone. Then, you've got social elements throwing everything from supply chain accountability and community involvement to health and safety, workplace diversity, and labour practices at you. On top of that, governance, risk management, corporate ethics, CEO compensation, and board membership are all demanding their piece. Each category pulls data from different systems that were never designed for sustainability reporting. It's a complete mess, and you know it.
The need for scalable, automated data management solutions isn't decreasing as global reporting requirements grow and investors incorporate ESG more deeply into their decision-making. You either get on board or get left behind.
The ESG data management market splits into segments that reflect what different customers actually need. Understanding these segments matters because if you pick the wrong provider, you'll pay through the nose for features you'll never use while missing the capabilities that actually matter to your business. Don't make such mistakes.
Environmental data platforms focus on carbon accounting and climate metrics. These providers serve manufacturers, utilities, energy companies, and other resource-heavy industries where environmental performance drives your ESG strategy. They win on calculation accuracy, comprehensive emission databases, and tight integration with operational systems that generate your environmental data. If your company's ESG priorities are heavily environmental, these specialised platforms give you deeper functionality than jack-of-all-trades solutions trying to do everything.
Comprehensive ESG platforms take a different approach. They bring environmental, social, and governance data together in a single system designed for large organisations managing ESG initiatives across multiple business units, regions, and reporting frameworks. Instead of relying on separate tools for different sustainability priorities, these platforms provide one centralised place to manage data, streamline reporting, and maintain consistency across the entire organisation.
This is also where reporting software providers have strengthened their market position. Coherent Market Insights notes that software offerings are expected to account for roughly 80.3 % of the market in 2026, reflecting customer preference for configurable platforms rather than service-heavy manual reporting processes. Organisations increasingly want systems that automate repetitive work, consolidate information from finance, procurement, operations, and human resources, and generate output across multiple reporting frameworks without rebuilding workflows every reporting cycle. That flexibility has become especially valuable as businesses expand internationally and face different disclosure expectations across jurisdictions.
Investment-focused ESG data providers serve a completely different market. Asset managers, institutional investors, and financial institutions rely on company-level ESG data to evaluate portfolios, identify potential risks, and meet regulatory reporting requirements. Their positioning is generally focused on breadth rather than depth, as covering thousands of public companies is often more important than providing granular operational data for individual organisations.
Supply chain ESG platforms help you assess and monitor supplier performance on sustainability criteria. These providers tackle the growing challenge of Scope 3 emissions and broader value chain impacts that increasingly fall within disclosure requirements. These platforms may include supplier assessment questionnaires, risk monitoring capabilities, and collaboration features that let you engage suppliers on improvement initiatives. Their positioning is about extending your ESG visibility beyond your organisation into the extended value chains where most sustainability impacts actually occur.
Supply chain reporting has become one of the clearest examples of why software capabilities now influence competitive positioning. Scope 3 emissions, supplier labour practices, and procurement transparency all require information that often sits outside an organisation's direct control. ESG reporting software increasingly supports these programmes by creating structured workflows for supplier questionnaires, document collection, progress tracking, and ongoing monitoring. Instead of treating supplier assessments as one-off compliance exercises, businesses are building continuous reporting processes that improve visibility across extended value chains while strengthening audit readiness for future disclosures.
ESG ratings and benchmarking providers serve a different purpose by showing how a company’s performance compares with its peers and how it may be viewed by investors and other external stakeholders. Although these organisations are not traditional ESG data management providers, their ratings and assessment methods have a direct influence on the type and quality of data companies need to collect and maintain. Looking across these provider categories shows how differently the market operates, with each group serving its own customers, data requirements, and business priorities.
Competitive Landscape and Key Differentiators
Technology architecture plays an important role when organisations choose an ESG data management solution. Cloud based platforms can offer faster implementation, easier scaling, and lower infrastructure costs compared with traditional on premise systems that require significant upfront investment and ongoing maintenance. Cloud solutions can be particularly enterprise may continue to consider on premise or hybrid deployments because of data control and infrastructure requirements.
Cloud adoption has become one of the strongest competitive themes across the ESG reporting software market. Coherent Market Insights estimates cloud-based deployment to account for approximately 60.2 % of the market in 2026, driven by easier implementation, lower upfront costs, and the ability to support distributed sustainability teams through secure web-based access. As hybrid work becomes standard across many industries, organisations increasingly prefer platforms that allow finance teams, sustainability specialists, operational managers, and external auditors to access the same reporting environment without relying on complex on-premises infrastructure.
One of the key competitive factors is the breadth and quality of data coverage; providers compete on company coverage, geographic reach, historical data, and the frequency of updates. The providers you're evaluating are competing on company count, geographic reach, how far back their historical data goes, and how frequently they update everything. But here's the problem you need to understand: environmental and social data availability varies widely across companies and regions. The smart providers fill these gaps through estimates, alternative data sources, and direct company outreach. What increasingly separates the winners from the losers? How accurate and transparent they are about these methods, especially as you and other buyers get savvier about data quality.
Framework alignment becomes critical when you're facing multiple disclosure demands from different regulators. The providers supporting more standards reduce your integration headaches significantly. But keeping up is tougher than it looks; new frameworks and updates keep coming at you constantly. How fast your provider adapts to regulatory shifts will directly impact their market position, and yours.
Integration capabilities drive competitive success more than any other factor. Nobody wants sustainability data trapped in isolated systems anymore, and neither should you. The providers with solid APIs, ready-made connectors to standard enterprise software, and flexible data exchange options win business consistently. Financial system integration has become especially critical as companies align their financial and sustainability reporting. You need this integration to work seamlessly, or you'll find yourself dealing with data silos that make reporting a nightmare.
Regional dynamics also influence these competitive differences. Coherent Market Insights identifies North America as the leading regional market, expected to account for around 40.2 % of the global market share in 2026. Strong regulatory activity, established technology vendors, and widespread corporate sustainability programmes have accelerated enterprise adoption across the region.
Market Outlook and Strategic Implications
Partnerships have also become an important part of growth strategies. ESG providers are increasingly teaming up with accounting firms, IT companies, and consulting firms to broaden what they can offer to clients. These partnerships also help them enter new markets and provide customers with more practical support when putting ESG systems and processes into place.
The competitive landscape itself reflects how quickly the category has matured. Established enterprise software companies now compete alongside specialised sustainability providers, each approaching the market from different strengths. Companies such as Diligent Corporation, Cority, Workiva, SAP, Intelex Technologies, Salesforce, Benchmarks Digital Partners, Nasdaq, Novisto, Brightest, UL Solutions, Sphera, Wolters Kluwer, Greenstone+ and Emex Software represent a mix of governance specialists, enterprise software providers, financial information companies, and sustainability focused platforms competing across different customer segments.
This growing competition ultimately benefits buyers because it pushes providers beyond basic compliance functionality. Instead of competing solely on reporting templates, vendors increasingly invest in automation, advanced analytics, audit readiness and enterprise integrations that help organisations connect sustainability reporting with broader operational performance.
Instead of believing that larger platforms are necessarily superior, tailor the qualities of the suppliers you choose to your particular demands.
Moreover, companies with mainly environmental concerns and strong technical teams often get more value from specialised environmental platforms than general ESG systems trying to do everything.
Investment firms need capabilities operating companies don't, making focused platforms better fits despite their narrower scope
Getting this right saves you from paying for features you'll never touch or choosing solutions too shallow where you actually need depth.

