

3D Printed Medical Implants Market Analysis & Forecast: 2026 to 2033
3D printed medical implants market is estimated to be valued at USD 1.40 Bn in 2026 and is expected to reach USD 4.77 Bn in 2033, exhibiting a compound annual growth rate (CAGR) of 19.1% from 2026 to 2033.
Key Takeaways
- Based on Component Type, the Material segment is expected to hold 48% share of the market in 2026.
- Based on Implantation Technology, the Laser Beam Melting segment is expected to lead the market with 47.5% share in 2026.
- Based on Application, the Orthopedic segment is projected to account for 53% share of the market in 2026.
- Based on End User, the Medical and Surgical Centers segment is projected to capture 50% share of the market in 2026.
- Based on Region, North America is set to lead the 3D printed medical implants market with 42% share in 2026. While, Asia Pacific is anticipated to be the fastest growing region.
Market Overview
3D printing, also known as additive manufacturing, refers to addition of successive layers of raw material to produce objects forming three-dimensional file. In medical terms, 3D printed medical implants allow surgeons in surgery by implantation of biological objects, reduces risks involved during surgeries, decrease in anesthesia exposure duration, and risk of infection. 3D printing is a rapidly emerging technology which empowers key manufacturer in the medical field to form the customized medical products and implant them by replacing the damaged biological structure. 3D printed medical implantation allow patients in rapid recovery and thereby, it reduces hospital stay. Moreover, preclinical testing prior to implantation of 3D printed organs reduces chances of implant rejection.
Current Events and Its Impacts on the 3D Printed Medical Implants Market
Current Events | Description and its Impact |
Regulatory Framework Evolution and Harmonization |
|
Breakthrough Material Science and Bioprinting Innovations |
|
Can Bioprinting and Tissue Engineering Create the Next Generation of Medical Implants?
- Bioprinting & Tissue Engineering: Bioprinting enables creation of bone scaffolds and cartilage using bio‑inks, opening new implant categories and reducing reliance on donor tissue. For instance, in November 2025, Tiger Aesthetics invested in GenesisTissue to advance personalized 3D bioprinting. The partnership focuses on developing innovative tissue engineering solutions that combine bioprinting with regenerative medicine. This collaboration aims to expand applications in medical and aesthetic implants, driving progress in customized healthcare and strengthening the future of patient‑specific treatments.
- Smart Implants: Smart implants integrate sensors for real‑time monitoring, improving patient safety, reducing revision surgeries, and enhancing clinical outcomes.
- Hybrid Manufacturing: Hybrid manufacturing combines 3D printing with traditional machining, balancing customization with durability, lowering costs, and improving scalability for medical implants.
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Segmental Insights
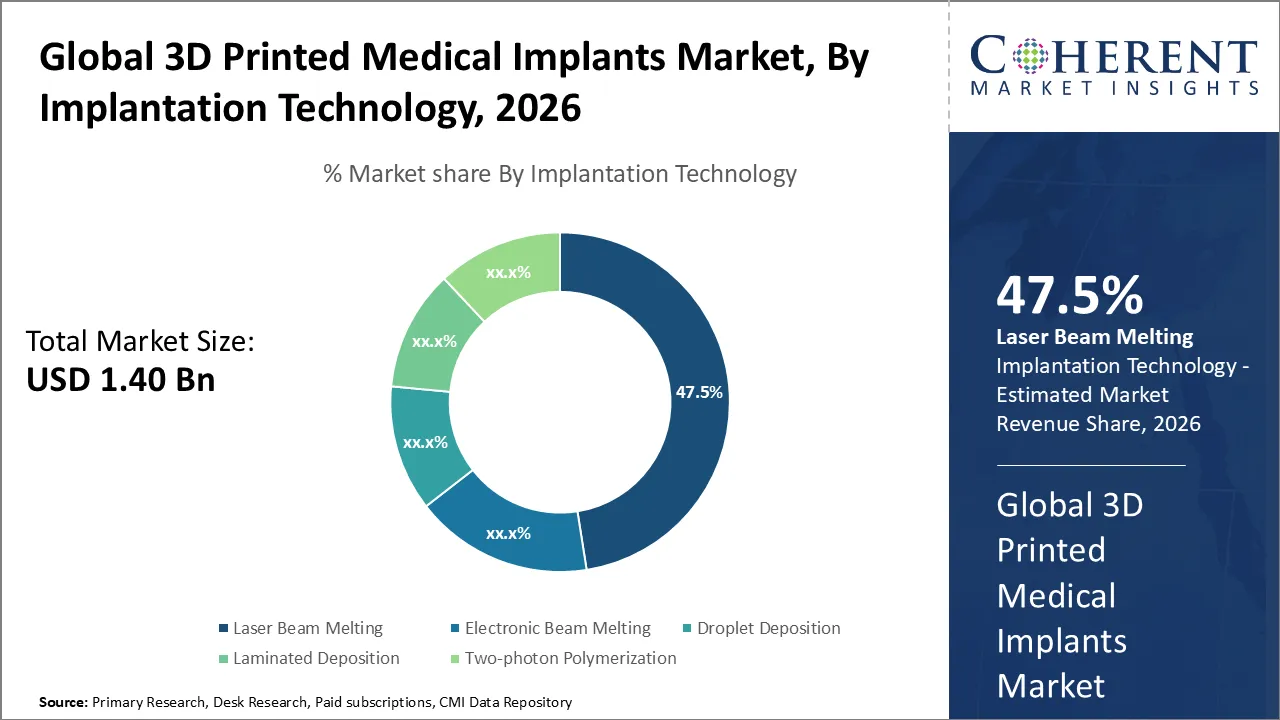
3D Printed Medical Implants Market Insights, By Implantation Technology: Laser Beam Melting Leads Offering Unmatched Precision and Scalability for Complex Medical Implants
In terms of implantation technology, the laser beam melting segment is expected to lead the 47.5% share in 2026, due to its precision and scalability. It enables complex geometries, high accuracy, and cost‑effective production of orthopedic and dental implants. Its widespread adoption across hospitals and research centers solidifies its dominance over other additive manufacturing techniques.
For instance, in December 2025, Imaginarium joined GE Additive’s sales partner network to expand access to metal 3D printing in India. GE Additive’s Direct Metal Laser Melting systems enable precise, patient‑specific medical implants. This partnership accelerates adoption of Laser Beam Melting technology, reinforcing its dominance in orthopedic and dental applications within healthcare.
3D Printed Medical Implants Market Insights, By Component Type: Materials Dominate the Market, With Titanium Alloys and Biocompatible Polymers Driving Implant Production
In terms of component type, the material segment is expected to hold 48% share in 2026, driven by titanium alloys and biocompatible polymers. These materials ensure durability, patient safety, and compatibility with human tissue. Their versatility across orthopedic, dental, and cranio‑maxillofacial applications makes them the backbone of implant production, capturing nearly half the market share.
For instance, in March 2025, Materialise announced that they would be performing a clinical trial for a 3D-printed bioresorbable implant made of polycaprolactone, a biodegradable polymer that dissolves safely in the body over time. This new technology shows the significance materials are in medical implants. It allows for patient-specific solutions and expands the use of implants beyond bone to soft tissue, which strengthens materials' position as the market leader.
3D Printed Medical Implants Market Insights, By Application: Orthopedic Implants Is Fueled by Rising Demand for Hip, Knee, And Spinal Replacements
In terms of application, the orthopedic segment is projected to account for 53% share of the market in 2026. Rising demand for hip, knee, and spinal replacements, fueled by aging populations and trauma cases, drives growth. 3D printing enables patient‑specific solutions, improving surgical outcomes and recovery rates, making orthopedics the most lucrative application segment.
For instance, in October 2025, Israel’s Sheba Medical Center achieved a breakthrough in orthopedics with the nation’s first 3D‑printed bone implant. Surgeons reconstructed a patient’s forearm using a custom PEKK lattice implant, enabling biological integration with grafts or stem cells. This innovation reduces rejection risks, improves fit, and advances personalized regenerative bone surgery.
3D Printed Medical Implants Market Insights, By End User: Medical and surgical centers dominate as hospitals remain primary providers of patient‑specific implants
In terms of end user, the medical and surgical centers segment is projected to capture 50% share in 2026. These institutions directly perform implant surgeries, requiring customized, patient‑specific solutions. Their adoption of advanced 3D printing systems enhances efficiency, reduces surgery times, and improves patient outcomes, ensuring their continued dominance in the industry.
For instance, in December 2025, Amandeep Hospitals in India launched a facility integrating 3D printing and virtual reality for surgical care. The center enables patient‑specific implants, prosthetics, and immersive pre‑surgical planning. This innovation enhances precision, safety, and recovery, positioning the hospital as a pioneer in advanced medical technology and personalized surgical solutions.
Regional Insights
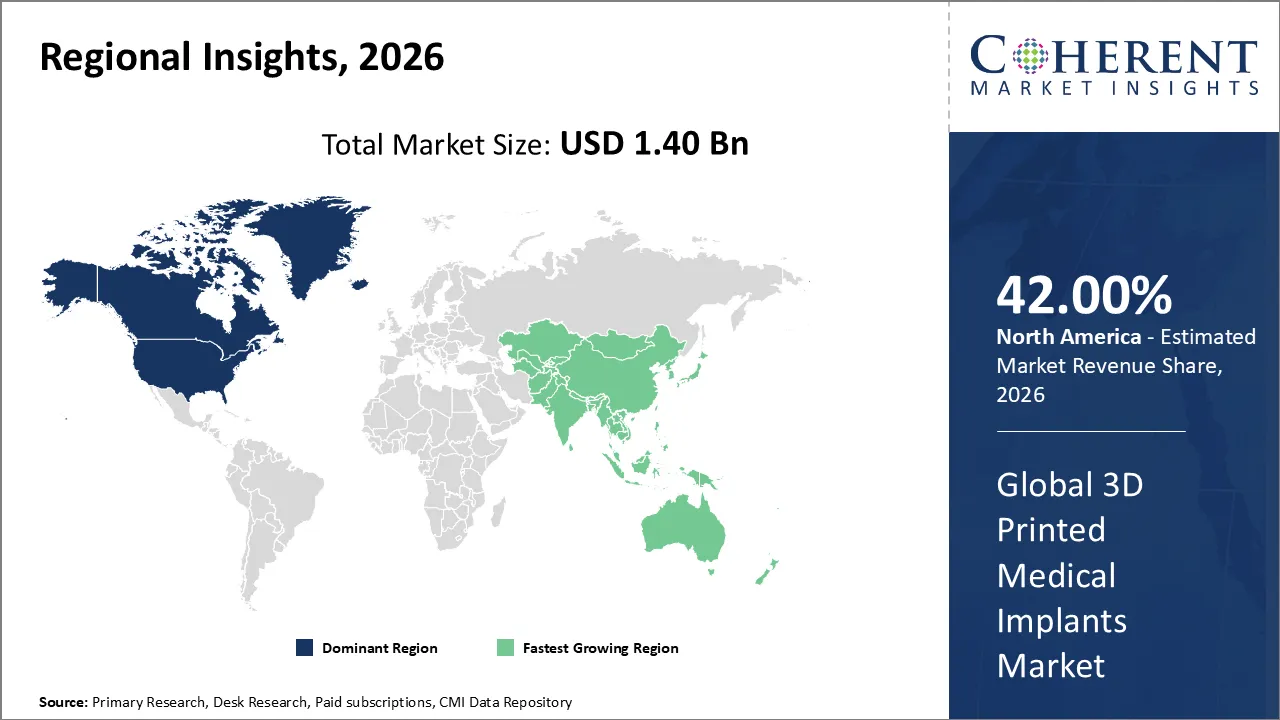
North America 3D Printed Medical Implants Market Analysis & Trends
North America is expected to dominate the 3D printed medical implants market with 42% share in 2026, driven by advanced healthcare infrastructure, high adoption of personalized orthopedic and dental solutions, strong presence of key manufacturers, and supportive regulatory frameworks. Rising chronic conditions and aging populations further fuel market growth, ensuring dominance in innovative surgical technologies.
For instance, in May 2025, Durham‑based restor3d secured $38 million to expand its portfolio of 3D‑printed orthopedic implants. The funding supports commercialization of patient‑specific knee, ankle, hip, and shoulder systems, several already FDA cleared or pending approval. This investment strengthens personalized surgical solutions, advancing innovation in regenerative medicine and orthopedic implant technology.
Asia Pacific 3D Printed Medical Implants Market Analysis & Trends
Asia Pacific is expected to exhibit the fastest growth, fueled by expanding healthcare infrastructure, rising investments in advanced surgical technologies, and a large patient base requiring orthopedic and dental solutions. Rapid urbanization, government support, and growing awareness of personalized medicine make the region the fastest‑growing market globally.
For instance, in December 2025, Medi‑Mold announced a ₹100 crore investment to establish India’s first 3D‑printed orthopedic implant facility. The initiative will enable patient‑specific implants, enhancing surgical precision and recovery outcomes. This milestone positions India as a key player in the Asia‑Pacific market, advancing innovation and accessibility in personalized orthopedic healthcare solutions.
3D Printed Medical Implants Market Outlook Country-Wise
The U.S. 3D Printed Medical Implants Market Trends
In 2026, the U.S. 3D‑printed medical implants market is driven by advanced healthcare infrastructure, strong R&D investment, and widespread adoption of personalized orthopedic and dental solutions. An aging population, rising chronic conditions, and supportive FDA regulatory approvals fuel demand, positioning the U.S. as the dominant global market leader.
For instance, in March 2025, Michigan Medicine launched a clinical trial to test a groundbreaking 3D‑printed airway splint for infants with tracheobronchomalacia, a rare respiratory disease. The bioresorbable implant supports breathing until airways strengthen naturally. This innovation highlights U.S. leadership in pediatric care and advances the role of 3D‑printed medical implants in life‑saving treatments.
China 3D Printed Medical Implants Market Trends
In 2026, China’s 3D‑printed medical implants market is driven by rapid healthcare modernization, rising orthopedic and dental needs, and government support for additive manufacturing. An aging population, increasing chronic conditions, and domestic innovation in personalized implants fuel demand, positioning China as a leading force in Asia‑Pacific’s medical technology growth.
For instance, in March 2025, Researchers at Naton Biotech in China developed the first laser 3D‑printed total knee implant, marking a breakthrough in orthopedic surgery. The innovation enhances implant fit, durability, and patient outcomes, positioning China as a leader in additive manufacturing for medical devices and advancing personalized healthcare in the Asia‑Pacific region.
Market Report Scope
3D Printed Medical Implants Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 1.40 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 19.1% | 2033 Value Projection: | USD 4.77 Bn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | 3D Systems Corporations, Stratasys Ltd, EnvisionTEC, Arcam AB, Organovo Holdings, Inc., EnvisionTEC, Arcam AB, SLM Solutions Group AG, Oxford Performance Materials, Inc., Materialise NV, Bio3D Technologies, and Cyfuse Medical K.K. | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
3D Printed Medical Implants Market Driver
Technological Advancements
Rapid progress in additive manufacturing has transformed the medical field by enabling the creation of complex, patient‑specific implants that traditional methods cannot replicate. The integration of AI and advanced digital design tools ensures greater precision, faster production cycles, and reduced costs. These innovations significantly enhance surgical outcomes and broaden clinical applications. As a result, technological breakthroughs are a major driver of the 3D printed medical implants market share, positioning it as a rapidly expanding segment in global healthcare.
For instance, in November 2025, Lynxter launched new 3D printing technology designed for medtech applications, advancing precision and customization in implant production. The innovation supports faster prototyping and patient‑specific solutions, improving surgical outcomes. This technological advancement strengthens additive manufacturing’s role in healthcare, driving progress in medical implants and expanding opportunities for personalized treatment.
Personalized Healthcare Demand
Patients increasingly seek customized implants tailored to their unique anatomy, whether orthopedic, dental, or cranial. 3D printing allows faster prototyping, individualized solutions, and improved surgical precision, reducing complications and recovery times. This personalization trend aligns with the broader shift toward patient‑centric care. The growing preference for individualized treatments is fueling strong 3D printed medical implants market demand, making customization a critical factor in the adoption and expansion of additive manufacturing in modern medicine.
For instance, in February 2025, Apollo Hospitals partnered with Anatomiz3D Medtech to establish hospital‑based 3D printing labs in India. These labs will enable patient‑specific implants and surgical models, enhance precision and reduce risks in complex procedures.
3D Printed Medical Implants Market Opportunity
Regulatory Support & Approvals
Agencies such as the FDA in the United States and EMA in Europe are increasingly establishing clearer pathways for 3D‑printed medical devices, ensuring safety and efficacy while reducing uncertainty for manufacturers. These streamlined processes accelerate product commercialization, encourage global investment, and foster innovation in personalized healthcare. With faster approvals, companies can bring advanced implants to market more efficiently, strengthening confidence in additive manufacturing. This regulatory evolution is a critical driver shaping the 3D printed medical implants market forecast.
For instance, in July 2025, Holmes Nanochon’s 3D‑printed knee implant has received approval for human clinical trials, marking a key regulatory milestone. This clearance demonstrates growing support for innovative medical devices, accelerating commercialization and investment.
Analyst Opinion (Expert Opinion)
The market for 3D printed medical implants continues to evolve as a major part of advanced healthcare technology, with considerable amounts of use in orthopedic, dental, and craniofacial applications. Orthopedic implants are always the most popular application category, driven by larger number of individuals want personalized joint replacements and trauma-related implants that are made to fit their unique anatomical structures. Dental applications are also gaining an enormous amount of ground, in part to digital dentistry workflows that make design and placement easier and make patients happier.
Material trends indicate that titanium alloys and other biocompatible metals are the best choices for structural implants as they are strong and light and can withstand the stress of the body. People are also paying more attention to polymer and ceramic materials for certain situations where flexibility and biological integration are important. Advanced manufacturing technologies, like laser beam melting, make up a large part of the fabrication process. They allow for accuracy and consistency in complex shapes.
North America is the most important market due to it has a well-established healthcare system and was one of the first places to use additive manufacturing technologies. At the same time, the Asia-Pacific region is becoming a rapidly growing market owing to greater funds being spent on healthcare and more clinical uses. Hospitals and surgical centers are still the main end users, but ambulatory surgical centers and specialty clinics are becoming more interested as implant procedures diversify.
Overall, the market for 3D-printed medical implants is supported by new technologies, the growing usefulness of custom implants in the clinic, and the wider use of additive manufacturing solutions in surgery, which are changing demand and competition patterns around globally.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Recent Developments
- In November 2025, Customed, based in Israel, raised $6 million to expand AI‑powered 3D‑printed solutions for orthopedic surgery. The funding supports development of patient‑specific implants that enhance surgical precision, reduce complications, and improve recovery.
- In August 2025, OIC International, Medi‑Mold, and Fives AddUp partnered to launch a 3D printing hub for orthopedic implants. The collaboration aims to advance patient‑specific solutions, strengthen manufacturing capacity, and expand access to innovative surgical implants. This initiative supports global growth in personalized healthcare and the future of additive medical technologies.
Market Segmentation
- By Component Type
- Material
- Services
- System
- By Implantation Technology
- Laser Beam Melting
- Electronic Beam Melting
- Droplet Deposition
- Laminated Deposition
- Two-photon Polymerization
- By Application
- Dental
- Orthopedic
- Cranio-maxillofacial
- Others
- By End Users
- Medical And Surgical Centers
- Pharmaceutical Companies
- Biotechnology Industry
- Medical Institution
- By Region
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East & Africa
- GCC Countries
- Israel
- Rest of Middle East & Africa
- North America
- 3D Printed Medical Implants Market Companies
- 3D Systems Corporations
- Stratasys Ltd
- EnvisionTEC
- Arcam AB
- Organovo Holdings, Inc.
- SLM Solutions Group AG
- Oxford Performance Materials, Inc.
- Materialise NV
- Bio3D Technologies
- Cyfuse Medical K.K.
Sources
Primary Research Interviews
- 3D Printed Medical Implant Manufacturers
- Orthopedic & Dental Implant Companies
- Medical Device OEMs & Contract Manufacturers
- Additive Manufacturing Material Suppliers (Metals & Polymers)
- Healthcare Technology Consultants & Biomedical Engineers
- Surgeons, Orthopedic Specialists, and Hospital Procurement Heads
- Others
Databases
- Bloomberg Terminal
- Thomson Reuters Eikon
- Others
Magazines
- Medical Device and Diagnostic Industry (MDDI)
- Orthopedic Design & Technology
- Additive Manufacturing Magazine
- Medical Design & Outsourcing
- 3D Printing Industry Magazine
- Others
Journals
- Journal of Biomedical Materials Research
- Additive Manufacturing Journal
- Journal of Orthopaedic Research
- Materials Science & Engineering: C
- International Journal of Advanced Manufacturing Technology
- Others
Newspapers
- Financial Times
- The Wall Street Journal
- Reuters
- Bloomberg News
- Others
Associations
- Additive Manufacturing Users Group (AMUG)
- ASTM International – Additive Manufacturing Committee (F42)
- Medical Device Manufacturers Association (MDMA)
- Orthopaedic Research Society (ORS)
- European Society of Biomaterials (ESB)
- Others
Public Domain Sources
- U.S. Food and Drug Administration (FDA) – Medical Devices
- National Institutes of Health (NIH)
- European Medicines Agency (EMA)
- World Health Organization (WHO)
- National Center for Biotechnology Information (NCBI)
- Others
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of Information for the Last 8 Years
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The 3D printed medical implants market is estimated to be valued at USD 1.40 Bn in 2026, and is expected to reach USD 4.77 Bn by 2033.
The CAGR of the 3D printed medical implants market is projected to be 19.1% from 2026 to 2033.
Technological advancements and personalized healthcare demand are expected to drive the market growth.
The laser beam melting is the leading implantation technology segment in the market.
High manufacturing costs are expected to hinder the global 3D printed medical implants market over the forecast period.
The major players operating in the market include 3D Systems Corporations, Stratasys Ltd, EnvisionTEC, Arcam AB, Organovo Holdings, Inc., EnvisionTEC, Arcam AB, SLM Solutions Group AG, Oxford Performance Materials, Inc., Materialise NV, Bio3D Technologies, and Cyfuse Medical K.K.