

Automated Endoscopy Reprocessor Market Size and Share Analysis - 2026 To 2033
The Automated Endoscopy Reprocessor market is anticipated to grow at a CAGR of 5.10% with USD 767.67 Mn in 2026 and is expected to reach USD 1,087.9 Mn in 2033. The increasing number of gastrointestinal (GI) diseases demanding endoscopic procedures are expected to drive the automated endoscope reprocessor market growth. The U.S. records more than 370,000 new GI cancer cases and nearly 200,000 related deaths each year, including colorectal and pancreatic cancers. Increasing adoption rate of endoscope reprocessors in hospitals for infection prevention and control is expected to fuel the global automated endoscopy reprocessor market revenue. AERs can enhance reliability and consistency of endoscope reprocessing by standardizing several important reprocessing steps, thereby reducing the possibility of human error.
Key Takeaways
- Double Basin segment is expected to account the largest share of 60% in 2026, as it supports high-volume hospital workflows, especially in gastroenterology units handling Mns of procedures annually. By 2050, the global burden of GI cancer is projected to reach 9.06 Mn incident cases (+85%) and 6.42 Mn deaths (+93%) from 2022.
- Standalone will dominate with 65% in 2026, driven by high adoption in hospitals, which account for the majority of endoscopic and surgical reprocessing demand. In Korea, more than 15 Mn gastrointestinal endoscopic procedures were performed in 2023.
- Hospitals will dominate with 64% in 2026, as they perform the highest number of endoscopic procedures. The number of hospitals worldwide is projected to reach 215,977 by 2026.
- North America is expected to acquire the dominant share of 38% in 2026, high gastrointestinal endoscopy volumes in the region dominate the regional market. The estimated numbers of U.S. endoscopic procedures performed in 2019 are as follows: Total endoscopic procedures: 22,162,641.
High-Level Disinfection Technologies is transforming the Automated Endoscopy Reprocessor Industry
High-level disinfection technologies are improving the way hospitals clean and disinfect endoscopes. Advanced chemical disinfection systems use solutions such as peracetic acid, OPA, and glutaraldehyde with automated monitoring to ensure safe and effective cleaning. The Olympus ENDOCAVITY system, used by hospitals like Mayo Clinic, Johns Hopkins Hospital, etc., helped minimize reprocessing time by 40% as well as cut procedure turnaround time from 45 minutes to 25 minutes while discarding 99.9% of pathogens.
Similarly, the STERIS System 1E has been adopted by leading healthcare providers including Cleveland Clinic, Massachusetts General Hospital, etc. This system automated chemical handling, lower staff exposure to disinfectants by 95% and improving workplace safety. Hospitals using the technology also reported zero chemical-related staff incidents after implementation.
Current Events and Their Impact on the Automated Endoscopy Reprocessor Market
Current Event | Description and its Impact |
Stricter FDA Guidelines for Endoscope Reprocessing |
|
Growing Focus on Infection Prevention in Hospitals |
|
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Segmental Insights

Why is Double Basin Segment Acquiring the Largest Market Share?
Double Basin segment is projected to account for the largest share of product type in 2026, representing approximately 60% of the total volume. The superior operational efficiency along with enhanced workflow capabilities in high-volume healthcare facilities is one of the factors responsible for the growth of the segment.
By 2037, the U.S. is projected to face a shortfall of approximately 1,390 gastroenterologists, according to the U.S. Health Resources & Services Administration. As demand for GI care continues to outpace the supply of physicians, health systems are facing escalating challenges in sustaining timely as well as equitable access to care.
Their ability to simultaneously process multiple endoscopes, which significantly reduces turnaround times and increases throughput capacity in busy endoscopy departments is further stimulating the segmental growth.
This simultaneous processing capability is particularly crucial in large hospitals and specialized gastroenterology centers where multiple procedures are conducted daily. The guidelines by the World Health Organization on healthcare facility efficiency target the importance of streamlined reprocessing workflows, which double basin systems inherently provide through their dual-chamber design.
Standalone holds the Largest Market Share
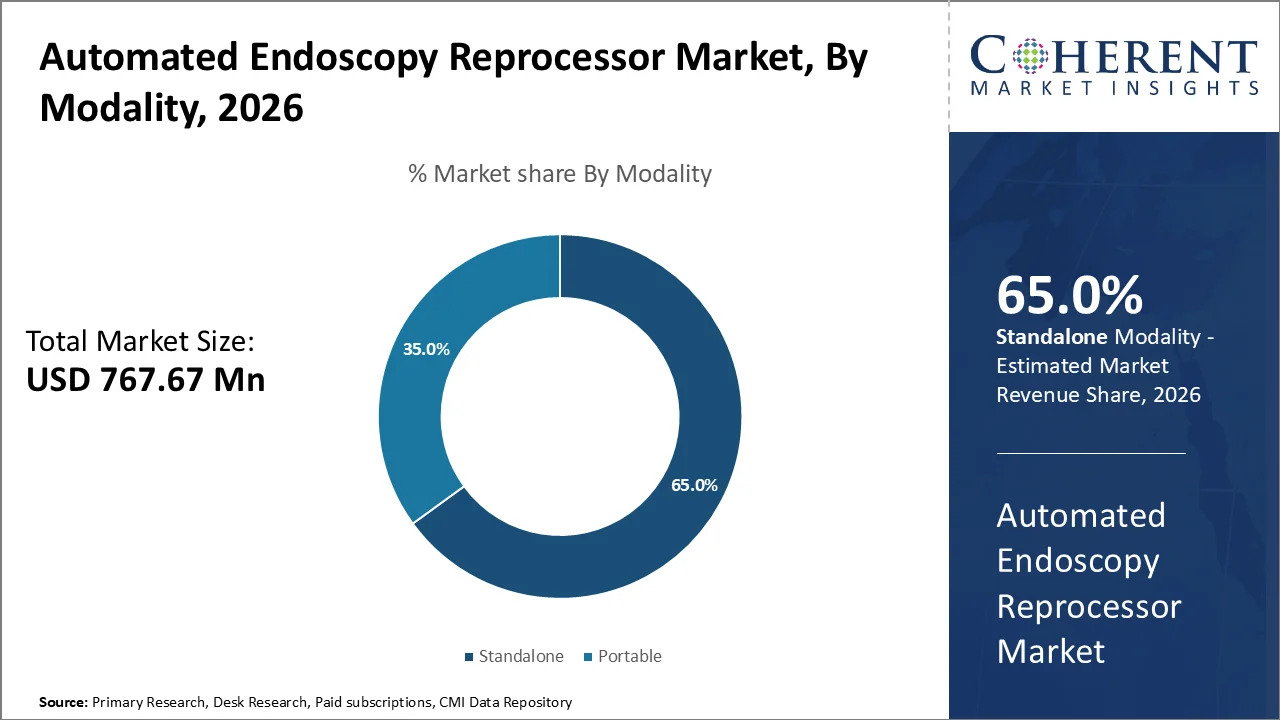
Based on modality, Standalone dominates the market, accounting for a significant 65% share in 2026, their superior processing capabilities, overall cleaning protocols, along with robust infrastructure requirements that align with the operational demands is augmenting growth.
Their ability to accommodate multiple endoscopes concurrently, with most systems capable of processing between 2-12 endoscopes per cycle depending on the model as well as manufacturer specifications is propelling the segmental growth. This high-capacity processing capability becomes crucial in busy medical facilities where endoscopic procedures including colonoscopies, upper endoscopies, bronchoscopies, etc., are performed in rapid succession.
Hospital holds the Largest Market Share
Hospital dominates the market, accounting for a significant 64% share in 2026, the extensive endoscopic procedure volumes, comprehensive infrastructure requirements, as well as strict infection control protocols mandated by healthcare regulatory bodies.
Hospitals represent the backbone of healthcare delivery systems globally, performing the high volume of complex endoscopic procedures including colonoscopies, upper gastrointestinal endoscopies, Bronchoscopy specialized therapeutic interventions, etc. Bronchoscopy was one of the most prevalent in Asia compared to Europe (25% versus 5%).
The guidelines by World Health Organization on decontamination and reprocessing of medical devices emphasize the critical importance of automated reprocessing systems in hospital settings, particularly given the high patient turnover as well as diverse case complexity that characterizes hospital environments.
Automated Endoscopy Reprocessor Market Trends
- The market is experiencing a shift toward smart AER systems with IoT connectivity, real-time monitoring capabilities, and automated documentation features. Number of connected IoT devices growing 14% to 21.1 billion globally in 2025.
- Integration of artificial intelligence for predictive maintenance along with enhanced cleaning protocols is becoming highly prevalent.
- Heightened emphasis on patient safety and infection prevention protocols is driving demand for advanced reprocessing solutions that make sure consistent as well as validated cleaning cycles. Nearly 78.95% hospitals assigned trained personnel to oversee the implementation and feedback of IPC.
- High adoption of eco-friendly reprocessing solutions with lower water consumption, energy-efficient designs, as well as biodegradable cleaning agents shows the commitment of the industry towards environmental stewardship.
Regional Insights
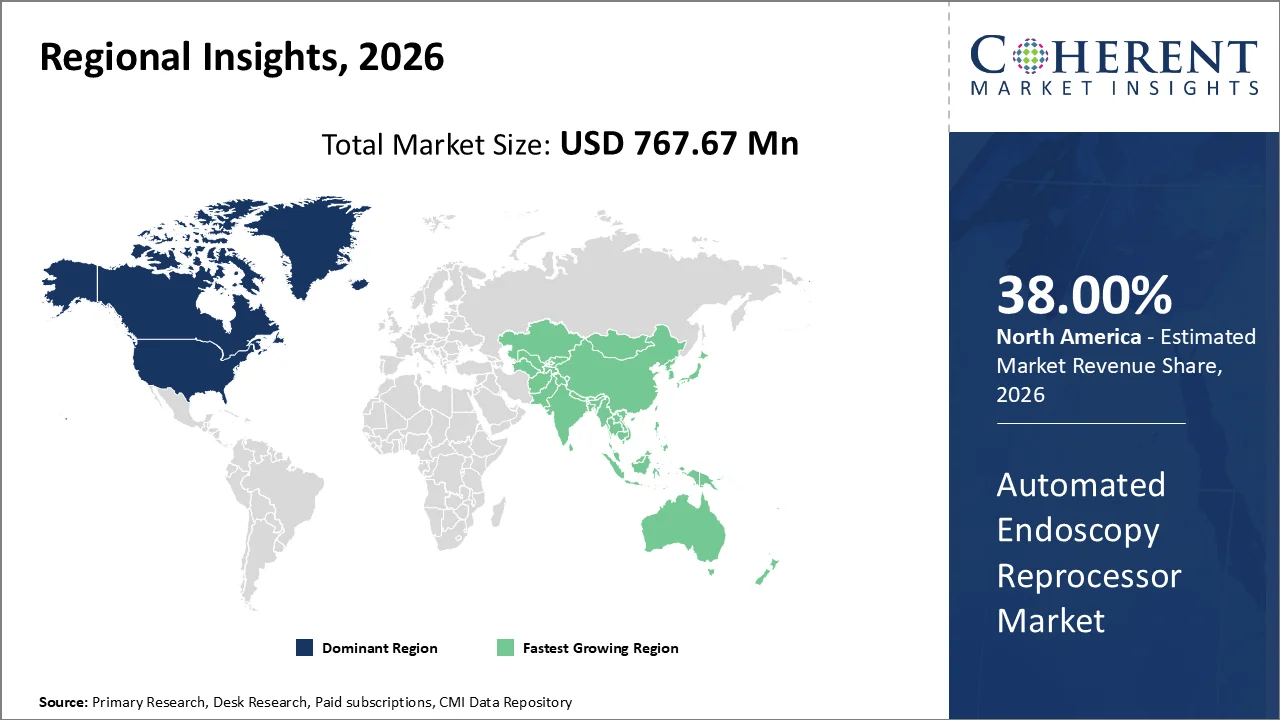
North America dominates owing to the region's well-established healthcare infrastructure
North America account 38% market share in 2026, the region's well-established healthcare infrastructure, stringent regulatory standards, as well as widespread adoption of advanced medical technologies. There was 871 Medical Device Manufacturing in the US businesses as of 2025, an increase of 1.2% from 2024.
The robust healthcare spending patterns, with institutions continuously investing in state-of-the-art medical equipment to ensure patient safety along with operational efficiency is fueling the market. The presence of major medical device manufacturers as well as healthcare technology companies in the United States and Canada has supported an ecosystem where innovation thrives and new technologies are rapidly integrated into clinical practice.
Asia Pacific Automated Endoscopy Reprocessor Market Trends
The Asia Pacific region is poised to be the fastest-growing region through 2026-2033, expanding at a CAGR of approximately 6.2%. The sophisticated healthcare infrastructure and advanced medical technology adoption patterns that have been replicated across Asia-Pacific healthcare facilities. As per 2025 OECD report, as of 2021, Singapore had the most physicians per person among SEA countries (2.6 per 1 000 people).
For example, the Joint Commission International (JCI) accreditation standards, which originated in North America, are now implemented across over 1,000 healthcare facilities in the Asia Pacific region, mandating specific endoscopy reprocessing protocols that favor automated systems.
Its Robust Healthcare Infrastructure is Accelerating the Automated Endoscopy Reprocessor Market Demand in U.S.
The U.S. contributes the highest share in the Automated Endoscopy Reprocessor (AER) market in North America owing to its robust healthcare infrastructure, extensive hospital network, as well as strict regulatory frameworks governing medical device sterilization.
The United States houses over 6,000 hospitals and numerous ambulatory surgical centers, making a high demand for automated endoscopy reprocessing equipment. The Centers for Disease Control and Prevention (CDC) has made a comprehensive guidelines for endoscope reprocessing, mandating high-level disinfection protocols that drive adoption of automated systems.
For example, the CDC's surveillance report documented healthcare-associated infections linked to inadequately processed duodenoscopes, prompting hospitals nationwide to invest in advanced AER systems. Major healthcare systems like Kaiser Permanente, Cleveland Clinic, etc., have implemented standardized AER protocols across their facilities, show growth of the market.
Japan Automated Endoscopy Reprocessor Market Trends
Japan contributes the highest share in the Automated Endoscopy Reprocessor market in APAC owing to its sophisticated healthcare infrastructure, stringent infection control protocols, and advanced medical technology adoption. The emphasis by the Japanese healthcare system on patient safety and quality assurance has driven high implementation of automated endoscopy reprocessing solutions across hospitals as well as ambulatory surgical centers.
The Japan Gastroenterological Endoscopy Society (JGES) has established comprehensive guidelines for endoscope reprocessing that mandate the use of automated systems in major medical facilities, majorly boosting market penetration. For example, leading Japanese hospitals like Tokyo University Hospital and Osaka Medical Center have fully integrated automated endoscopy reprocessors into their gastroenterology departments, with some facilities processing over 200 endoscopic procedures daily using these automated systems.
Who are the Major Companies in Automated Endoscopy Reprocessor Industry
Some of the major key players in Automated Endoscopy Reprocessor market include, Cantel Medical Corp., Johnson & Johnson, Laboratoires Anios, Olympus Corporation, Steelco SpA, Steris Plc., Getinge Group, Hoya Group, and Metall Zug AG
Key News
- In May 2026, SteelcoBelimed expanded its endoscope reprocessing portfolio with the launch of Steri Case, an innovative closed case designed for the washing and liquid chemical sterilization of endoscopes, while maintaining continuous leak test control throughout the entire cycle.
Market Report Scope
Automated Endoscopy Reprocessor Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 767.67 Mn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 5.10% | 2033 Value Projection: | USD 1,087.9 Mn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | Cantel Medical Corp., Johnson & Johnson, Laboratoires Anios, Olympus Corporation, Steelco SpA, Steris Plc., Getinge Group, Hoya Group, and Metall Zug AG | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Analyst Opinion
- The automated endoscopy reprocessor market demonstrates robust momentum driven by escalating demand for infection control protocols and stringent regulatory compliance requirements across healthcare facilities globally.
- The increasing prevalence of gastrointestinal disorders, cancer screening programs, and minimally invasive procedures significantly amplifies the utilization of endoscopic equipment, consequently driving demand for efficient reprocessing solutions. Minimally invasive procedures accounted for 28,243,407 procedures (91.5% of the total volume).
- Healthcare-associated infections remain a critical concern, positioning automated reprocessors as essential investments for hospitals seeking to minimize cross-contamination risks while ensuring consistent disinfection standards. The CDC estimates that 1 in 31 hospital patients in the U.S. has at least one healthcare-associated infection (HAI) on any given day (widely cited public health benchmark).
- Emerging opportunities lie in the development of eco-friendly reprocessing chemicals and energy-efficient systems, aligning with healthcare sustainability initiatives. The growing adoption of single-use endoscopes may pose competitive pressure, yet creates parallel demand for specialized reprocessing verification systems
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- By Product Type (Revenue, USD Mn, 2021-2033)
- Single Basin
- Double Basin
- By Modality (Revenue, USD Mn, 2021-2033)
- Portable
- Standalone
- By End User (Revenue, USD Mn, 2021-2033)
- Hospital
- Diagnostic Laboratories
- Ambulatory Centers
- By Region (Revenue, USD Mn, 2021-2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Rest of Latin America
- Europe
- Germany
- U.K.
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- South Africa
- Central Africa
- North Africa
- North America
Sources
Primary Research Interviews
- Hospital Infection Control Managers
- Endoscopy Department Directors
- Medical Device Procurement Specialists
- Healthcare Technology Integration Consultants
- Others
Databases
- MedDevice Tracker Database
- GlobalData Medical Device Intelligence
- Evaluate MedTech Database
- Healthcare Market Research Database
- Others
Magazines
- Medical Device & Diagnostic Industry (MD+DI)
- Healthcare Purchasing News
- Infection Control Today
- Endoscopy News Digest
- Others
Journals
- American Journal of Infection Control
- Gastrointestinal Endoscopy Journal
- Infection Control & Hospital Epidemiology
- Others
Newspapers
- Healthcare Finance News
- Modern Healthcare
- FierceBiotech
- Medical Device Network News
- Hospital Management Tribune
- Others
Associations
- Association for the Advancement of Medical Instrumentation (AAMI)
- Society of Gastroenterology Nurses and Associates (SGNA)
- International Association of Healthcare Central Service Material Management (IAHCSMM)
- American Society for Gastrointestinal Endoscopy (ASGE)
- Others
Public Domain Sources
- FDA Medical Device Database
- Centers for Disease Control and Prevention (CDC) Guidelines
- World Health Organization (WHO) Medical Device Reports
- ClinicalTrials.gov
- PubMed Central Open Access Database
- Others
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of information for last 10 years
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Automated Endoscopy Reprocessor market is expected to reach USD 1,087.9 Mn in 2033.
Major players operating in the global Automated Endoscopy Reprocessor market include Cantel Medical Corp., Johnson & Johnson, Laboratoires Anios, Olympus Corporation, Steelco SpA, Steris Plc., Getinge Group, Hoya Group, and Metall Zug AG
High initial capital investment and maintenance costs is expected to restrain the automated endoscopy reprocessor market growth over the forecast period.
Increasing number of gastrointestinal (GI) diseases demanding endoscopic procedures is one of the major factors that is expected to propel growth of the market over the forecast period.
The Automated Endoscopy Reprocessor market is anticipated to grow at a CAGR of 5.10% between 2026 and 2033.
Among regions, North America is expected to account for a largest market share in the global Automated Endoscopy Reprocessor market over the forecast period.
An AER can perform standardized disinfection processes and reduce personnel exposure to disinfectants. The use of AER for the HLD involves six procedures: (1) leak testing, (2) cleaning, (3) rinsing, (4) disinfection, (5) final rinsing, and (6) drying.