

Automotive Mudguards Market Size and Share Analysis- 2026 To 2033
The Automotive Mudguards Market size is anticipated to grow at a CAGR of 3.1%, with a market value of USD 1.18 Bn in 2026, and is expected to reach approximately USD 1.45 Bn by 2033. The primary growth drivers are largely defined by the increasing production and sales of passenger and commercial vehicles, rising demand for vehicle protection components, growing replacement requirements in the automotive aftermarket, and increasing adoption of lightweight and durable plastic and composite mudguards. According to the European Automobile Manufacturers’ Association (ACEA), worldwide passenger car registrations increased by 5% to approximately 37.4 million units during the first half of 2025, led by a 12% increase in China and 2.5% growth in North America.
Key Takeaways
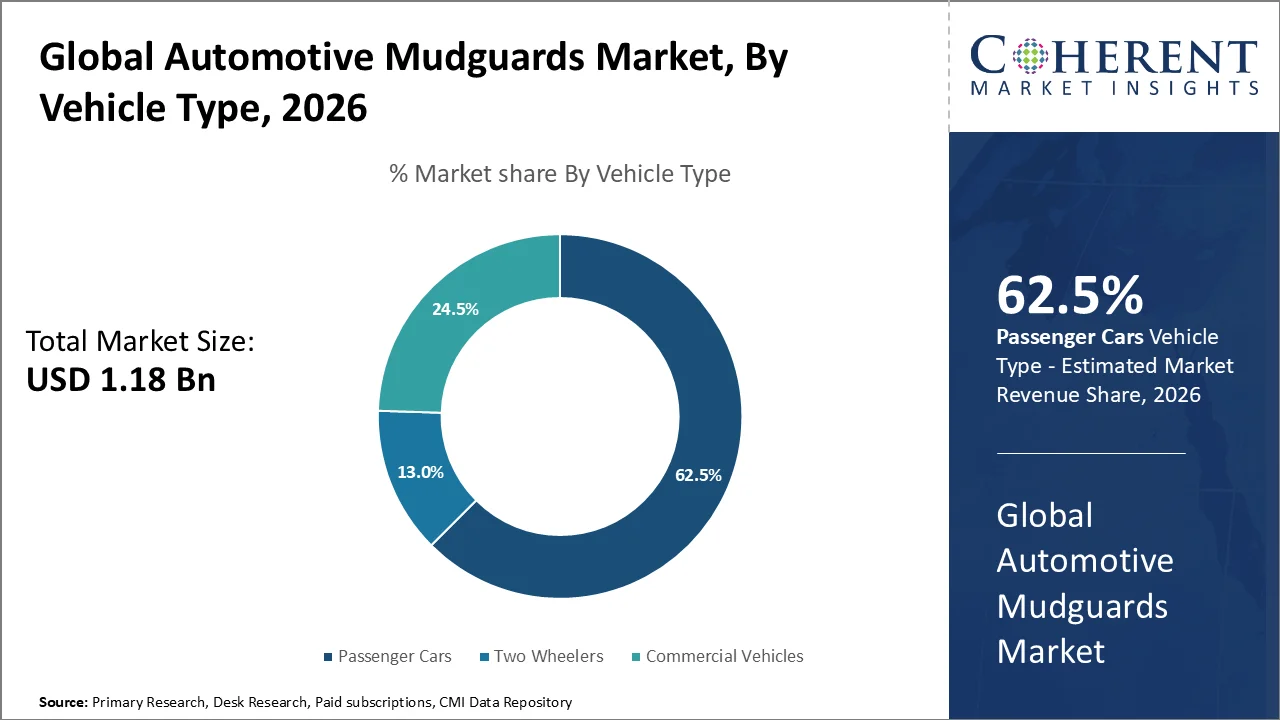
- The passenger cars segment is likely to dominate the market with 62.5% in 2026. The segment’s growth is owing to the substantially larger passenger vehicle installed base, continuous model launches, increasing private vehicle ownership, and recurring demand for replacement mudguards and exterior protection components. According to ACEA’s Vehicles on European Roads 2026 report, approximately 256 million passenger cars were operating on EU roads in 2024, up 1.4% from the previous year.
- The acrylonitrile butadiene styrene (ABS) plastic segment is likely to lead with 36.5% in 2026. The segment’s growth is owing to ABS plastic’s impact resistance, heat resistance, ease of molding, surface finish, and suitability for mass-produced automotive interior and exterior components. SABIC's 2026 polymer portfolio includes a PC/ABS grade containing 30% post-consumer recycled material specifically intended for automotive interior and exterior applications.
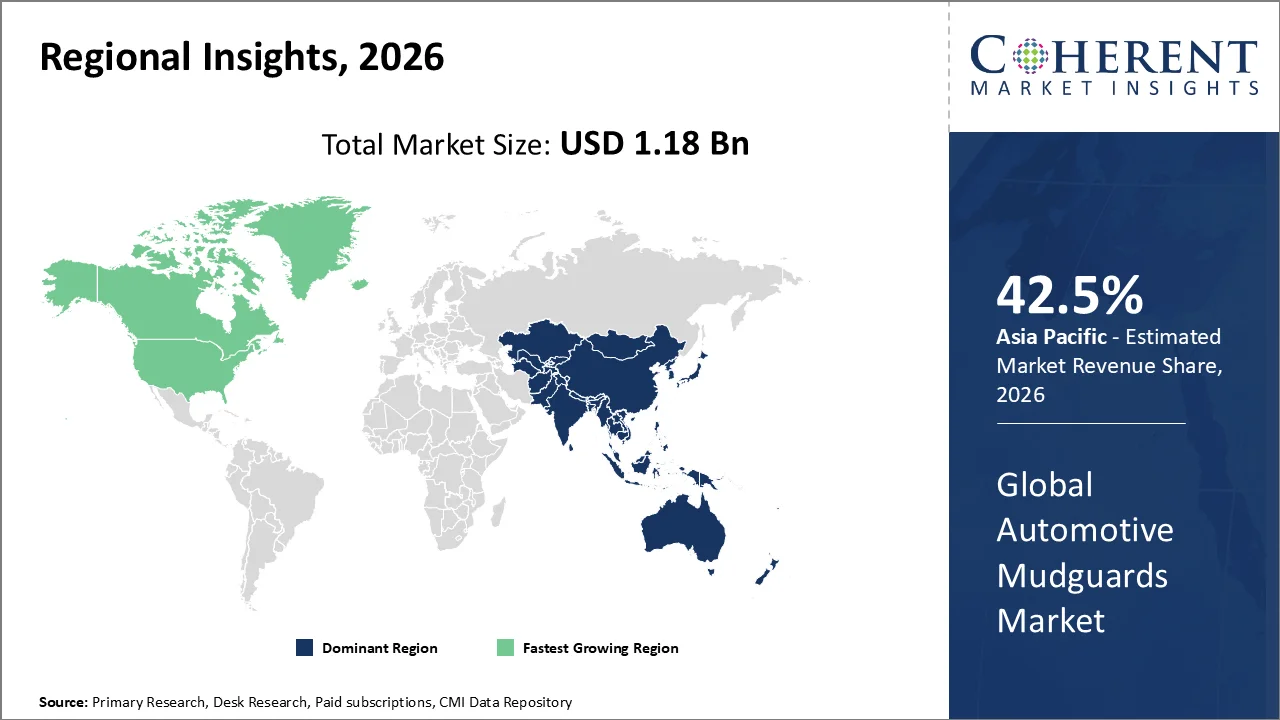
- Asia Pacific will lead the market with 42.5% in 2026. The region's leadership is attributed to its concentrated automotive manufacturing ecosystem, high volumes of passenger and commercial vehicle production, expanding supplier networks, and robust vehicle demand across China, India, Japan and Southeast Asia. India’s passenger vehicle sales in April-June 2026 stood at 1.27 million units, the highest first quarter volume ever, with a year-on-year growth of 25.9%, according to the Society of Indian Automobile Manufacturers (SIAM).
Market Drivers
Rising Vehicle Production and Commercial Vehicle Demand are Expanding the Automotive Mudguards Market
The Automotive Mudguards Market is gaining momentum with the continued growth of global vehicle manufacturing. Higher production volumes directly translate into higher OEM demand for mudguards, splash guards, wheel arch protection and other related exterior parts for both passenger and commercial vehicles.
According to the International Organization of Motor Vehicle Manufacturers (OICA), global motor vehicle production increased 3.9% from 92.7 million units in 2024 to 96.4 million units in 2025. Global vehicle sales also rose 4.7% to 99.8 million units in 2025, indicating continued expansion of the addressable vehicle base for automotive component manufacturers.
In July 2026, ACEA reported that EU truck registrations increased 9.8% year-on-year to 171,933 units during the first half of 2026, while van registrations increased 1.9% to 742,759 units and bus registrations increased 22.7% to 22,590 units. The recovery in commercial vehicle registrations creates additional OEM opportunities for heavy-duty mudguards and related exterior protection systems
Current Events and Their Impact on the Automotive Mudguards Market
Current Event | Description and its Impact |
European Union Introduces New Vehicle Circularity and Recycled-Plastic Requirements (August 2026) |
|
India Strengthens End-of-Life Vehicle EPR and Automotive Material Reporting Requirements (2026) |
|
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Segmental Insights
Why are Passenger Cars Acquiring the Largest Share?
On the basis of vehicle type, the passenger cars segment is projected to account for the largest Automotive Mudguards Market share of 62.5% in 2026. The segment’s growth is owing to the large passenger-vehicle production base, frequent replacement of road-exposed exterior components, increasing vehicle ownership, and continuous OEM demand for mudguards, splash guards, wheel-arch liners, and related protection components.
VDA reported on February 3, 2026, that Germany manufactured a record 1.67 million electric passenger cars in 2025, an increase of 23% from 2024. Demand for newer vehicle platforms requiring light, tough exterior components is increasing as electric vehicles accounted for about 40% of German passenger-car production.
In August 2026, Hyundai Motor announced plans to launch or refresh more than 100 vehicle models globally by 2030 and expand its global manufacturing capacity by approximately 1.27 million units.
Why is Acrylonitrile Butadiene Styrene (ABS) Plastic Acquiring the Largest Share?
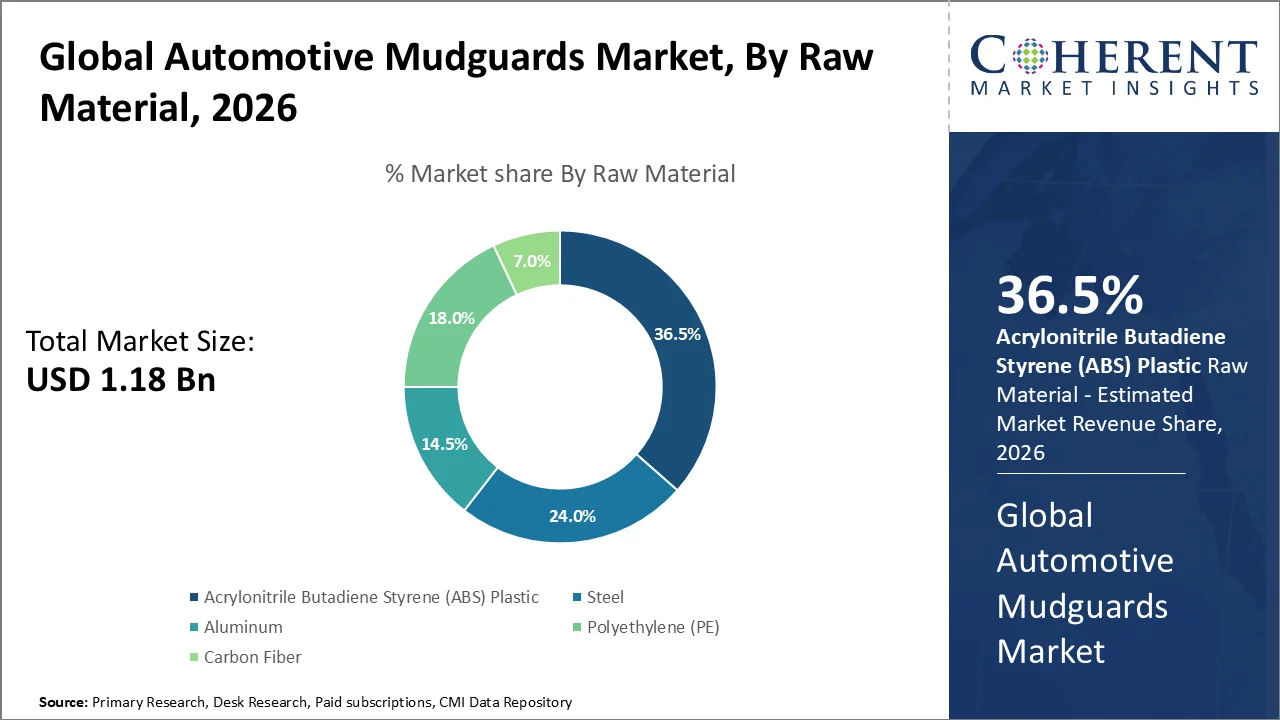
On the basis of raw material, the acrylonitrile butadiene styrene (ABS) plastic segment is projected to account for the largest Automotive Mudguards Market share of 36.5% in 2026. The segment’s growth is owing to ABS plastic’s high impact resistance, dimensional stability, ease of injection molding, paintability, surface quality, and ability to support lightweight automotive exterior-component designs.
Trinseo currently offers MAGNUM ECO+ ABS with up to 60% chemically recycled post-consumer styrene for mobility applications. The company reports that the material can deliver an up to 18% reduction in CO₂ footprint compared with all-prime counterparts while retaining similar processing and performance characteristics. The material is specifically positioned for both visible and hidden automotive applications, strengthening the case for recycled-content ABS in exterior parts.
Automotive Mudguards Market Trends
- Growing use of lightweight and recycled polymeric materials is transforming mudguards and other wheelhouse protection parts. In April 2025, Autoneum presented some 30 fibre-based components, including wheelhouse liners, for the Renault Emblème. The mono-material polyester solutions achieved up to 25% weight reduction and an approximately 70% lower CO₂ footprint per component.
- Increasing attention to acoustic wheelhouse protection is driving the development of multi-functional mudguard and liner designs. Electric vehicles are making tyre and road noise more audible due to quieter powertrains. Autoneum’s current Propylat technology is used for wheelhouse outer liners, which protect against stone chipping and spray water and reduce rolling noise. Some Propylat variants are made from up to 100% recycled fibers, Propylat PET contains up to 70% recycled fibers and is fully recyclable.
- Rising popularity of pickup trucks, SUVs, off-road vehicles, and vehicle customization is driving demand for mud flaps, extended mudguards, splash protection, and wheel-area accessories in the aftermarket. According to the SEMA 2026 Market Report, U.S. consumers spent almost USD 53 billion on specialty-equipment and automotive accessory products in 2025. Pickup-related products accounted for 30% of industry sales, with consumers spending more than USD 15 billion modifying pickups.
Regional Insights
Asia Pacific Dominates Owing to the Large Automotive Manufacturing and Component Supply Base
The Asia Pacific region accounts for 42.5% of the Automotive Mudguards Market share in 2026. The region’s dominance is owing to large-scale vehicle manufacturing, extensive automotive component supply chains, growing passenger and commercial vehicle ownership, and continued expansion of electric and hybrid vehicle production.
According to OICA, China produced about 34.53 million motor vehicles in 2025, adding about 3.25 million units in one year. China was the world's largest automotive manufacturing center and a large OEM demand base for mudguards, splash guards, wheelhouse liners and other exterior protection components
In July 2026, Autoneum announced the construction of two new automotive component production facilities in Wuhu and Anqing, China, following multiple new program awards from Chinese OEMs including Chery.
North America Automotive Mudguards Market Trends
North America is expected to be the fastest-growing region in the Automotive Mudguards Market over the forecast period. The region’s growth is owing to its large light-truck and SUV fleet, increasing vehicle customization, expanding electrified vehicle portfolio, strong replacement-part demand, and highly integrated automotive manufacturing operations across the U.S., Canada, and Mexico.
In June 2026, Statistics Canada reported that 190,167 new motor vehicles were sold in Canada, increasing 7.3% year-on-year. New truck sales increased 8.0%, while passenger-car sales rose 2.9%. Zero-emission vehicle sales increased particularly rapidly, rising 56.1% year-on-year to 21,876 units. The growing vehicle base creates additional OEM and replacement opportunities for mudguards and wheel-area protection components.
In June 2026, OPmobility announced the construction of a new state-of-the-art automotive exterior solutions plant in the greater Toledo area of Ohio, U.S. The facility will be OPmobility’s first dedicated Exterior solutions plant in the U.S. Midwest, with production scheduled to begin in the second half of 2027.
Strong Domestic Manufacturing Investments and New Vehicle Programs are Supporting the Automotive Mudguards Market in the United States
The U.S. Automotive Mudguards Market is expected to witness strong growth over the forecast period. The growth is owing to expanding domestic vehicle manufacturing, increasing localization of automotive component sourcing, and continuous launches of SUVs, pickup trucks, and passenger vehicles. These vehicle categories generate substantial OEM and aftermarket demand for mudguards, splash guards, wheelhouse liners, and other exterior protection components.
In June 2026, General Motors announced that it would spend approximately USD 9 billion across its U.S. manufacturing footprint during 2026, along with more than USD 7 billion on U.S. research and development. GM also announced a USD 275 million investment in its Spring Hill, Tennessee manufacturing complex to support future vehicle and propulsion programs.
China Automotive Mudguards Market Trends
China is expected to remain a major market for automotive mudguards over the forecast period. The growth is owing to its enormous installed vehicle base, high level of new vehicle registrations, localization of global automotive manufacturing, and rapid transition toward new-energy vehicle platforms.
According to data from China's Ministry of Public Security, the country had approximately 371 million automobiles in operation by the end of June 2026. Around 10.51 million automobiles were newly registered during the first half of 2026, including 5.19 million new-energy vehicles. NEVs therefore accounted for 49.42% of all newly registered automobiles, creating a rapidly changing vehicle parc and a substantial addressable base for exterior replacement and OEM components.
In May 2026, BMW stated that the seven-millionth BMW vehicle would roll off its Shenyang production lines during 2026. The company is increasing localization across its Chinese value chain and introducing Neue Klasse technologies into locally developed and manufactured models.
Who are the Major Companies in Automotive Mudguards Industry
Some of the major key players in Automotive Mudguards Market are MrMudguard, Rhino Manufacturing, FeatherWing, KN Rubber, Jonesco, KWIK PFYT Mud Flaps, FIEM Industries, and Sant Manufacturers.
Key News
- In June 2026, FeatherWing announced its participation at Road Transport Expo (RTX) 2026, one of the U.K.'s major commercial road-transport exhibitions, where the company invited fleet and commercial-vehicle customers to explore its latest product innovations.
- In June 2026, FIEM Industries announced that its four-wheeler automotive component business was gaining significant traction and that the company would begin fulfilling key orders for Mahindra & Mahindra during FY2027.
Market Report Scope
Automotive Mudguards Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 1.18 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 3.1% | 2033 Value Projection: | USD 1.45 Bn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | MrMudguard, Rhino Manufacturing, FeatherWing, KN Rubber, Jonesco, KWIK PFYT Mud Flaps, FIEM Industries, and Sant Manufacturers. | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Analyst Opinion
- The Automotive Mudguards Market is expected to maintain steady structural growth as the global vehicle parc expands and vehicles remain in service for longer periods. S&P Global Mobility forecasts the global light-vehicle population to increase from approximately 1.6 billion vehicles in 2025 to 1.9 billion by 2034. Europe’s average light-vehicle age is also expected to exceed 14 years in 2026 and approach 16 years by 2034. This expanding and ageing vehicle base creates recurring replacement demand for road-exposed components such as mudguards, splash shields, and wheel-arch protection systems.
- Material innovation is expected to become an increasingly important competitive differentiator in the mudguards market, particularly as OEMs seek lightweight, recyclable, and lower-carbon exterior components. Röchling Automotive reported that a wheel-housing liner produced entirely from recycled material reduced CO₂e emissions by 73%, from 3.24 kg to 0.88 kg CO₂e per component. Its broader recycled-polypropylene and natural-fiber underbody solutions can reduce CO₂e by up to 40% and manufacturing energy consumption by 80%, demonstrating the performance potential of sustainable materials in components exposed to stones, water, ice, and road debris.
- The market is also gradually shifting from conventional standalone mudguards toward multifunctional wheel-area systems combining protection, aerodynamics, acoustics, and lightweighting. Röchling currently develops hybrid wheel-arch liners using recycled-content PP/EPDM and nonwoven inserts, with designs integrating brake-air ducts, cooling-air outlets, and aerodynamic functions. This indicates that future supplier competitiveness will increasingly depend on integrated engineering capabilities rather than solely on low-cost molded component production.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- By Vehicle Type (Revenue, USD Bn, 2021-2033)
- Two Wheelers
- Passenger Cars
- Commercial Vehicles
- Light Commercial Vehicles (LCVs)
- Heavy Commercial Vehicles (HCVs)
- By Raw Material (Revenue, USD Bn, 2021-2033)
- Steel
- Aluminum
- Acrylonitrile Butadiene Styrene (ABS) Plastic
- Polyethylene (PE)
- Carbon Fiber
- By Region (Revenue, USD Bn, 2021-2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Rest of Latin America
- Europe
- Germany
- U.K.
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- South Africa
- Central Africa
- North Africa
- North America
Sources
Primary Research Interviews
- Automotive mudguard and mud flap manufacturers
- Automotive exterior component manufacturers
- Plastic injection molding and polymer component suppliers
- ABS, polyethylene, aluminum, and steel material suppliers
- Automotive OEM procurement and sourcing managers
- Commercial vehicle body and accessory manufacturers
- Automotive aftermarket distributors and dealers
- Vehicle repair, collision repair, and replacement-part specialists
- Product development and automotive materials engineers
- Fleet operators and commercial vehicle maintenance managers
Databases
- International Organization of Motor Vehicle Manufacturers (OICA)
- European Automobile Manufacturers’ Association (ACEA)
- National Highway Traffic Safety Administration (NHTSA)
- U.S. International Trade Commission (USITC) DataWeb
- UN Comtrade Database
- Eurostat
- U.S. Census Bureau
- Statistics Canad
- China Association of Automobile Manufacturers (CAAM)
- Society of Indian Automobile Manufacturers (SIAM)
Magazines
- Automotive News
- Automotive World
- Automotive Manufacturing Solutions
- Plastics Today
- Modern Plastics
- BodyShop Business
- Collision Repair Magazine
Journals
- International Journal of Automotive Technology
- SAE International Journal of Materials and Manufacturing
- Journal of Materials Processing Technology
- Polymer Testing
- Materials Today
- Journal of Manufacturing Processes
- Transportation Research Procedia
Newspapers
- Reuters
- The Wall Street Journal
- Financial Times
- The Economic Times
- Nikkei Asia
- South China Morning Post
Associations
- International Organization of Motor Vehicle Manufacturers (OICA)
- European Automobile Manufacturers’ Association (ACEA)
- Society of Automotive Engineers (SAE International)
- Society of Indian Automobile Manufacturers (SIAM)
- China Association of Automobile Manufacturers (CAAM)
- Auto Care Association
- Specialty Equipment Market Association (SEMA)
- Motor & Equipment Manufacturers Association (MEMA)
- European Association of Automotive Suppliers (CLEPA)
Public Domain Sources
- Automotive OEM and component manufacturer annual reports
- Company investor presentations and product catalogs
- Automotive production and vehicle registration statistics
- Government vehicle safety and type-approval regulations
- Automotive component import and export databases
- Patent databases such as WIPO, USPTO, and Google Patents
- Vehicle homologation and spray-suppression regulations
- Sustainability and recycled-material disclosures from automotive suppliers
- Company press releases related to new plants, product launches, and OEM contracts
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of Information for the Last 10 Years
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Automotive Mudguards Market is expected to reach approximately USD 1.45 Billion by 2033, up from USD 1.18 Billion in 2026.
Major players operating in the Automotive Mudguards Market include MrMudguard, Rhino Manufacturing, FeatherWing, KN Rubber, Jonesco, KWIK PFYT Mud Flaps, FIEM Industries, and Sant Manufacturers.
Fluctuating raw material prices and high tooling and mold development costs are the key factors hampering growth of the Automotive Mudguards Market.
The increasing global production and sales of passenger and commercial vehicles, along with rising demand for replacement mudguards in the automotive aftermarket, are key factors driving market growth.
The Automotive Mudguards Market is anticipated to grow at a CAGR of 3.1% between 2026 and 2033.
Among regions, Asia Pacific is expected to dominate the Automotive Mudguards Market, accounting for 42.5% of the market share in 2026. The region benefits from large-scale vehicle manufacturing, extensive automotive component supply chains, and expanding passenger and commercial vehicle ownership.
North America is expected to be the fastest-growing region over the forecast period, supported by its large light-truck and SUV fleet, growing vehicle customization, expanding electrified vehicle portfolio, strong replacement-part demand, and integrated automotive manufacturing operations.