
Myelodysplastic Syndrome Treatment Market Size and Trends - 2026 to 2033
The Myelodysplastic Syndrome Treatment Market is estimated to be valued at USD 2.99 Bn in 2026 and is expected to reach USD 4.63 Bn by 2033, growing at a compound annual growth rate (CAGR) of 6.4% from 2026 to 2033.
Key Takeaways
- Based on Drug, the Azacitidine segment is expected to lead the market with 36.20% share in 2026, due to its wide clinical adoption.
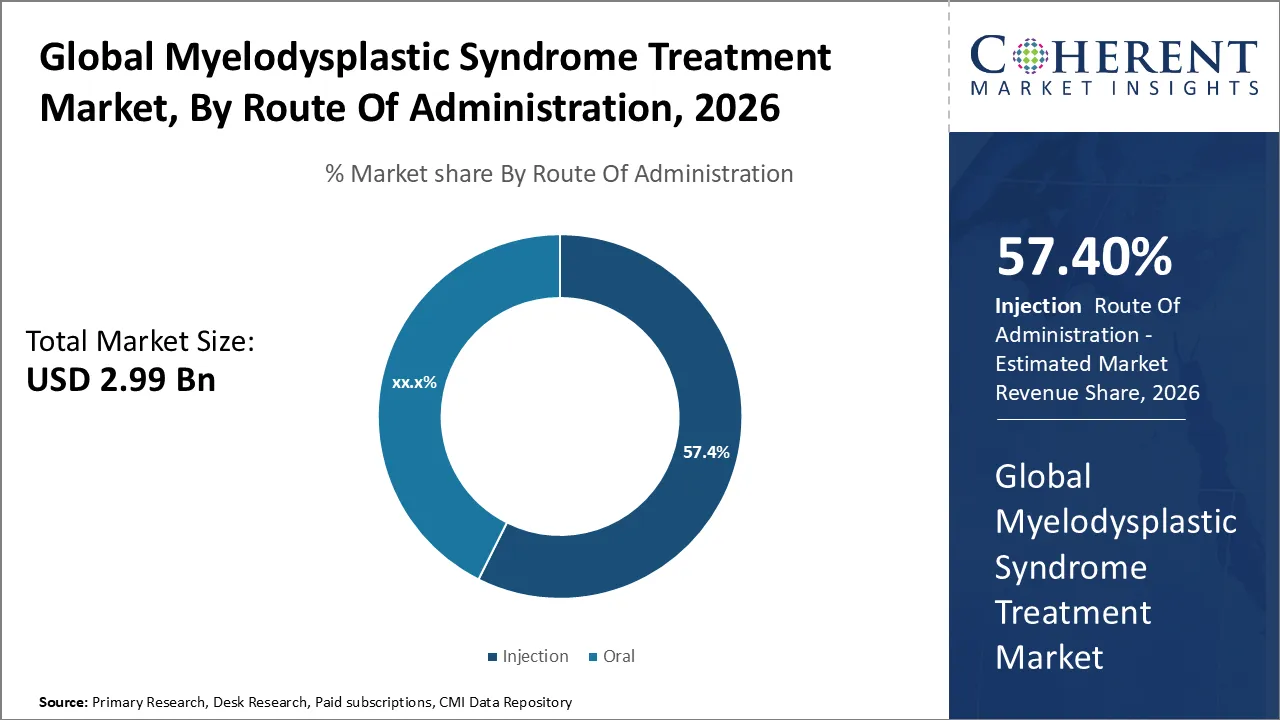
- Based on Route of Administration, the Injection segment is expected to lead the market with 57.40% share in 2026, due to established HMA therapies.
- Based on Distribution Channel, the Hospital Pharmacies segment is expected to lead the market with 47.70% share in 2026, due to complex oncology treatments.
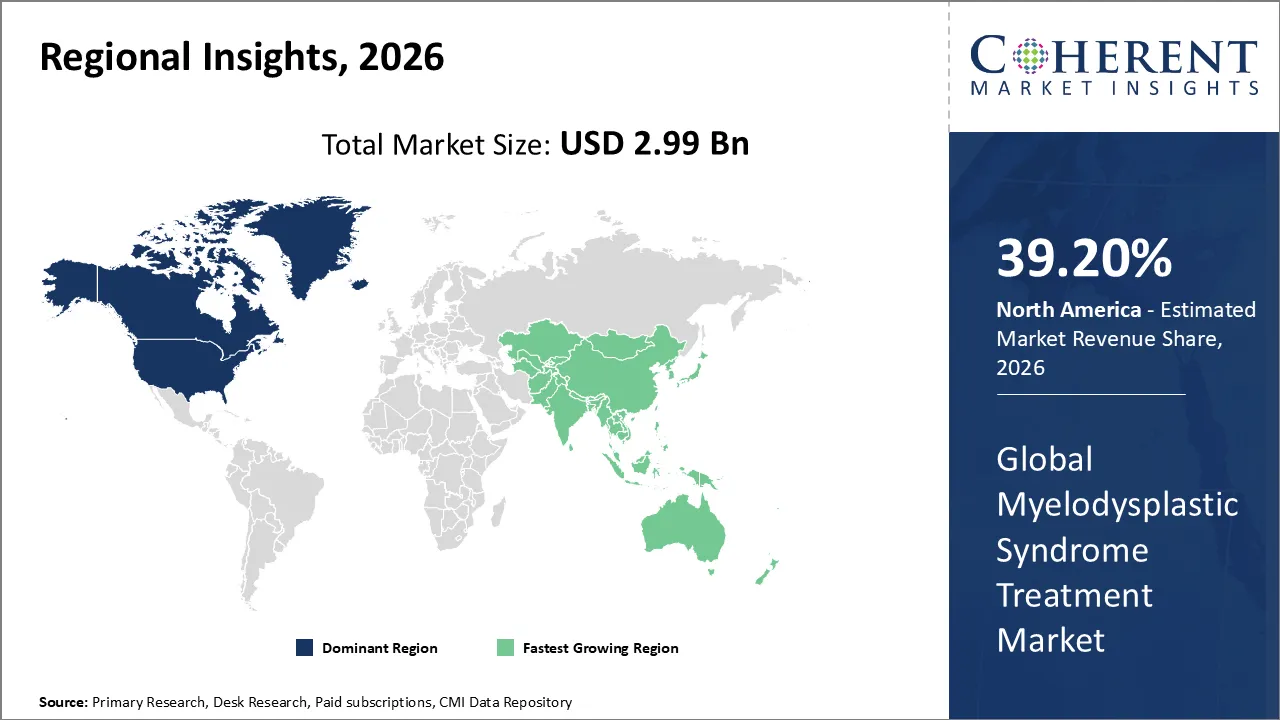
- Based on Region, North America is set to lead the market with 39.20% share in 2026. While, Asia Pacific is anticipated to be the fastest growing region.
Market Overview
The myelodysplastic syndrome treatment market is advancing significantly, driven by the rising demand for targeted therapies and precision medicine in the hematology and oncology sectors. The increasing prevalence of Myelodysplastic Syndromes (MDS), mainly among the growing geriatric population, is contributing to the increased demand for effective therapies. A strategic shift toward molecularly guided interventions like treatments targeting SF3B1 and TP53 mutations is expected to propel market growth over the forecast period.
The cutting-edge therapeutic agents like next-generation hypomethylating agents and telomerase inhibitors are derived from deep insights into bone marrow pathology and clonal evolution. This makes advanced drug therapy a vital component in modern health protocols, thus focusing on reducing transfusion dependency and improving overall survival rates for both lower-risk and high-risk patients.
Current Events and Its Impacts on the Myelodysplastic Syndrome Treatment Market
Current Event | Description and the Impact |
Regulatory Approvals and Policy Changes
|
|
Technological and Research Advancements |
|
Epidemiological Trends and Demographic Shifts
|
|
Segmental Insights
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Myelodysplastic Syndrome Treatment Market Insights, By Route of Administration – Injection Leads Due to Higher Bioavailability and Precise Dosing
In terms of route of administration, the injection segment contributes the highest share of 57.40% in 2026 of the market. The core therapeutic agents for MDS are formulated for intravenous or subcutaneous delivery. The injectable administration ensures higher bioavailability and precise dosing, which is critical for managing the complex hematological profiles of MDS patients. In addition, multiple treatments are administered in clinical settings where healthcare professionals can monitor for immediate adverse reactions. The reliance on injectable erythropoiesis-stimulating agents and traditional chemotherapy keeps this agent at the forefront. The need for rapid systemic absorption during acute phases of the disease also cements the injectable route as the most reliable and widely utilized method for delivering life-saving MDS medications.
For instance, in September 2024, Camber Pharmaceuticals has announced the recent release of Decitabine for Injection to its product range. This medication is classified as a nucleoside metabolic inhibitor and is specifically authorized for use in the treatment of adult patients with the diagnosis of myelodysplastic syndromes (MDS).
Myelodysplastic Syndrome Treatment Market Insights, By Drug – Azacitidine Leads Due to its Wide Clinical Adoption
In terms of drug, the azacitidine segment contributes the highest share of 36.20% in 2026 of the market. The growth is because it remains the gold standard hypomethylating agent for patients. Azacitidine is one of the few interventions clinically proven to extend overall survival and delay progression to acute myeloid leukemia. Its growth is attributable to its inclusion in global clinical guidelines and its increasing use in combination with newer targeted therapies. The established efficacy and safety profile of Azacitidine make it the foundational treatment, although the market sees frequent entries of novel molecules. The increasing prevalence of MDS among the aging population results in increased demand for Azacitidine in both developed and emerging healthcare markets.
For instance, in November 2025, SELLAS Life Sciences Group, Inc. showcased Phase 2 data on SLS009 for relapsed or refractory acute myeloid leukemia (r/r AML) at the 67th American Society of Hematology (ASH) Annual Meeting and Exposition. The Phase 2 trial is testing SLS009, a highly selective CDK9 inhibitor, in combination with azacitidine (AZA) and venetoclax (VEN) for r/r AML with myelodysplastic syndrome-related changes (AML-MR) after VEN-based treatment.
Myelodysplastic Syndrome Treatment Market Insights By, Distribution Channel – Hospital Pharmacies Leads Due to Specialized Nature of MDS Care
In terms of distribution channel, the hospital pharmacies contributes the highest share of 47.70% in 2026 of the market. This growth is owing to the specialized nature of MDS care. The MDS treatment involves intensive chemotherapy and biologics that require professional handling, specialized storage, and sterile preparation. Since MDS patients frequently require integrated services such as blood transfusions, bone marrow biopsies, and close monitoring by hematologists, the majority of drug dispensing occurs within the hospital infrastructure. These pharmacies are equipped for managing the high expenses and complex reimbursement processes associated with oncology drugs. The centralized delivery of cancer care positions hospital pharmacies as the primary point of access for patients. They provide a seamless link between diagnosis, specialized treatment, and essential supportive care services.
Regional Insights
North America Myelodysplastic Syndrome Treatment Market Analysis & Trends
North America has remained the dominant region with 39.20% in 2026 of the global myelodysplastic syndrome treatment market over the past decade. The growth is owing to the aging demographic in the US, where the high incidence of MDS is met with a sophisticated healthcare infrastructure and early access to breakthrough therapies. The North American landscape is characterized by a rapid transition toward precision oncology. This is driven by the increasing clinical use of genomic profiling to identify specific mutations like SF3B1 or TP53. The market has seen a substantial shift toward oral formulations like the FDA-approved Inqovi, which enhances patient quality of life by reducing the need for clinical infusions.
In addition, the region also benefits from the highest concentration of clinical trials globally. The top firms like Bristol Myers Squibb and AbbVie are pursuing targeted therapies like BCL-2 and IDH inhibitors. The Medicare and private insurance offer robust reimbursement plans, thus encouraging more individuals to explore these new drugs. The advancements in allogeneic stem cell transplant techniques for older patients position North America as a leader in treating myelodysplastic syndromes (MDS).
For instance, in January 2025, Medexus has obtained FDA approval for GRAFAPEX™, an alkylating agent that is used alongside fludarabine as a preparative regimen for allogeneic hematopoietic stem cell transplantation (alloHSCT). This treatment is intended for adult and pediatric patients aged one year and older who are diagnosed with acute myeloid leukemia (AML) or myelodysplastic syndrome (MDS).
Asia Pacific Myelodysplastic Syndrome Treatment Market Analysis & Trends
The Asia Pacific region is the fastest growing market for myelodysplastic syndrome treatment. The growth can be attributed to the increasing aging population, especially in Japan, China, and South Korea. It significantly raises the incidence rate of bone marrow disorders. Currently, China holds the largest market share in the region. Japan is experiencing a strong growth rate attributable to its cutting-edge healthcare infrastructure and early adoption of innovative therapies. The market is witnessing a decisive transition from basic supportive care like blood transfusions and erythropoiesis-stimulating agents, toward sophisticated disease-modifying treatments.
The landscape is also being transformed by the increasing availability of allogeneic stem cell transplantation in emerging economies like India and Vietnam. The top pharmaceutical businesses like Takeda, Otsuka, and Bristol Myers Squibb are collaborating with local biotech firms to navigate complex regulatory hurdles and improve drug accessibility. The integration of molecular diagnostics and genomic profiling is streamlining patient stratification. This ensures that the region remains a key hub for clinical research and commercial growth in the oncology sector.
In August 2025, Ascentage Pharma has secured permission from the European Medicines Agency (EMA) and the U.S. Food and Drug Administration (FDA) to conduct the GLORA-4 study (NCT06641414). This study is a global registrational Phase III trial of lisaftoclax (APG-2575), a proprietary Bcl-2 inhibitor, in combination with azacitidine (AZA). The trial aims to treat patients who have recently been diagnosed with higher-risk myelodysplastic syndrome (HR-MDS).
Myelodysplastic Syndrome Treatment Market Outlook Country-Wise
The US Myelodysplastic Syndrome Treatment Market Trends
The US is leading the myelodysplastic syndrome treatment market. The growth is owing to the rapid expansion of the biopharmaceutical industry, where efficient cell disruption is critical for the production of monoclonal antibodies, vaccines, and recombinant proteins. The rising prevalence of chronic diseases has also speeded up the research in genomic and proteomic analysis, placing a premium on high-purity intracellular extractions. Technologically, the market is transitioning toward reagent-based lysis and automated high-throughput systems, which provide greater consistency and reduced sample degradation compared to traditional mechanical methods. The top companies in the industry like Thermo Fisher Scientific and Danaher Corporation are placing a greater emphasis on innovation to cater to the rising demand for precision medicine and personalized healthcare.
China Myelodysplastic Syndrome Treatment Market Trends
China is rapidly emerging as the fastest-growing market for treatments of myelodysplastic syndrome. The growth is owing to an aging population and substantial regulatory reforms by the National Medical Products Administration (NMPA). The market is focusing on targeted therapies and innovative combinations. The recent approval of Luspatercept by the NMPA represents a major advancement in the treatment of transfusion-dependent anemia. Hypomethylating Agents (HMAs) like Azacitidine are still the standard way to treat high-risk patients. China is also uniquely combining Traditional Chinese Medicine (TCM) with Western treatment protocols to make chemotherapy less harmful and improve the function of the bone marrow. The Chinese landscape is shifting toward a more personalized and multidisciplinary approach. A strong pipeline of domestic clinical trials is focusing on PD-1 and BCL-2 inhibitors.
Market Report Scope
Myelodysplastic Syndrome Treatment Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 2.99 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 6.4% | 2033 Value Projection: | USD 4.63 Bn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | Celgene Corporation, Otsuka Pharmaceutical Co., Ltd. Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Limited, Dr. Reddy's Laboratories Ltd., Mylan NV, Cipla Limited, Acceleron Pharma, Inc., Aprea Therapeutics, FibroGen Inc., Onconova Therapeutics Inc., and Geron. | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Myelodysplastic Syndrome Treatment Market Drivers
Rising aging population
The global Myelodysplastic Syndrome (MDS) treatment market is closely tied to the demographic shift toward an aging population, as the incidence of this disease rises with age. The average age at diagnosis is about 71 years. The World Health Organization (WHO) projects that the number of people aged 60 and older will double by 2050, which means that the number of people with MDS is growing at an unprecedented rate. This biological reality creates a sustained demand for long-term therapeutic interventions as aged bone marrow becomes susceptible to the genetic mutations and hematopoietic failures that define the syndrome.
The effects of this aging trend are particularly evident in the swift embrace of lower-intensity therapies and oral medications. The older patients with comorbidities tolerate traditional aggressive treatments like intensive chemotherapy poorly. This is driving the market toward gentler alternatives like Hypomethylating Agents (HMAs) and erythropoiesis-stimulating agents. Innovations like Inqovi, an oral HMA, have specifically targeted this demographic by eliminating the physical burden of frequent hospital visits for infusions. In addition, the rising prevalence of transfusion-dependent anemia in the elderly has solidified the commercial success of drugs like Luspatercept, which addresses the chronic fatigue and reduced quality of life associated with the disease.
The primary driver of demand for MDS therapies is strongest in Japan and Western Europe. This is mainly due to aging populations, which have resulted in substantial government support for these treatments. The emerging nations like China and India are experiencing increased demand owing to rising life expectancy and advancements in diagnostic capabilities. The MDS market is expected to witness growth fueled by the dual forces of demographic necessity and the pursuit of quality-of-life-focused medicine.
Analyst Opinion (Expert Opinion)
The Myelodysplastic Syndrome Treatment Market is witnessing steady growth driven by demographic and clinical factors. Globally, the incidence of MDS is highest among older populations, with the United States reporting approximately 4–5 new cases per 100,000 people annually, translating to an estimated 10,000–15,000 new diagnoses each year. This rising prevalence is reflected in increasing adoption of advanced therapeutic options.
Treatment utilization is predominantly concentrated in hypomethylating agents, such as azacitidine and decitabine, due to their established efficacy in higher-risk MDS. Targeted therapies are gaining traction, supported by molecular diagnostic stratification, while supportive care and transfusion therapies continue to account for a significant proportion of real-world interventions. Red blood cell transfusions remain among the most commonly administered treatments across regions.
Regional dynamics reveal that North America leads in treatment uptake, driven by advanced diagnostic infrastructure and comprehensive coverage models. Europe follows, with broad reimbursement frameworks and guideline-driven care, while Asia Pacific shows rapid adoption growth due to increasing healthcare investment and expanding specialist networks.
Clinical outcomes, including a 5-year survival rate of around 37% post-diagnosis, emphasize the need for therapies that improve quality of life, prolong transfusion independence, and reduce complications. Market expansion is balanced against high therapy costs and limited access to molecular diagnostics in emerging regions.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Myelodysplastic Syndrome Treatment Industry News
- In November 2025, Orca Bio announced that the U.S. Food and Drug Administration (FDA) has received approval for Priority Review their Biologics License Application (BLA) for Orca-T. This is the company's lead investigational allogeneic T-cell immunotherapy aimed at treating hematological malignancies such as myelodysplastic syndromes (MDS).
- In Mar 2025, Geron has announced that the European Commission has granted approval for RYTELO® (imetelstat), a first-in-class telomerase inhibitor. This treatment is intended for adults who suffer from transfusion-dependent anemia caused by lower-risk MDS.
- In October 2024, the National Institutes of Health (NIH) has begun a proof-of-concept clinical study in precision medicine. This trial intends to examine potential treatment combinations that particularly target gene mutations in the cancer cells in people with acute myeloid leukemia (AML) and myelodysplastic syndromes (MDS).
- In October 2023, Servier has received approval from the U.S. Food and Drug Administration (FDA) for TIBSOVO® (ivosidenib tablets). This treatment is specifically intended for patients with relapsed or refractory (R/R) myelodysplastic syndromes (MDS) who have mutations in isocitrate dehydrogenase 1 (IDH1).
Market Segmentation
- Drug Insights (Revenue, USD Bn, 2026 - 2033)
- Lenalidomide
- Decitabine
- Azacitidine
- Phase 3 Drugs
- Route of Administration Insights (Revenue, USD Bn, 2026 - 2033)
- Injection
- Oral
- Distribution Channel Insights (Revenue, USD Bn, 2026 - 2033)
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Regional Insights (Revenue, USD Bn, 2026 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- North Africa
- Central Africa
- South Africa
- Key Players Insights
- Celgene Corporation
- Otsuka Pharmaceutical Co., Ltd.
- Teva Pharmaceutical Industries Ltd.
- Sun Pharmaceutical Industries Limited
- Dr. Reddy's Laboratories Ltd.
- Mylan NV
- Cipla Limited
- Acceleron Pharma, Inc.
- Aprea Therapeutics
- FibroGen Inc.
- Onconova Therapeutics Inc.
- Geron
Sources
Primary Research Interviews
- Hematology & Oncology Specialists
- Clinical Research Organizations (CROs)
- Biopharmaceutical Companies Developing MDS Treatments
- Hospital & Cancer Center Pharmacologists
- Health Technology Assessment (HTA) Experts
- Patient Advocacy Group Representatives
- Others
Databases
- Bloomberg Terminal
- Thomson Reuters Eikon
- IHS Markit
- Others
Magazines
- Hematology News
- Oncology Times
- Pharmaceutical Executive
- Cancer Therapy Advisor
- Others
Journals
- Blood
- Leukemia
- Journal of Clinical Oncology
- Haematologica
- British Journal of Haematology
- Others
Newspapers
- Financial Times
- The Wall Street Journal
- Reuters
- Bloomberg News
- Others
Associations
- American Society of Hematology (ASH)
- European Hematology Association (EHA)
- International Myelodysplastic Syndromes Foundation (IMDSF)
- National Cancer Institute (NCI)
- Others
Public Domain Sources
- U.S. Food & Drug Administration (FDA)
- European Medicines Agency (EMA)
- World Health Organization (WHO)
- National Institutes of Health (NIH)
- ClinicalTrials.gov
- Others
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of Information for the Last 8 Years
Definition: The myelodysplastic syndrome treatment market is a specialized segment of the global oncology and hematology industry focused on the management of a group of rare bone marrow cancers where the body fails to produce mature, healthy blood cells. The increasing burden of MDS in aging populations is a key contributor to market growth worldwide. It includes a wide array of therapeutic interventions like hypomethylating agents, immunomodulators, and targeted therapies designed to address specific genetic mutations. The marrow includes essential supportive care like blood transfusions and growth factors, alongside curative allogeneic stem cell transplantations. Currently, the sector is being transformed by precision medicine, which utilizes molecular profiling to provide more personalized and effective treatment for patients.
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Myelodysplastic Syndrome Treatment Market is estimated to be valued at USD 2.99 Bn in 2026, and is expected to reach USD 4.63 Bn by 2033.
The CAGR of the Myelodysplastic Syndrome Treatment Market is projected to be 6.4% from 2026 to 2033.
Factors such as government organizations and drug manufacturing companies focusing on spreading awareness about the myelodysplastic syndrome (MDS) disease and increasing regulatory approval of drugs for treating Myelodysplastic Syndrome (MDS) are the major factors driving the growth of the Myelodysplastic Syndrome Treatment Market.
The high cost of treatment for Myelodysplastic Syndrome (MDS) are the major factors hampering the growth of the Myelodysplastic Syndrome Treatment Market.
In terms of drug, the azacitidine segment is estimated to dominate the market revenue share in 2026.
Celgene Corporation, Otsuka Pharmaceutical Co., Ltd. Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Limited, Dr. Reddy's Laboratories Ltd., Mylan NV, Cipla Limited, Acceleron Pharma, Inc., Aprea Therapeutics, FibroGen Inc., Onconova Therapeutics Inc., and Geron are the major players.
North America is expected to lead the Myelodysplastic Syndrome Treatment Market in 2026.