
Optical Transceiver Market Size and Forecast – 2026 to 2033
Optical Transceiver Market is estimated to be valued at USD 15.96 Bn in 2026 and is expected to reach USD 36.18 Bn in 2033, exhibiting a compound annual growth rate (CAGR) of 12.4% from 2026 to 2033.
Key Takeaways
- By Protocol, Fiber Channel hold the largest market share of 33.3.% in 2026 owing to its hyperscale data center growth.
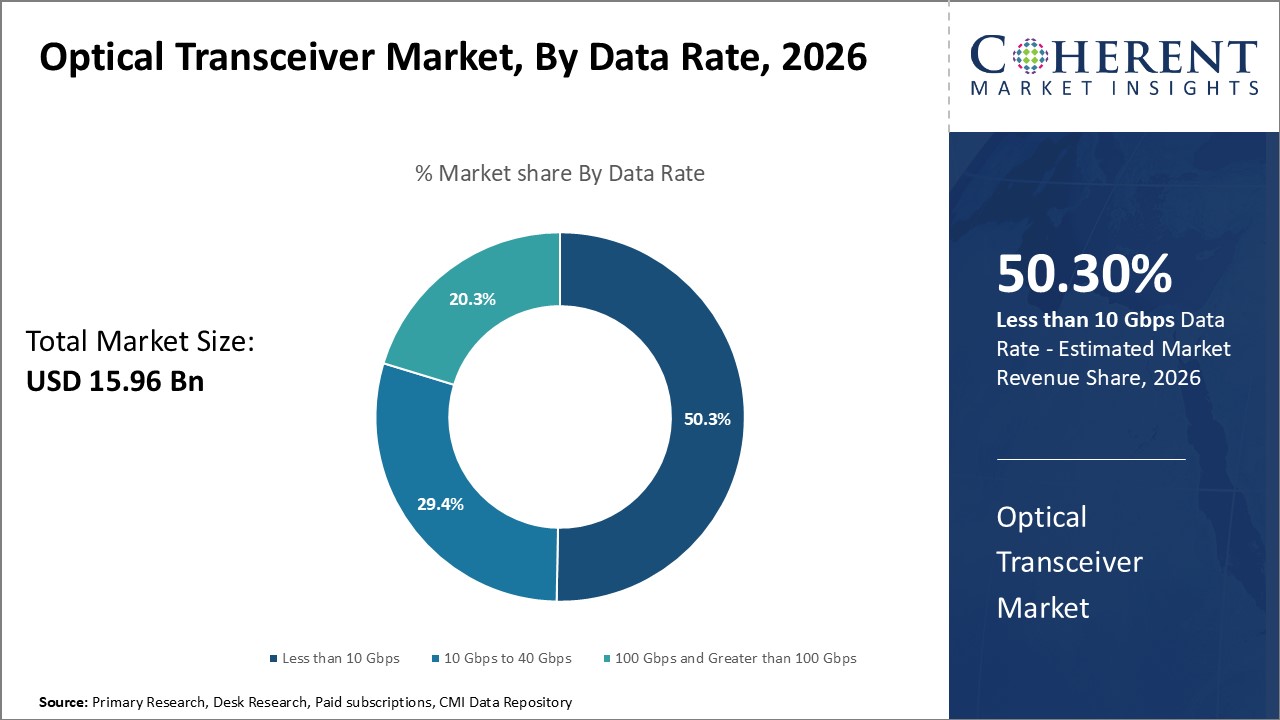
- By Data Rate, less than 10 Gbps expected to hold largest market share in 2026 owing to the legacy network infrastructure.
- By Application, Telecommunication acquired the prominent market share in 2026 owing to the growth of 5G networks.
- By Region, North America dominates the overall market with an estimated share of 37.1% in 2026 owing to the massive data center expansion.
Market Overview
The optical transceiver market continues to grow as data centers, telecom operators, and enterprises rely increasingly on high-speed fiber-optic communication. Rising internet traffic, expanding cloud usage, AI-driven workloads, and upgrades across metro, core, and 5G networks actively push this demand forward. Companies adopt diverse data rates and form factors to achieve higher bandwidth, lower latency, and better energy efficiency. Ongoing innovations in silicon photonics and coherent optics strengthen performance and encourage wider deployment across network environments.
Current Events and Its Impact on the Optical Transceiver Market
Current Events | Description and its impact |
Geopolitical Tensions and Trade Policies |
|
Technological Advancements and Industry Standards |
|
Environmental and Supply Chain Sustainability Initiatives |
|
Segmental Insights

- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Optical Transceiver Market Insights, By Protocol - Fiber Channel contribute the highest share of the market owing to its 5G & telecom network expansion
Fiber Channel hold the largest market share of 33.3% in 2026. Fiber Channel demand grows as data centers and enterprises prioritize reliable, high-performance storage networks. Organizations increasingly deploy SAN architectures, expand storage virtualization, and scale cloud and hybrid IT environments, driving the need for Fiber Channel optical transceivers. They use these modules to ensure secure, low-latency data movement and to strengthen backup and disaster recovery operations. Ongoing transitions to higher-speed Fibre Channel standards further encourage the adoption of advanced optical transceiver solutions. For instance, in November 2025, Broadcom launched the Brocade X8 Directors and G820 switches, making the industry’s first 128G Fibre Channel platforms available for mission-critical enterprise and AI workloads. The company also expanded its partnership with NEC to accelerate adoption of VMware Cloud Foundation-based private clouds.
Optical Transceiver Market Insights, By Data Rate - Less than 10 Gbps contribute the highest share of the market owing to its cost efficiency
The demand for optical transceivers below 10 Gbps grows as organizations continue using legacy network infrastructure and pursue cost-effective upgrades. Enterprises, industrial facilities, and access networks deploy lower-speed modules for building networks, campus connectivity, and short-reach links where high bandwidth is unnecessary. Telecom operators utilize these transceivers in specific fronthaul and backhaul applications. Their energy efficiency, reliability, and compatibility with existing systems actively drive adoption across a variety of networking environments. For instance, in September 2025, VIAVI Solutions introduced two new all-in-one handheld testers, expanding its portable device lineup for last-mile fiber activation and multi-gig power testing at data rates up to 10 Gbps.
Optical Transceiver Market Insights, By Application - Telecommunication contribute the highest share of the market owing to its network upgrades to support higher bandwidth
The telecommunication segment fuels demand for optical transceivers as operators expand 5G networks, upgrade metro and core infrastructure, and deploy fiber-to-the-home and fiber-to-the-tower solutions. Rising mobile data traffic, growing cloud services, and increasing IoT applications drive the need for high-bandwidth, low-latency optical links. Telecom providers implement advanced coherent and pluggable optics to boost network capacity, reliability, and energy efficiency. Government broadband initiatives and competitive pressures to enhance service quality actively accelerate the deployment of optical transceivers across telecom networks. For instance, in April 2025, Jabil Inc. has launched 1.6T transceivers capable of transmitting data at 1.6 Terabits per second, expanding its photonics portfolio to support growing AI/ML workloads, HPC, cloud computing, and high-speed data center interconnects.
Regional Insights

North America Optical Transceiver Market Trends
North America dominates the overall market with an estimated share of 37.1% in 2026. The North American optical transceiver market grows as hyperscale data centers expand and organizations adopt AI and cloud computing. Telecom operators modernize networks through 5G rollouts, fiber deployments, and metro-core upgrades, driving demand for advanced optical modules. The region leads in adopting high-speed coherent optics, silicon photonics, and energy-efficient transceivers. Increasing digital traffic, government broadband initiatives, and enterprise network transformations actively boost market activity, positioning North America as a major hub for innovation and large-scale optical transceiver deployment. For instance, in October 2026, Credo Technology Group Holding Ltd launched its ZeroFlap (ZF) optical transceiver line, delivering secure, high-speed connectivity with improved reliability and energy efficiency, and supporting 400G, 800G, and 1.6T network speeds.
Europe Optical Transceiver Market Trends
The European optical transceiver market grows as telecom operators and enterprises upgrade infrastructure to handle rising digital traffic and next-generation networks. Expanding 5G networks, deploying fiber-to-the-home, and enhancing metro-core systems drive demand for high-speed, reliable optical modules. Europe prioritizes energy-efficient and sustainable network solutions, prompting widespread adoption of low-power. Increasing cloud services, modernizing data centers, and implementing government-backed digital connectivity programs actively boost deployment, establishing the region as a leading market for innovative optical transceiver technologies.
United States Optical Transceiver Market Trends
The United States optical transceiver market expands rapidly as cloud service providers, enterprises, and telecom operators build high-speed networks. Hyperscale data center growth and AI-driven workloads push demand for advanced optical modules that deliver high bandwidth and low latency. Telecom companies deploy 5G infrastructure and upgrade fiber networks, while enterprises modernize campus and metro systems. Focus on energy-efficient and scalable solutions encourages adoption of optics and silicon photonics, positioning the U.S. as a key hub for innovation and large-scale optical transceiver deployment. For instance, in April 2026, Jabil Inc. has launched 1.6T transceivers that transmit data at 1.6 Terabits per second, expanding its photonics portfolio to support growing AI/ML workloads, HPC, cloud computing, and high-speed data center interconnects.
United Kingdom Optical Transceiver Market Trends
The United Kingdom optical transceiver market expands as telecom operators and enterprises upgrade network infrastructure to handle rising data traffic and growing digital service demands. Expanding 5G networks, deploying fiber-to-the-premises projects, and enhancing metro and core networks drive demand for high-speed, reliable optical modules. Emphasis on sustainable, energy-efficient technologies promotes adoption of low-power transceivers. Growing cloud adoption, modernizing data centers, and government initiatives to improve broadband connectivity actively boost deployment, positioning the UK as a key market for advanced optical transceiver solutions.
End-user Feedback and Unmet Needs in the Optical Transceiver Market
- Demand for Higher Bandwidth and Speed: End-users increasingly report that existing transceivers struggle to meet growing data traffic from cloud, AI, and 5G applications. They seek higher-speed modules with improved throughput to support latency-sensitive workloads. Current solutions sometimes limit scalability, prompting demand for optical transceivers that can deliver consistent high performance across expanding network infrastructures.
- Energy Efficiency and Thermal Management: Users highlight high power consumption and heat generation as critical challenges, especially in dense data centers. There is a need for energy-efficient optical transceivers that maintain performance while reducing operational costs. Effective thermal management and low-power designs remain a top priority to support sustainable and reliable network operations.
- Interoperability and Standardization Issues: Many end-users face challenges integrating transceivers from different vendors due to compatibility issues. Lack of standardized form factors, protocols, and interfaces can disrupt network deployment. Users seek transceivers that ensure seamless interoperability, backward compatibility, and flexibility to work across multiple platforms, reducing integration complexity and downtime.
Optical Transceiver Market Trend
Transition to Ultra-High-Speed Modules
The optical transceiver market is shifting rapidly toward ultra-high-speed modules such as 100G, 400G, and 800G to address the ever-increasing demand for data throughput in cloud computing, AI, and hyperscale data centers. Organizations are upgrading legacy systems to maintain low latency and high bandwidth across core, metro, and access networks. The trend reflects a need for scalable infrastructure capable of supporting next-generation applications while future-proofing networks. As companies anticipate growing workloads and complex networking requirements, investments in advanced, high-capacity optical transceivers are becoming a strategic priority for maintaining competitive advantage.
Growing Adoption of Coherent and Pluggable Optics
Coherent and pluggable optical transceivers are gaining prominence due to their ability to combine high data rates, long reach, and reduced energy consumption. Telecom operators and data center providers increasingly favor pluggable modules that simplify network upgrades and enable flexible deployment across metro, long-haul, and hyperscale environments. Coherent optics allow for efficient signal transmission over longer distances without the need for complex amplification, making network design more streamlined.
Optical Transceiver Market Opportunity
Adoption of 5G Networks and Edge Computing
The global rollout of 5G networks and the expansion of edge computing infrastructures offer strong market potential. Telecom operators need optical transceivers for fronthaul, midhaul, and backhaul links, connecting edge nodes, towers, and core networks. Edge computing requires low-latency, high-bandwidth connectivity to support real-time applications such as autonomous vehicles, AR/VR, and IoT analytics. Optical transceiver providers can capitalize on these needs by offering compact, energy-efficient modules capable of supporting high-density deployments.
Market Report Scope
Optical Transceiver Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 15.96 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 12.4% | 2033 Value Projection: | USD 36.18 Bn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | HUBER+SUHNER Cube Optics AG, II-VI Incorporated, Broadcom Inc., Accelink Technologies, Huawei Technologies Co. Ltd., Lumentum Operations LLC (Lumentum Holdings), Source Photonics (Redwood Capital), Sumitomo Electric Industries Ltd., Reflex Photonics Inc., and Fujitsu Optical Components Limited | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Optical Transceiver Market News
- In August 2025, TDK Corporation expanded its PLEC69B series of thin-film inductors (1.2 x 0.6 x 0.95 mm), designed to separate data signals from power in optical transceivers used in AI data centers.
- In February 2025, ST has introduced SiPho and next-gen BiCMOS technologies to boost performance and energy efficiency in cloud optical interconnects for data centers and AI clusters.
- In September 2025, NEC Corporation expanded its optical transceiver lineup with the "25G SFP28 80km BiDi," enabling 25Gb/s transmission over distances up to 80km.
Analyst Opinion (Expert Opinion)
- The optical-transceiver sector appears to be approaching a structural turning point—driven not by a fundamental shift associated with intensifying hyperscale requirements and the rapid acceleration of AI workloads. Hyperscale operators already constitute a significant portion of coherent digital-optics deployments, and as 400G coherent modules become the foundation of data-center interconnect architectures, the traditional pluggable-optics model is increasingly strained.
- The principal inflection point is the rise of silicon photonics. Investment momentum is accelerating: recent financing rounds have enhanced device performance and reduced integration timelines, while coordinated R&D efforts are delivering 20–25% improvements in signal integrity and coupling efficiency. Silicon photonics is moving beyond its former “short-reach only” characterization and is beginning to expand meaningfully into domains traditionally dominated by coherent optics.
- Nonetheless, the market faces substantial disruptive risk. Nvidia’s advancement of co-packaged optics (CPO)—integrating silicon-photonics components directly within switch ASICs to enable throughput of up to 1.6 Tbps per port—has the potential to significantly diminish the relevance of pluggable optics in next-generation AI data centers. Should CPO achieve broad commercial scalability, demand for conventional transceivers could contract sharply.
- Power consumption remains a critical constraint. Leading hyperscale operators are specifying sub-15-watt power budgets for 400G modules, yet many existing designs struggle to meet this requirement without compromising performance. Market leadership is expected to consolidate around organizations capable of resolving these thermal and efficiency challenges without sacrificing operational metrics.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- Global Optical Transceiver Market, By Protocol
- Ethernet
- Fiber Channel
- CWDM/DWDM
- FTTx
- Other Protocols
- Global Optical Transceiver Market, By Data Rate
- Less than 10 Gbps
- 10 Gbps to 40 Gbps
- 100 Gbps
- Greater than 100 Gbps
- Global Optical Transceiver Market, By Application
- Data Center
- Telecommunication
- Regional Insights (Revenue, USD Mn, 2021 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC Countries
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
- North America
- Key Players Insights
- HUBER+SUHNER Cube Optics AG
- II-VI Incorporated
- Broadcom Inc.
- Accelink Technologies
- Huawei Technologies Co. Ltd.
- Lumentum Operations LLC (Lumentum Holdings)
- Source Photonics (Redwood Capital)
- Sumitomo Electric Industries Ltd.
- Reflex Photonics Inc.
- Fujitsu Optical Components Limited
Sources
Primary Research interviews
- Engineers and product managers at silicon photonics companies (e.g., Intel, GlobalFoundries)
- R&D leaders at module manufacturers (e.g., Lumentum, Coherent)
- Network architects from hyperscale cloud data centers
Databases
- IEEE Xplore (technical papers on optical transceivers and coherent optics)
- arXiv (preprint research on photonics, coherent systems)
- Optica Publishing Group online archives
Magazines
- Photonics Spectra — industry‑oriented features on fiber optics and photonic components
- Photonics Focus (SPIE) — technology trends and applications
- Optics & Photonics News — developments in photonics, fiber optics, and communications
Journals
- Journal of Lightwave Technology — foundational and advanced research in guided‑wave optics
- Journal of Optical Communications and Networking — networking and optical systems research
- eLight — cutting‑edge photonic and integrated optics research
- Optik — international optics research and optical component studies
- Current Optics and Photonics — open-access research in applied photonics
Newspapers / News Sources
- Reuters — for technology news on co‑packaged optics and major corporate moves
- Tom’s Hardware — for applied optical technology news such as hollow‑core fiber breakthroughs
- Investors.com / Investor news sites — coverage of optical‑component company earnings and strategy (e.g., Lumentum, Coherent)
Associations
- IEEE Photonics Society — thought leadership, standards, community perspectives
- The Fiber Optic Association (FOA) — fiber‑optics certification, training, and technical reference materials
- Fiber Optic Sensing Association (FOSA) — broad fiber‑optics industry perspectives, policy, and innovation
Public Domain Sources
- arXiv preprints (e.g., coherent lightwave communications, photonic integration) such as Phase-coherent lightwave communications with frequency combs
- Open access conference proceedings (e.g., SPIE, ECOC) freely available via institutional repositories
- Preprint surveys on optical wireless / free-space optics, e.g., A Comparative Survey of Optical Wireless Technologies
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of information for last 8 years
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Optical Transceiver Market is estimated to be valued at USD 15.96 Bn in 2026, and is expected to reach USD 36.18 Bn by 2033.
The CAGR of the Optical Transceiver Market is projected to be 12.4% from 2026 to 2033.
Rise in need for advanced communication and growing demand for cloud-based services are fuelling the market.
The Fibre Channel segment is the leading component segment in the market.
Growing complexity of networks and adverse situations resulting from COVID-19 pandemic are the major factors restraining the market.
HUBER+SUHNER Cube Optics AG, II-VI Incorporated, Broadcom Inc., Accelink Technologies, Huawei Technologies Co. Ltd., Lumentum Operations LLC (Lumentum Holdings), Source Photonics (Redwood Capital), Sumitomo Electric Industries Ltd., Reflex Photonics Inc., and Fujitsu Optical Components Limited.