

Wind Turbine Nacelle Market Size and Forecast — 2026-2033
Global wind turbine nacelle market is estimated to be valued at US$ 6.17 Bn in 2026 and is expected to reach US$ 9.40 Bn by 2033, exhibiting a compound annual growth rate (CAGR) of 6.2% from 2026 to 2033. Governments across the globe are strongly promoting investments in renewable energy sources to reduce dependence on fossil fuels. This leads to increased installations of wind turbines worldwide.
Governments are providing several incentives for wind energy projects, and this leads to increased investments. echnological advancements such as development of larger and more efficient wind turbines also drives the market growth. However, high initial installation costs of wind turbines and intermittency of wind energy can hamper the market growth.

Improvements in wind turbine designs
With governments and organizations focusing strongly on increasing the share of renewable energy sources to tackle climate change, the wind energy market has expanded significantly in recent years. Wind turbine manufacturers have been investing heavily in research and development activities to design bigger and more efficient wind turbines that can generate power even at lower wind speeds. Advanced rotor blade designs utilizing composites allow for longer blades that capture more energy from wind. At the same time, advancements in conditions monitoring technologies optimize turbine performance and reduce downtime. Larger turbine capacities also mean more energy can be harnessed from each individual turbine. Such design-led improvements boost demand for wind turbine nacelle that require upgrades to handle the additional power loads. Going forward, we can expect newer multi-megawatt turbine designs with rotor diameters of over 250 feet to penetrate the market further and bolster nacelle demand.
Insights, By Deployment
 Insights, By Deployment- Low infrastructure costs drives the onshore segment growth
In terms of deployment, onshore segment is estimated to contribute the highest market share of 67.4% in 2026, due to its significantly lower infrastructure costs as compared to offshore wind farms. Land transportation for construction and installation is far more economical than marine logistics for offshore projects. Onshore turbines have lower annual operation and maintenance expenses since technicians can easily access turbines via roads for repairs and servicing. The fixed foundation cost for onshore turbines mounting directly on concrete is much cheaper than the heavy hydraulic or gravity-based structures required in seas. Furthermore, grid connectivity is simpler to establish for onshore farms located near towns with existing transmission networks. These substantial cost advantages have encouraged widespread growth of onshore wind power globally, thus, driving ongoing technological advancements and economies of scale that continue lowering costs.
Insights, By Turbine Capacity
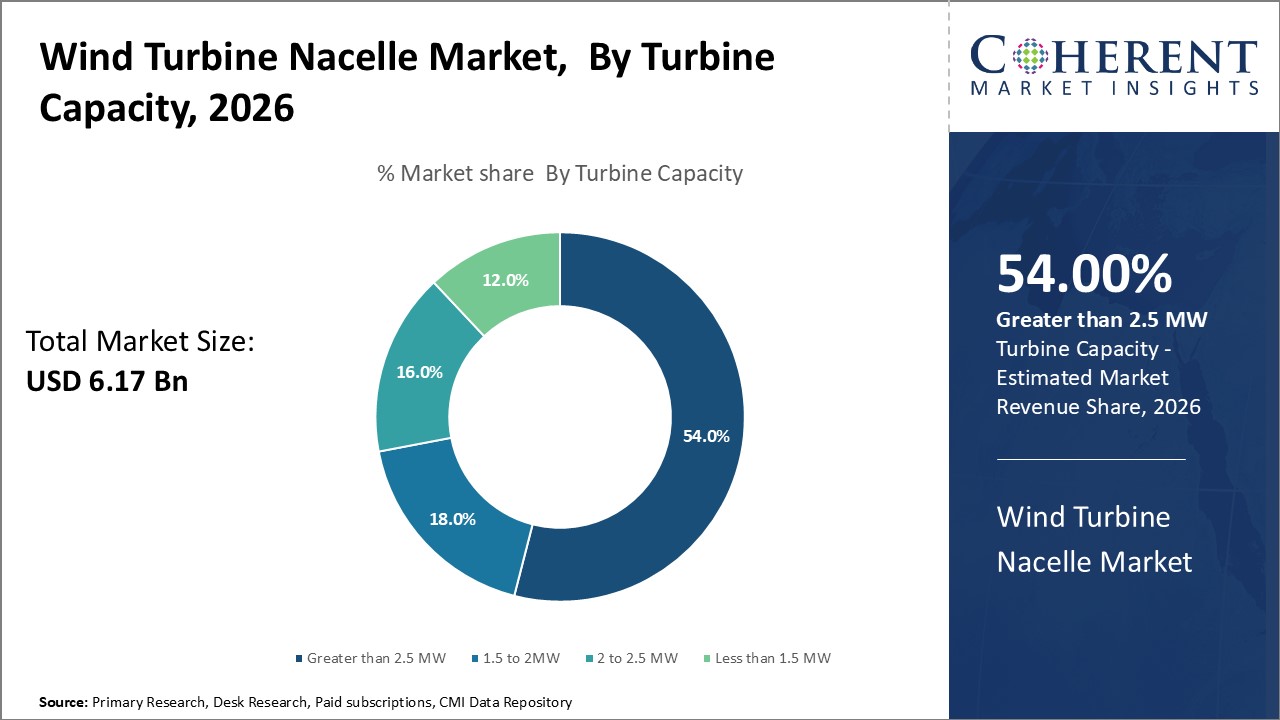
Insights, By Turbine Capacity- Increasing demand for large turbines drives the greater than 2.5 MW segment growth
In terms of turbine capacity, greater than 2.5 MW segment is estimated to contribute the highest market share of 54% in 2026 due to rising demand for larger, more powerful turbines. Utilities and power producers prefer higher capacity turbines that generate more annual energy by using fewer turbines to cover a given land area. Larger rotor diameters capture wind energy more efficiently at lower mid-range wind speeds. Significant research and development has enabled steady scaling up of turbine sizes to efficiently harness wind resources further offshore or in areas with lower average wind speeds. Major manufacturers now offer multi-megawatt turbine models meeting the growing industry preference for consolidated generation capacities per wind farm. This shift to larger capacity turbines boosts the greater than 2.5 MW segment growth.
Insights, By Application
Insights, By Application- Residential micro wind turbines see strong growth driven by off-grid adoption
In terms of application, the residential segment is estimated to contribute the highest market share of 37.4% in 2026 due to rising demand for small-scale, off-grid wind power solutions. Micro wind turbines under 1 kW in capacity have gained popularity for residential, rural, and off-grid applications where connection to central power networks is uneconomical or impossible. Their ability to provide clean, renewable energy independence at the domestic level attracts many homeowners, cottage or cabin owners, and off-grid communities. Distributed energy sources become particularly valuable during extreme weather events and power outages. The simplicity and reliability of micro wind solutions appeal to both developed and developing markets. Ongoing cost reductions and performance improvements boosts the residential segment growth, especially in off-grid and developing regions seeking distributed renewable energy access.
Regional Insights
 Europe dominates the global wind turbine nacelle market with estimated 39.4% market share in 2026 due to strong historical presence and government support for renewable energy in key countries. Countries like Germany, U.K., France and Denmark have emerged as major markets in the region due to conducive policy environment and focus on developing local supply chain to support indigenous wind power industry. Large industrial players have established manufacturing facilities close to major wind farms to cater growing demand. Further, European countries are also focusing on exports realizing competitive advantage in engineering and manufacturing expertise.
Asia Pacific has emerged as the fastest growing regional market. China, as world's largest installer of new wind capacity annually, has ramped up investments significantly to meet renewable energy targets. Local giants have come up dominating supply landscape with help of favorable local content norms. Meanwhile, other Southeast Asian countries like India, Vietnam and Philippines have also begun promoting wind energy progressively to reduce dependence on fossil fuels and de-carbonize power sector. This has attracted global OEMs to set up local plants to gain early mover advantage as these markets continue to grow exponentially in times to come.
While Europe still accounts for the largest share of global nacelle production due to supply contracts for existing sizable fleet, Asia Pacific is likely to surpass Europe in mid-term driven by massive new installation plans. Localization will be the key differentiator for suppliers to win orders against rising protectionism. Further, pricing pressure is also mounting in Asia Pacific as local suppliers gain competence with supporting policy push. This prompts technology transfers and collaborations by global players to stay cost competitive while meeting local content obligations for new projects.
Europe dominates the current wind turbine nacelle market landscape, the bigger growth story is in Asia Pacific, led by China, over the coming years as countries significantly increase their renewable energy installed capacity to meet climate commitments. Localization will remain a determining success factor for suppliers in both regions to capitalize on this growth.
Market Players, Key Development, and Competitive Intelligence
 Increasing prominence of offshore wind energy
The offshore wind energy sector has emerged as a major focus area for achieving renewable targets, given the stronger and more consistent wind speeds available in coastal waters. Several countries in Europe have been pioneering large offshore wind projects. However, operational challenges in the marine environment require specialized engineering of wind turbine components. This has created opportunities for manufacturers of offshore-specific nacelle systems with features like enhanced structural integrity, effective corrosion protection and maintenance accessibility from vessels. The nacelle is also a crucial interface for the electrical systems onboard servicing vessels. As major markets like China, US and others rapidly build their offshore networks in the coming decade, it will be an important driver propelling the offshore wind turbine nacelle and components industry to new heights. Growing experience worldwide is also continuously improving designs to boost energy output and reduce costs from offshore installations.
Key Developments
- In November 2021, Vestas, a wind turbine manufacturer, introduced a groundbreaking modular nacelle design, offering customization options. This new product is aimed at streamlining market entry, simplifying logistics, operations, construction, and maintenance processes. Vestas also believes that the upcoming modular nacelle units can be transported through tunnels, over bridges, and via rail systems, requiring less specialized handling.
- In September 2021, Spain-based Siemens Gamesa Renewable Energy and Denmark-based Orsted, a global wind leader, opened a new nacelle assembly facility at the Port of Taichung, Taiwan. This facility marks their first manufacturing site in the Asia Pacific region and their first outside of Europe. It is expected to produce nacelles for Orsted's 900MW Greater Changua 1 & 2a offshore wind farms in Taiwan.
- In November 2021, Vestas, a wind turbine manufacturer, introduced a new modular nacelle design that allows for customization. This product aims to speed up market entry and simplify various operations, construction, and maintenance tasks. The manufacturer also believes that the upcoming modular nacelle units can be transported more easily over rail systems, bridges, and through tunnels, requiring less specialized handling.
*Definition: The wind turbine nacelle market consists of the manufacturing and sales of enclosures mounted atop wind turbine towers that house all of the generating components of a wind turbine. Nacelles protect electrical generators, gearboxes, and drive trains from the elements while enabling them to be oriented toward the wind through the use of a yaw drive. Major components include the generator, gearbox, and brake systems. Key players in this market manufacture nacelles optimized for various wind turbine models and tower sizes.
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Market Report Scope
Wind Turbine Nacelle Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 6.17 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 6.2% | 2033 Value Projection: | USD 9.40 Bn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | General Electric, Molded Fiber Glass, Vesta, AREVA WIND, Bora Energy AVANTIS Energy, DeWind, ENERCON, EWT, GBT Composites Technology, Xinjiang Goldwind Science and Technology, Hexcel, Indutch Composites Technology, Inoxwind, Reliance Industries, Leitner, NORDEX, ReGen Powertech, SR Fibreglass Auto, and Wind World | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Analyst Opinion (Expert Opinion)
 Market Challenge: High setup & installation costs of wind turbines
Wind power is dependent on natural weather conditions and availability of wind which can impact consistent energy production. High initial installation costs and maintenance requirements can hamper the market growth. Remote locations for setting up wind farms increase expenses. Technological innovations in turbine designs are occurring rapidly which risks making existing nacelles obsolete sooner. Standardization across manufacturers is still lacking.
Market Opportunity: Offshore wind turbine projects & growing offshore installation market
Global focus on renewable energy and incentives boosts demand for wind power. Nacelle components require frequent replacement providing recurring business. Technologies like sensor monitoring and use of lightweight materials in nacelles boost efficiency. Growing international markets and offshore wind projects open new avenues. Partnerships across manufacturing and maintenance cycles can optimize costs.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- Deployment Insights (Revenue, US$ BN, 2021 - 2033)
- Onshore
- Offshore
- Turbine Capacity Insights (Revenue, US$ BN, 2021 - 2033)
- Less than 1.5 MW
- 1.5 to 2MW
- 2 to 2.5 MW
- Greater than 2.5 MW
- Application Insights (Revenue, US$ BN, 2021 - 2033)
- Residential
- Utility
- Industrial
- Commercial
- Regional Insights (Revenue, US$ BN, 2021 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East & Africa
- North America
- Key Players Insights
- Molded Fiber Glass
- Vesta
- AREVA WIND
- Bora Energy AVANTIS Energy
- DeWind, ENERCON
- EWT
- GBT Composites Technology
- Xinjiang Goldwind Science and Technology
- Hexcel
- Indutch composites technology
- Inoxwind
- Reliance Industries
- Leitner
- NORDEX
- ReGen Powertech
- SR Fibreglass Auto
- Wind World
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Wind Turbine Nacelle Market is estimated to be valued at USD 6.17 Bn in 2026, and is expected to reach USD 9.40 Bn by 2033.
The CAGR of the Wind Turbine Nacelle Market is projected to be 6.2% from 2026 to 2033.
Improvements in wind turbine designs and increasing prominence of offshore wind energy are the major factors driving the growth of global wind turbine nacelle market.
High setup & installation costs of wind turbines and intermittency in wind speed availability are the major factors hampering the growth of global wind turbine nacelle market.
In terms of deployment, onshore segment is estimated to dominate the market in 2026.
General Electric, Molded Fiber Glass, Vesta, AREVA WIND, Bora Energy AVANTIS Energy, DeWind, ENERCON, EWT, GBT Composites Technology, Xinjiang Goldwind Science and Technology, Hexcel, Indutch Composites Technology, Inoxwind, Reliance Industries, Leitner, NORDEX, ReGen Powertech, SR Fibreglass Auto, and Wind World
North America is expected to lead the global wind turbine nacelle market in 2026.