

Cell Therapy Market Size and Forecast – 2026 to 2033
Global cell therapy market is estimated to be valued at USD 3,109.6 Mn in 2026 and is expected to reach USD 5,983.1 Mn by 2033, exhibiting a compound annual growth rate (CAGR) of 9.8% from 2026 to 2033.
Key Takeaways
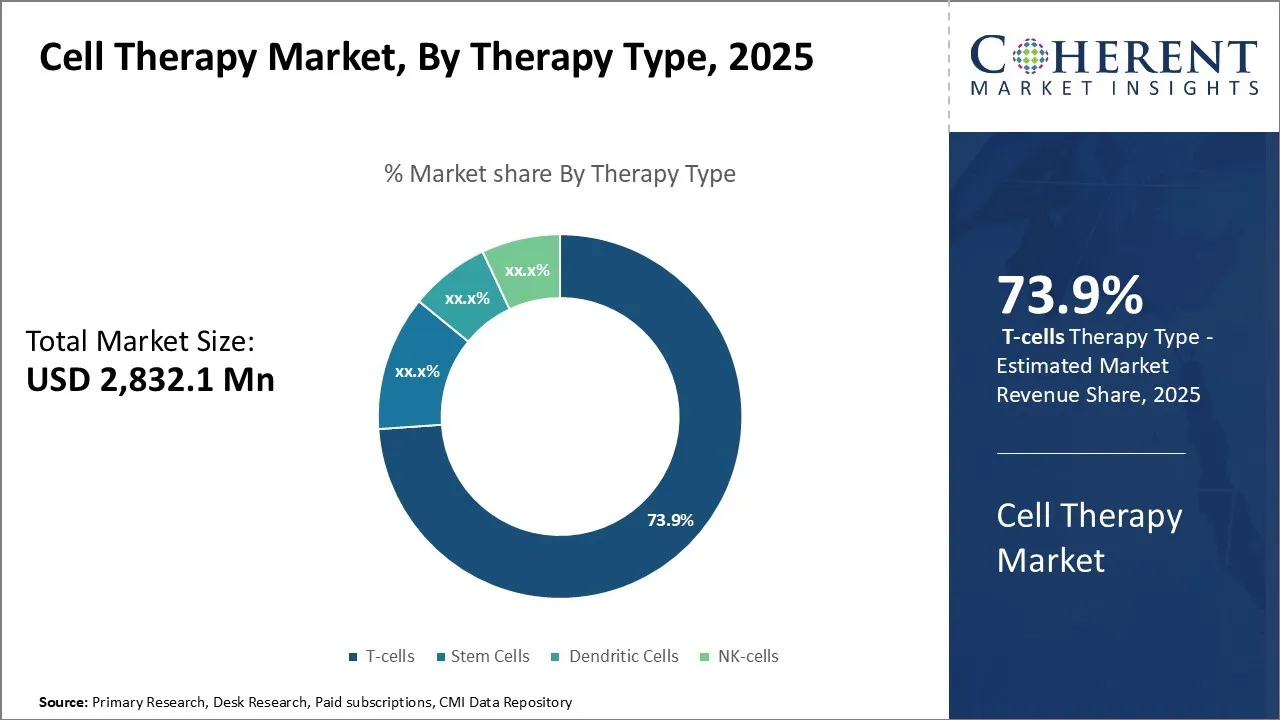
- By Therapy Type, T-cells hold the largest market share of 74.9% in 2026 owing to the rising incidence of cancer.
- By Indication, Oncology expected to hold largest market share of 71.2% in 2026 owing to its advances in genetic engineering and cell technologies.
- By End User, Hospitals acquired the prominent market share of 42.7% in 2026 owing to the advanced infrastructure & clinical capabilities.
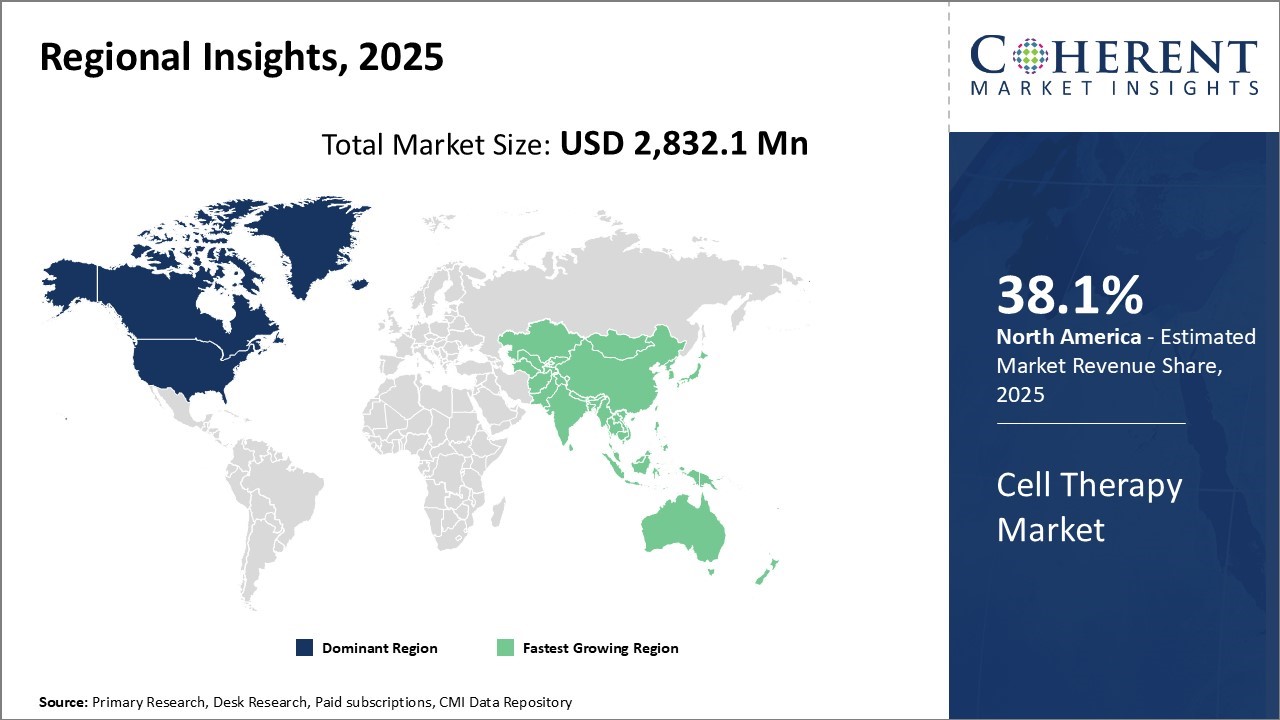
- By Region, North America dominates the overall market with an estimated share of 38.1% in 2026 owing to the strong R&D ecosystem & clinical trial infrastructure.
Market Overview
The global cell therapy market is rapidly expanding as advancements in regenerative medicine, immunotherapy, and genetic engineering drive innovation. Researchers and companies are developing therapies such as CAR-T cells, stem cells, and TCR therapies to treat oncology, rare diseases, and autoimmune disorders. Rising cases of chronic and genetic diseases, along with supportive regulatory frameworks and strong clinical pipelines, are boosting demand. Hospitals and specialized treatment centers are building infrastructure to administer these therapies, while technological innovations and strategic collaborations are improving accessibility and commercialization worldwide.
Current Events and Its Impact on the Cell Therapy Market
Current Events | Description and its impact |
Regulatory Developments in Key Regions |
|
Technological Advancements and Innovations |
|
Investment and Funding Landscape |
|
Segmental Insights
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Cell Therapy Market Insights, By Therapy Type: T-Cells contribute the highest share of the market owing to its robust R&D investments and clinical pipeline.
T-cells hold the largest market share of 74.9% in 2026. T-cells or T lymphocytes form an essential part of the adaptive immune system, and are capable of recognizing infected or cancerous cells. Research in recent years has shown the potential of engineered T-cells, known as CAR T-cell therapy, to identify and destroy cancer cells that traditional drugs are unable to eliminate. Pioneering drugs such as Kymriah and Yescarta achieved impressive complete remission rates in late-stage clinical trials for blood cancers. Their subsequent approval by regulatory bodies has validated CAR T-cell therapy as a mainstream treatment option. Key factors powering the T-cell segment include improved understanding of T-cell biology and immunology, development of novel technologies for T-cell engineering and expansion, refinement of lymphodepletion regimens to improve T-cell engraftment, and identification of novel tumor-associated antigens. For instance, in November 2025, India expanded access to cancer immunotherapy by launching its first indigenous CAR-T cell therapy, NexCAR19, developed by ImmunoACT, a spin-off from IIT Bombay.

Cell Therapy Market Insights, By Indication: Oncology contributes the highest share of the market owing to its increased investment and funding.
Oncology expected to hold largest market share of 71.2% in 2026. The oncology segment strongly drives the cell therapy market as the high prevalence of blood and solid cancers and the limitations of conventional treatments create urgent demand. Researchers and companies are advancing CAR-T, TCR, and other immune cell therapies to improve precision and effectiveness in cancer care. Robust clinical pipelines, successful trial results, and supportive regulatory measures are boosting adoption. For instance, in May 2025, HCG Manavata Cancer Centre and SunAct – Advanced Cancer Therapies opened SunAct’s fourth national Centre of Excellence in Cell and Gene Therapy at HCGMCC, Nashik, inaugurated by Dr. Shripad Banavali, Chair of Paediatric Haemato-Oncology at the Indian Academy of Paediatrics and Academic Director at Tata Memorial Hospital, Mumbai.
Cell Therapy Market Insights, By End User: Hospitals contribute the highest share of the market owing to its experience managing risks & side‑effects.
Hospitals acquired the prominent market share of 42.7% in 2026. Hospitals actively drive the cell therapy market by offering the infrastructure and clinical expertise needed to deliver complex treatments. They operate ICUs, infusion centers, and specialized laboratories to ensure safe administration and manage side effects. Hospitals conduct and support clinical trials, providing early patient access to innovative therapies. Their strong connections with payers and experience in reimbursement processes promote therapy adoption. Moreover, hospitals invest in manufacturing capabilities, integrate advanced technologies, and form strategic partnerships to expand cell therapy services and enhance patient access. For instance, in October 2025, CTMC, a joint venture between Resilience and MD Anderson Cancer Center, collaborated with Einstein Hospital Israelita in São Paulo, Brazil, to accelerate the adoption of cell therapy across Brazil and Latin America.
Role of AI (Artificial Intelligence) in the Cell Therapy Market
Artificial Intelligence (AI) is actively transforming the cell therapy market by advancing research, development, and manufacturing processes. AI algorithms analyze complex biological data to identify optimal cell targets, predict therapy outcomes, and accelerate drug discovery. In manufacturing, AI enhances quality control, optimizes cell expansion, and ensures consistent results. It also guides clinical decision-making by personalizing treatments and monitoring patient responses. By streamlining development, increasing precision, and minimizing errors, AI enables companies and healthcare providers to deliver safer, more effective, and accessible cell therapies. For instance, in February 2025, Cellino partnered with Mass General Brigham’s Gene and Cell Therapy Institute to launch the world’s first hospital-based autologous iPSC Foundry. Using Cellino’s AI-driven Nebula technology, the initiative aims to create a nationwide network of decentralized hubs delivering personalized cell and tissue therapies directly at the point of care.
Regional Insights
North America Cell Therapy Market Trends
North America dominates the overall market with an estimated share of 38.1% in 2026. North America’s cell therapy market is rapidly evolving as companies develop allogeneic “off‑the‑shelf” platforms, leveraging advanced manufacturing infrastructure and strong R&D capabilities. Leading biotech hubs are expanding modular, automated production models to increase efficiency. Accelerated regulatory pathways, including U.S. FDA designations, enable faster clinical advancement, while robust payer-provider networks and hospital-based cell therapy centers improve patient access. Biopharma firms and CMOs form strategic partnerships to streamline commercialization and scale delivery of therapies across the region. For instance, in October 2026, Visionary Holdings Inc. has signed a strategic agreement with Jiangsu Yike Regenerative Medical Technology to create Visionary Yike Stemcell Technologies Inc., a Canada-based joint venture focused on advancing stem cell research, clinical applications, and global commercialization.
Asia Pacific Cell Therapy Market Trends
The Asia‑Pacific cell therapy market is rapidly advancing as a global innovation hub, with Japan, China, and South Korea leading development through strong government support and extensive R&D investments. Companies in the region are conducting a surge of clinical trials, with over 650 ongoing CGT studies. Developers are expanding advanced regenerative platforms, including cell‑sheet therapies, while local CDMOs are scaling up capacity to meet growing demand and accelerate commercialization across the region. For instance, in November 2026, Science and Technology Minister Dr. Jitendra Singh launched India’s first indigenous CRISPR-based gene therapy for Sickle Cell Disease, primarily targeting the tribal population.
United States Cell Therapy Market Trends
In the United States, companies are rapidly advancing the cell therapy market through allogeneic “off‑the‑shelf” CAR‑T platforms, leveraging a thriving CDMO ecosystem and expanding GMP manufacturing capacity. Researchers are applying cutting-edge gene editing and cell engineering technologies to develop new therapies. Regulatory agencies are actively streamlining approval pathways for innovative treatments, while clinical trial activity continues to increase. Biotech firms, contract developers, and hospital networks are forming strong collaborations to accelerate commercialization and enhance patient access to these therapies. For instance, in August 2026, ADIA Nutrition Inc. launched its second nationwide TV campaign, showcasing Adia Med and its advanced regenerative stem cell treatments at the flagship clinic in Winter Park, Florida.
China Cell Therapy Market Trends
China’s cell therapy market is rapidly advancing as the government provides strong support, regulatory agencies streamline approvals, and reimbursement frameworks expand. Domestic companies are developing both autologous and allogeneic CAR‑T and TCR therapies while reducing costs through process innovations. Biotech hubs in Shanghai, Shenzhen, and Beijing are scaling up GMP manufacturing and CDMO capabilities. At the same time, companies are conducting more clinical trials, and growing demand for cancer treatments is establishing China as a key player in the global cell therapy market. For instance, in January 2024, Fosun Kite Biotechnology launched China’s first outcome-based CAR-T cell therapy plan, offering cancer patients up to 600,000 yuan ($84,300) refund if the treatment fails.
End-user Feedback and Unmet Needs in the Cell Therapy Market
- Patient Access and Affordability: Patients and caregivers frequently highlight challenges in accessing cell therapies due to high costs, complex hospital requirements, and limited treatment centers. They emphasize the need for more affordable therapies, broader insurance coverage, and expansion of specialized infusion and monitoring centers to improve availability across urban and rural regions.
- Safety and Side-effect Management: Healthcare providers report concerns about managing therapy-related adverse events such as cytokine release syndrome and neurotoxicity. They stress the need for improved safety protocols, real-time monitoring, and standardized management guidelines to reduce complications and enhance patient confidence in advanced cell therapies.
- Treatment Personalization: Clinicians and researchers indicate a demand for more personalized approaches to cell therapy. Differences in patient genetics, tumor profiles, and immune responses highlight the need for predictive biomarkers and tailored therapy designs that maximize efficacy while minimizing risks for individual patients.
Cell Therapy Market Trend
Expansion of Allogeneic “Off-the-Shelf” Therapies
The market is witnessing a shift from autologous to allogeneic cell therapies, allowing multiple patients to be treated from a single donor source. This trend enhances scalability, reduces manufacturing time, and lowers costs. Biotech companies are investing in universal donor cells and gene editing technologies to create off-the-shelf CAR-T and TCR therapies. Hospitals and CDMOs are adapting infrastructure to support these therapies, enabling faster patient access while maintaining quality and regulatory compliance across regions.
Integration of Artificial Intelligence and Automation
AI and automation are transforming cell therapy development, production, and clinical management. AI models analyze patient data to optimize cell selection, predict therapy responses, and streamline clinical trial design. Automated manufacturing systems enhance reproducibility, reduce human error, and accelerate production cycles. Together, these technologies improve efficiency, precision, and scalability. Stakeholders are increasingly leveraging AI-driven decision support tools to monitor patient outcomes and optimize treatment regimens, driving better clinical results and faster commercialization.
Cell Therapy Market Opportunity
Development of Allogeneic and Off-the-Shelf Platforms
The shift from patient-specific autologous therapies to universal allogeneic platforms presents a major market opportunity. Off-the-shelf therapies reduce manufacturing complexity, shorten treatment timelines, and expand scalability. Biotech companies can invest in gene-editing and immunomodulation to create universally compatible cells. Hospitals and CDMOs can adopt modular production and automated systems to handle larger volumes, improving access and reducing cost barriers while enabling faster treatment delivery to multiple patients simultaneously.
Market Report Scope
Cell Therapy Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 3,109.6 Mn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 9.8% | 2033 Value Projection: | USD 5,983.1 Mn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | Bristol Myers Squibb Company, Amgen Inc., Novartis AG, Gilead Sciences, Inc., Johnson & Johnson Services, Inc., Allogene Therapeutics, Athersys, Inc., Orchard Therapeutics, JW Therapeutics Co., Ltd., Dendreon Pharmaceuticals LLC., Autolus Therapeutics, APAC Biotech, CORESTEM, Inc., BioCardia, Inc., JCR Pharmaceuticals Co., Ltd., Oxford Biomedica, CASI Pharmaceuticals Inc. | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Cell Therapy Market News
- In November 2025, BRIC-THSTI, in collaboration with Miltenyi Biotec and BIRAC, launched India’s first hands-on training program on cell and gene therapy manufacturing, focusing on CAR-T cell therapy.
- In November 2025, India has launched its first indigenous CRISPR-based gene therapy for sickle cell disease, achieving a major Atmanirbhar Bharat milestone and providing new hope to communities, especially tribal populations, who are disproportionately affected by the condition.
- In October 2025, Mytos launched its automated CDMO to tackle regenerative medicine’s key bottleneck: scalable, cost-effective manufacturing of stem cell-derived therapies.
Analyst Opinion (Expert Opinion)
- The cell therapy sector appears to be at a critical inflection point. Clinical progress remains strong, with more than 900 CAR T trials initiated since 2020, far exceeding expectations. For instance, 57% of the 79 new gene, cell, and RNA therapy trials launched in the first quarter of 2025 focused on oncology, reflecting the continued confidence in cancer-targeting approaches.
- However, capital availability is tightening. Only 90 deals in advanced molecular therapies were recorded in Q1 2025—a 20% decline from the previous quarter—and early-stage funding is contracting, signaling growing investor caution. High development costs and complex manufacturing demands may be contributing to this hesitation.
- Manufacturing remains a significant bottleneck. Although companies such as Cellares are advancing automated production systems, the field continues to struggle with consistency and scalable processes. Despite the large number of ongoing trials, candidate attrition is substantial, with many therapies failing to progress due to limited durability or safety concerns.
- Solid tumors are becoming a central challenge. A recent randomized CAR T trial in gastric cancer demonstrated roughly a 40% improvement in survival over standard care, offering encouraging evidence. Yet, replicating the successes seen in hematologic cancers is difficult due to the solid tumor microenvironment, antigen variability, and T-cell exhaustion. Innovations such as dual-antigen CARs and enhanced trafficking strategies will be necessary to transition many programs from early proof-of-concept to standard-of-care viability.
- AI and mechanistic modeling are poised to become transformative enablers. Emerging multi-agent AI platforms are being applied to target discovery, toxicity prediction, and rational CAR design, while mathematical models are clarifying how factors such as CD4:CD8 ratios and tumor spatial architecture influence therapeutic response. As these tools mature, they may accelerate development and reduce program risk.
- Regulatory misalignment presents another challenge. Analysts have noted discrepancies in clinical data submitted to the FDA and EMA for various cell and gene therapies, suggesting insufficient harmonization. Such inconsistencies may lead to approval delays or additional requirements for bridging studies.
- Apart from this, the rapid rise of CAR-NK therapies is noteworthy. With more than 120 active trials and early evidence—such as a 73% response rate for CD19 CAR-NK with minimal severe CRS—these therapies may offer a safer, more scalable alternative. If clinical performance continues to improve, CAR-NK approaches could significantly disrupt the current CAR T landscape, particularly in contexts where safety and off-the-shelf manufacturing are paramount.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- Therapy Type Insights (Revenue, USD Mn, 2021 - 2033)
- Stem Cells
- T-cells
- Dendritic Cells
- NK-cells
- Indication Insights (Revenue, USD Mn, 2021 - 2033)
- Oncology
- Cardiology
- Neurology
- Others
- End User Insights (Revenue, USD Mn, 2021 - 2033)
- Hospitals
- Clinics
- Research Institutes
- Regional Insights (Revenue, USD Mn, 2021 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC Countries
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
- Key Players Insights
- Bristol Myers Squibb Company
- Amgen Inc.
- Novartis AG
- Gilead Sciences, Inc.
- Johnson & Johnson Services, Inc.
- Allogene Therapeutics
- Athersys, Inc.
- Orchard Therapeutics
- JW Therapeutics Co., Ltd.
- Dendreon Pharmaceuticals LLC.
- Autolus Therapeutics
- APAC Biotech
- CORESTEM, Inc.
- BioCardia, Inc.
- JCR Pharmaceuticals Co., Ltd.
- Oxford Biomedica
- CASI Pharmaceuticals Inc.
Sources
Primary Research interviews
- Interviews with cell‑therapy R&D heads at biotechnology companies (e.g., CAR‑T or stem-cell companies)
- Discussions with clinicians / principal investigators running clinical trials in cell therapy
- Conversations with manufacturing leads at hospital‑based GMP facilities or CDMOs
- Regulatory experts engaged in cell‑gene therapy approvals (e.g., former FDA / EMA review staff)
Databases
- ASGCT / Citeline “Gene, Cell, + RNA Therapy Landscape Report” data
- Clinical trial repositories (e.g., clinicaltrials.gov)
- Public gene & cell therapy pipeline tracking databases (e.g., from professional societies)
Magazines
- Nature Biotechnology
- BioCentury
- The Scientist
Journals
- Molecular Therapy (ASGCT’s journal)
- Stem Cell Reports
- Peer‑reviewed preprint studies, e.g., on CAR‑T modeling or AI in cell therapy
Newspapers
- Reuters for industry‐moving announcements (e.g., Takeda exiting cell therapy)
- Financial Times (e.g., acquisitions in cell therapy)
Associations
- American Society of Gene & Cell Therapy (ASGCT)
- International Society for Cell & Gene Therapy (ISCT)
- European Society of Gene & Cell Therapy (ESGCT)
Public Domain sources
- Preprint servers (e.g., arXiv) for computational / AI‑driven cell therapy research
- Conference proceedings / abstracts from society annual meetings (e.g., ISCT)
- Regulatory agency press releases (e.g., FDA, EMA)
- Corporate public filings or investor presentations by clinical‑stage cell therapy companies (e.g., Lineage Cell Therapeutics)
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI existing repository of information for last 8 years
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Cell Therapy Market is estimated to be valued at USD 3,109.6 Mn in 2026, and is expected to reach USD 5,983.1 Mn by 2033.
The CAGR of the Cell Therapy Market is projected to be 9.8% from 2026 to 2033.
Technological advancement for development of cell therapy and increasing number of regulatory approvals for cell therapy products are the major factor driving the growth of global cell therapy market.
High cost of cell therapies and stringent regulatory frameworks are the major factor hampering the growth of global cell therapy market.
In terms of therapy type, T-cells segment is estimated to dominate the market in 2026.
Bristol Myers Squibb Company, Amgen Inc., Novartis AG, Gilead Sciences, Inc., Johnson & Johnson Services, Inc., Allogene Therapeutics, Athersys, Inc., Orchard Therapeutics, JW Therapeutics Co., Ltd., Dendreon Pharmaceuticals LLC., Autolus Therapeutics, APAC Biotech, CORESTEM, Inc., BioCardia, Inc., JCR Pharmaceuticals Co., Ltd., Oxford Biomedica, CASI Pharmaceuticals Inc. are the major players.
North America is expected to lead the global cell therapy market.