
Diabetes Monitoring Devices Market Analysis & Forecast: 2026-2033
Global diabetes monitoring devices market size is expected to reach USD 26.12 Bn by 2033, from USD 14.66 Bn in 2026, exhibiting a compound annual growth rate (CAGR) of 8.6% during the forecast period.
Key Takeaways
- Based on Product Type, the Continuous Glucose Monitoring (CGM) Device segment is expected to account for 57.8% share of the market in 2026, due to advanced real-time tracking and growing user adoption.
- Based on Indication, the Type-II Diabetes segment is projected to hold the largest share of the market in 2026, due to its global prevalence and chronic nature.
- Based on End User, the Home Care Settings segment is projected to capture the highest share of the market in 2026, as patients prefer convenient, tech-enabled monitoring solutions.
- Based on Region, North America is projected to dominate the global diabetes monitoring devices market in 2026 with a 35.8% share. While, Asia Pacific region expected to be the fastest growing region.
Market Overview
The diabetes monitoring devices market demand continues to grow as the market is bifurcated into self-monitoring blood glucose devices and continuous glucose monitoring devices. These devices are used to track blood sugar levels throughout the day and night, enabling individuals to make informed choices about food, physical activity, and medication. Blood sugar levels can be effectively monitored and tracked using assistive medical technologies known as diabetes monitoring or blood glucose monitoring devices. These devices cater to patients with both type I and type II diabetes, further driving the demand across diverse patient demographics.
Current Events and their impact on the Diabetes Monitoring Devices Market
Current Event | Description and its Impact |
Regulatory Transformation and Coverage Expansion |
|
Global Population Screening and Early Detection Initiatives |
|
Role of Artificial Intelligence (AI) in Diabetes Monitoring Devices Market
Artificial Intelligence (AI) is transforming the Diabetes Monitoring Devices Market by enabling smarter, more personalized care. AI-powered systems analyze vast amounts of glucose data to detect patterns, predict blood sugar fluctuations, and offer real-time insights. This enhances decision-making for both patients and healthcare providers, improving treatment outcomes. Integration with mobile apps and cloud platforms allows seamless data sharing and remote monitoring, while machine learning algorithms continuously refine accuracy and responsiveness. As AI continues to evolve, it is expected to drive innovation in non-invasive monitoring, early diagnosis, and automated insulin delivery, making diabetes management more proactive and efficient.
For instance, in May 2025, IBM and Roche introduced an AI-powered app designed to predict blood sugar levels, marking a breakthrough in diabetes management. The app enables proactive care by analyzing patterns and offering personalized insights, helping users manage their condition more effectively and reduce complications through smarter, data-driven decision-making.
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Segmental Insights

Diabetes Monitoring Devices Market Insights, By Product Type: Continuous Glucose Monitoring (CGM) Devices lead with advanced real-time tracking and growing user adoption
In terms of product type, the Continuous Glucose Monitoring (CGM) devices segment is expected to hold 57.8% share in 2026. These devices provide real-time glucose readings, trend analysis, and customizable alerts, offering a more dynamic and responsive approach to diabetes management compared to traditional Self-Monitoring Blood Glucose (SMBG) devices. The surge in CGM adoption is fueled by growing patient awareness, rapid technological advancements, and seamless integration with insulin pumps and mobile health applications. Their ability to reduce hypoglycemic episodes and improve glycemic control makes CGMs a preferred choice among both patients and healthcare providers.
For instance, in August 2025, Abbott launched its advanced FreeStyle Libre 2 Plus glucose monitoring system in India, offering continuous glucose readings every minute and optional alarms for enhanced diabetes management. This next-gen device aims to empower users with real-time insights and improved control, reinforcing Abbott’s commitment to innovative healthcare solutions.
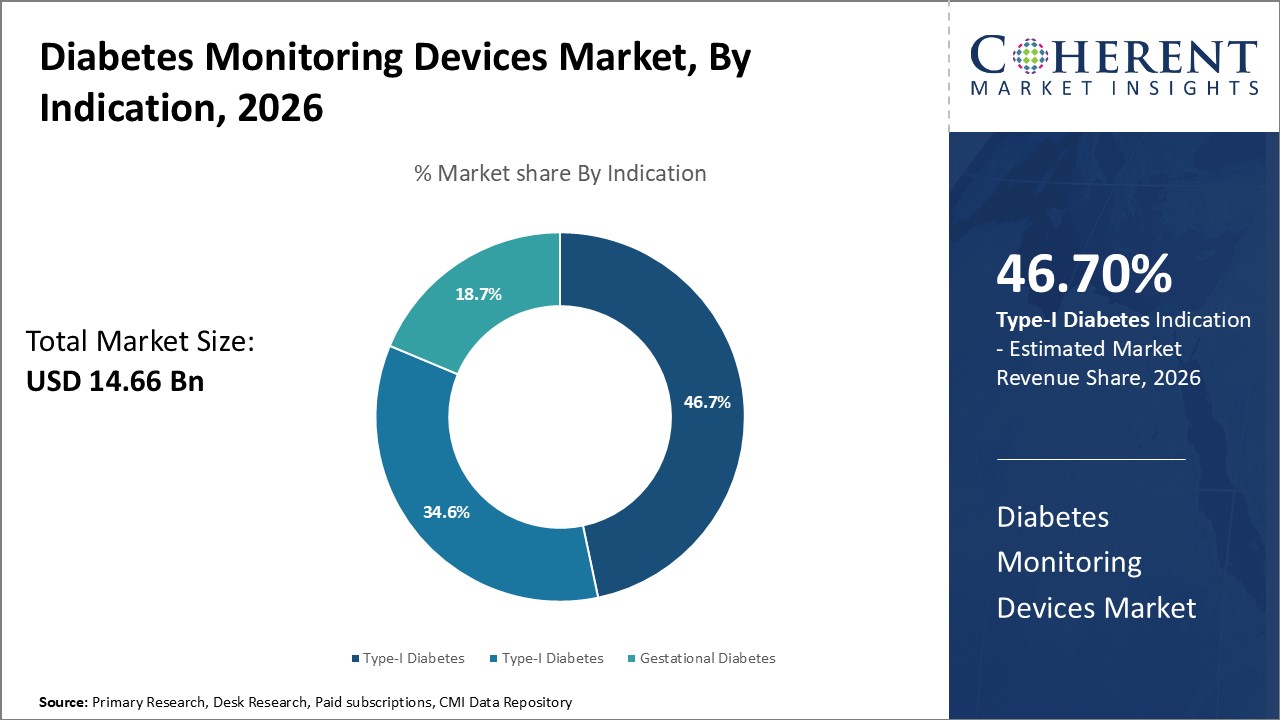
Diabetes Monitoring Devices Market Insights, By Indication: Type-II Diabetes drives demand due to its global prevalence and chronic nature.
In terms of indication, the Type-II diabetes segment is expected to contribute the largest share of the market in 2026. This is largely due to its widespread prevalence, particularly among aging populations and individuals with sedentary lifestyles. As Type-II Diabetes accounts for the majority of global diabetes cases, the demand for effective and accessible monitoring solutions is substantial. According the U.S. Centers of Disease Control and Prevention, more than 38 million Americans have diabetes (about 1 in 10), and about 91% to 95% of them have type 2 diabetes. The increasing focus on early detection, lifestyle management, and long-term disease control has amplified the need for reliable monitoring devices tailored to this demographic, making it a key driver of market growth.
For instance, in September 2025, Medtronic’s MiniMed 780G system received FDA clearance for use in Type 2 diabetes and integration with Abbott’s Instinct sensor. This milestone marks a significant step in automated insulin delivery, offering enhanced glucose management through real-time sensor data and expanding access to advanced diabetes care technologies.
Diabetes Monitoring Devices Market Insights, By End User: Home Care Settings dominate as patients prefer convenient, tech-enabled monitoring solutions.
In terms of end user, the Home Care Setting segment is projected to account for the highest share of the market in 2026, reflecting a broader shift toward decentralized and patient-centric healthcare. The convenience of monitoring blood glucose levels from home, coupled with the rise of telehealth services and remote patient monitoring, has made home-based solutions highly attractive. User-friendly interfaces, portable designs, and digital connectivity have empowered patients to take control of their health, reducing the need for frequent clinical visits. This trend is particularly impactful for chronic disease management, where continuous monitoring and timely interventions are crucial.
For instance, in July 2025, UMass Diabetes Center of Excellence released a comprehensive update on emerging diabetes technologies, highlighting advancements in continuous glucose monitoring, automated insulin delivery systems, and digital health tools. The center emphasizes improved patient outcomes, accessibility, and integration of smart devices, reflecting a growing shift toward personalized and tech-driven diabetes care.
Regional Insights

North America Diabetes Monitoring Devices Market Analysis & Trends
North America is expected to be the largest market for diabetes monitoring devices market during the forecast period, accounting for over 35.8% of the market share in 2026, due to the region's high diabetes prevalence, advanced healthcare infrastructure, and early adoption of innovative technologies like CGMs. Supportive reimbursement policies, growing awareness, and the presence of key market players further drive demand, making North America a dominant force in global diabetes care solutions.
For instance, in April 2026, Dexcom secured FDA clearance for its G7 continuous glucose monitoring system, now approved for 15-day wear. This advancement offers users extended sensor life, reducing replacements and enhancing convenience. The G7’s streamlined design and real-time data capabilities mark a significant step forward in personalized diabetes management and long-term glucose tracking.
Asia Pacific Diabetes Monitoring Devices Market Analysis & Trends
The Asia Pacific market is expected to be the fastest-growing market for diabetes monitoring devices market, with a CAGR of over 8.0% during the forecast period, due to rising diabetes prevalence, urbanization, and lifestyle changes. Increasing healthcare awareness, expanding middle-class populations, and supportive government initiatives are driving demand. Additionally, the adoption of digital health technologies and improved access to affordable monitoring devices are fueling market expansion across emerging economies in the region.
For instance, in September 2026, at the 3rd Borneo Diabetes Conference, BUZUD unveiled its AI-driven continuous glucose monitoring system, designed to enhance real-time diabetes management. The innovative device leverages artificial intelligence to deliver precise glucose readings, aiming to empower patients with smarter, more personalized care solutions in both clinical and home settings.
Diabetes Monitoring Devices Market Outlook Country-Wise
The U.S. Diabetes Monitoring Devices Market Trends
The U.S. Diabetes Monitoring Devices Market is booming due to high diabetes prevalence, advanced healthcare infrastructure, and strong consumer adoption of tech-driven solutions. Favorable reimbursement policies, rising awareness, and FDA approvals for innovative devices like CGMs and automated insulin systems further fuel demand, positioning the U.S. as a global leader in diabetes care.
For instance, in October 2026, Walmart planned to sell Abbott’s Lingo over-the-counter glucose monitor, expanding access to real-time metabolic tracking without a prescription. The move marks a major step in consumer health tech, enabling users to monitor glucose levels conveniently and proactively manage wellness through affordable, AI-powered insights available at retail locations nationwide.
China Diabetes Monitoring Devices Market Trends
China’s Diabetes Monitoring Devices Market is expanding due to a surge in Type 2 diabetes cases, driven by urbanization, aging population, and changing lifestyles. Increased health awareness, government support for digital health, and rising adoption of continuous glucose monitoring systems are fueling demand, making China a key player in the global diabetes care landscape.
For instance, in September 2026, Innovent Biologics received approval from China’s National Medical Products Administration (NMPA) for Mazdutide, a novel therapy for glycemic control in adults with Type 2 diabetes. This milestone marks a significant advancement in China’s diabetes treatment landscape, offering new options for effective and personalized disease management.
Market Report Scope
Diabetes Monitoring Devices Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 14.66 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 8.6% | 2033 Value Projection: | USD 26.12 Bn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | i-SENS, Inc., Ascensia Diabetes Care Holdings AG., Bayer AG, F. Hoffmann-La Roche Ltd, Johnson & Johnson Services, Inc., Medtronic, Dexcom, Abbott, Labiotech UG, ARKRAY, Inc., Cnoga, Sanofi, and Lifescan | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Global Diabetes Monitoring Devices Market Drivers
- Growing prevalence of diabetes: Growing prevalence of diabetes across the world is a major factor driving the growth of diabetes monitoring devices market. Diabetes is a chronic health condition where the body is unable to produce or properly use insulin which leads to increased blood sugar levels. Both type 1 and type 2 diabetes have seen significant rise in recent decades. According to the data by International Diabetes Federation, by 2050, projections show that 1 in 8 adults, approximately 853 million, will be living with diabetes, an increase of 46%. Such rising patient base of diabetes translates to increased demand for devices that help in monitoring blood glucose levels.
- Technological advancements in devices: Technological innovations have significantly advanced diabetes monitoring devices in recent years. Continuous glucose monitoring (CGM) systems that do not require finger pricks are becoming more mainstream, giving patients much greater convenience and insights into how food, exercise, and medications affect their blood sugar levels throughout the day and night. The adoption of CGM systems is expected to increase substantially over the next few years.
Global Diabetes Monitoring Devices Market Opportunities
- Advancing research in non-invasive glucose monitoring: Advancing research in non-invasive glucose monitoring presents a major opportunity in the diabetes monitoring devices market forecast. Traditionally reliant on finger pricks, diabetes care is shifting toward painless, continuous solutions. Technologies like ultrasound, infrared and impedance spectroscopy, thermophoresis, and glucose oxidase are being explored to measure glucose levels through the skin. These methods enable real-time, accurate readings without invasive procedures. For example, ultrasound-based monitors assess interstitial glucose painlessly, while spectroscopic tools analyze light absorption in tissues. Such innovations are set to revolutionize diabetes management, driving future growth and transforming patient experience in home and clinical settings.
- Integration of smartphones with glucose monitors: Integration of smartphones with glucose monitoring devices presents a major opportunity to enhance diabetes care and boost the diabetes monitoring devices market value. By linking monitors to mobile apps, patients can easily track blood sugar trends and share data with healthcare providers. This connectivity supports better self-management, enables personalized treatment plans, and may lead to improved clinical outcomes.
Global Diabetes Monitoring Devices Market Trends
- Production of user-friendly and portable diabetes monitoring devices: The production of user-friendly and portable diabetes monitoring devices is significantly driving diabetes monitoring devices market growth. These innovations empower patients with convenient, real-time glucose tracking, enhancing self-management and reducing hospital visits. Compact designs, smartphone integration, and painless sensors are boosting adoption, especially among tech-savvy and aging populations seeking personalized diabetes care solutions.
- Development of continuous glucose monitoring systems: The development of continuous glucose monitoring systems is revolutionizing diabetes care, fueling diabetes monitoring devices market research. These systems offer real-time data, predictive alerts, and seamless integration with digital platforms, enhancing patient outcomes and clinical decision-making. Their growing adoption reflects a shift toward proactive, tech-driven management, making CGMs a cornerstone of market innovation and expansion.
Analyst Opinion (Expert Opinion)
The diabetes monitoring devices market is transitioning from hardware-driven innovation to an ecosystem model defined by data integration, payer alignment, and clinical workflow ownership. Continuous glucose monitoring (CGM) has now achieved clinical validation beyond specialist use, studies show a ~22% increase in Time-In-Range (from 39.7% to 61.9%), underscoring its significant impact on glycemic control and complication reduction. However, adoption remains concentrated in high-income markets, with coverage gaps limiting access for most of the global diabetes population.
Competition is consolidating, led by platform players such as Abbott, Dexcom, and Medtronic, which combine sensor technology with data analytics and reimbursement networks. Incremental sensor accuracy improvements are no longer decisive; software-driven differentiation, including AI analytics, pump integration, and telehealth compatibility will shape long-term leadership. Reimbursement remains the pivotal determinant of uptake, as payers increasingly link device funding to proven outcome improvements and cost savings.
In emerging economies, affordability and infrastructure gaps demand localized models such as pay-as-you-go or government-backed programs. Ultimately, commercial success will hinge on health economics evidence, interoperable software ecosystems, and adaptive market access strategies, transforming diabetes monitoring from a device business into a digital health platform anchored in measurable patient outcomes and cost-effectiveness.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Recent Developments
- In September 2025, Sanofi announced a strategic partnership with Abbott to integrate its insulin products with Abbott’s FreeStyle Libre continuous glucose monitoring systems. This collaboration aims to streamline diabetes management by combining real-time glucose data with insulin delivery, enhancing patient outcomes and supporting personalized treatment across global markets.
- In September 2025, Roche received the CE mark for its Accu-Chek SmartGuide continuous glucose monitoring system, now integrated with the mySugr app. This approval paves the way for enhanced diabetes management across Europe, offering users real-time glucose tracking and personalized insights through a connected, user-friendly digital platform.
- In July 2025, the Government of Newfoundland and Labrador expanded coverage for continuous glucose monitoring (CGM) devices under the provincial drug program. Starting October 1, eligible residents with Type 1 diabetes will gain access to CGMs, enhancing diabetes management and reducing out-of-pocket costs for advanced monitoring technology.
- In January 2025, A research team from BITS Pilani Hyderabad has developed a non-invasive diabetes monitoring device, eliminating the need for painful finger pricks. The innovation uses advanced sensors to measure glucose levels through the skin, offering a more comfortable and accessible solution for diabetes management. The device is currently undergoing clinical validation.
Market Segmentation
- By Product Type (Revenue, USD Bn, 2021 - 2033)
- Self-Monitoring Blood Glucose Devices
- Continuous Glucose Monitoring Devices
- By Indication (Revenue, USD Bn, 2021 - 2033)
- Type-I Diabetes
- Type-II Diabetes
- Gestational Diabetes
- By End User (Revenue, USD Bn, 2021 - 2033)
- Hospitals
- Clinics
- Ambulatory Surgical Center
- Home Care Settings
- Others
- By Region (Revenue, USD Bn, 2021 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East & Africa
- GCC Countries
- Israel
- Rest of Middle East & Africa
- North America
- Top Companies in the Global Diabetes Monitoring Devices Market:
- i-SENS, Inc.
- Ascensia Diabetes Care Holdings AG.
- Bayer AG
- Hoffmann-La Roche Ltd
- Johnson & Johnson Services, Inc.
- Medtronic
- Dexcom
- Abbott
- Labiotech UG
- ARKRAY, Inc.
- Cnoga
- Sanofi
- Lifescan
Sources
Primary Research Interviews from the following stakeholders
Stakeholders
- Interviews with medical device manufacturers, healthcare professionals, endocrinologists, hospital procurement heads, diabetic care centers, and distributors across major regional markets.
Specific stakeholders
- Diabetologists and endocrinology specialists from leading hospitals (e.g., Apollo Hospitals, Mayo Clinic, Cleveland Clinic)
- Procurement managers and biomedical engineers at multispecialty hospitals and diagnostic labs
- Directors of diabetes management programs and chronic disease monitoring centers
- Clinical pharmacists and diabetes educators across North America, Europe, and Asia Pacific
- IT and data management heads involved in connected health and remote patient monitoring systems
- Product development and R&D leads at glucose monitoring device OEMs (e.g., CGM sensors, test strips, insulin delivery systems)
- Health insurance and reimbursement policy advisors involved in digital health and diabetic device coverage
- Medical distributors and supply chain managers for point-of-care diagnostic devices
Databases
- World Health Organization (WHO) Global Health Observatory (GHO)
- International Diabetes Federation (IDF) Diabetes Atlas
- World Bank Health Data Portal
- U.S. Food and Drug Administration (FDA) 510(k) and PMA databases
- European Medicines Agency (EMA) – Medical Devices Database
- Central Drugs Standard Control Organization (CDSCO), India
- Eurostat – Healthcare Equipment Statistics
- National Center for Health Statistics (NCHS), U.S.
- China National Medical Products Administration (NMPA)
- Japan Ministry of Health, Labour and Welfare (MHLW)
- Directorate General of Commercial Intelligence and Statistics (DGCIS), India
Magazines
- Diabetes Health
- Medical Device and Diagnostic Industry (MD+DI)
- MedTech Insight
- Healthcare Packaging
- Clinical Lab Products Magazine
- HealthTech Magazine
- DeviceMed
- Medgadget
Journals
- Diabetes Care (American Diabetes Association)
- Journal of Diabetes Science and Technology
- The Lancet Diabetes & Endocrinology
- Diabetologia (Springer)
- IEEE Journal of Biomedical and Health Informatics
- Journal of Medical Internet Research (JMIR)
- BioMedical Engineering Online
- Frontiers in Medical Technology
Newspapers
- The Wall Street Journal – Health & Pharmaceuticals
- The Economic Times – Healthcare and Medical Devices
- The Hindu Business Line – Healthcare & Life Sciences
- Financial Times – HealthTech and Devices Section
- Nikkei Asia – Medical Devices & Technology
- South China Morning Post – Healthcare Technology
Associations
- International Diabetes Federation (IDF)
- American Diabetes Association (ADA)
- European Association for the Study of Diabetes (EASD)
- Advanced Medical Technology Association (AdvaMed)
- Medical Device Manufacturers Association (MDMA)
- Asia Pacific Medical Technology Association (APACMed)
- Association of Indian Medical Device Industry (AiMeD)
- World Federation of Neurology (Endocrine and Metabolic Section)
Public Domain Sources
- World Health Organization (WHO) – Noncommunicable Diseases (NCD) Division
- U.S. Centers for Disease Control and Prevention (CDC) – Diabetes Surveillance System
- National Health Service (NHS) Digital – Diabetes Reports
- National Institute of Health (NIH) – NIDDK Publications
- Ministry of Health and Family Welfare (MoHFW), India
- European Commission – Medical Devices and eHealth Reports
- Health Canada – Medical Devices Active Licenses Database
- Reserve Bank of India (RBI) – Healthcare and Medical Devices Sector Reports
- NITI Aayog – HealthTech and Diagnostics Policy Framework
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of information for last 8 years
Definition: Blood glucose monitoring is the use of a glucose meter for testing the concentration of glucose in the blood. It is particularly important in diabetes management which includes a blood glucose test that is typically performed by piercing the skin to draw blood, and then by applying the blood to a chemically active disposable 'test-strip'.
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Diabetes Monitoring Devices Market is estimated to be valued at USD 14.66 Bn in 2026, and is expected to reach USD 26.12 Bn by 2033.
The key factors hampering the growth of the diabetes monitoring devices Market are high cost of innovative devices and lack of reimbursement in developing countries.
The major factors driving the growth of the market are growing prevalence of diabetes and technological advancements in devices.
The Continuous Glucose Monitoring Devices segment is the leading product type in the market.
The major players operating in the market are i-SENS, Inc., Ascensia Diabetes Care Holdings AG., Bayer AG, F. Hoffmann-La Roche Ltd, Johnson & Johnson Services, Inc., Medtronic, Dexcom, Abbott, Labiotech UG, ARKRAY, Inc., Cnoga, Sanofi, and Lifescan
North America leads the market.
The CAGR of the Diabetes Monitoring Devices Market is projected to be 8.6% from 2026 to 2033.