

Hepatitis Drugs Market Size and Trends: 2026-2033
Hepatitis drugs market is estimated to be valued at USD 26,380 Mn in 2026 and is expected to reach USD 32,906 Mn by 2033, exhibiting a compound annual growth rate (CAGR) of 3.2% from 2026 to 2033.
Key Takeaways
- Based on Drug Class, the Nucleotide Polymerase / NS5A Inhibitor Combinations segment is expected to lead the market with 25% share in 2026, due to its high efficacy in treating hepatitis C.
- Based on Disease Type, the Hepatitis C segment is expected to hold 50% share of the market in 2026, as the prevalence of Hepatitis C drives strong demand for targeted therapies.
- Based on Route of Administration, the Oral segment is projected to account for 70% share of the market in 2026, owing to patient preference for convenient, non-invasive treatment.
- Based on Distribution Channel, the Hospital Pharmacies segment is projected to account for 45% share of the market in 2026, due to the critical role of hospitals in administering antiviral therapies.
- Based on Region, North America is set to lead the hepatitis drugs market with 36% share in 2026. While, Asia Pacific is anticipated to be the fastest growing region.
Market Overview
Rising prevalence of hepatitis B and C infections across the globe is driving the demand for effective antiviral therapies. The market is expanding due to government initiatives for hepatitis screening and vaccination programs, as well as growing awareness of early diagnosis. New drugs like NS5A inhibitors, nucleotide polymerase inhibitors, and combination therapies have given patients more treatment options. Also, the growing preference for oral antiviral drugs because they are easier to take and make patients more likely to follow the treatment plan has helped the market grow.
Current Events and Its Impacts on the Hepatitis Drugs Market
Current Events | and its impact |
WHO Global Hepatitis Elimination Strategy and Policy Developments |
|
Geopolitical Tensions and Supply Chain Disruptions |
|
How is Product Innovation driving growth in the hepatitis drugs market?
- Novel Antiviral Combination Therapies: Development of NS5A inhibitors in combination with nucleotide polymerase inhibitors to improve rates of cure and reduce treatment duration.
- Oral Formulations: Launch of oral formulations that are convenient and easy to take, replacing injectable formulations and improving patient compliance.
- Targeted Therapies: Development of medications targeting particular hepatitis viruses (Hepatitis B, C, or dual infections) to enhance efficacy and reduce adverse reactions.
- Pediatric and Geriatric Formulations: Development of dosage forms for particular age groups, including children and the elderly.
- Extended-Release and Fixed-Dose Combinations: Novel formulations that simplify dosing regimens, improving patient compliance and outcomes.
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Segmental Insights
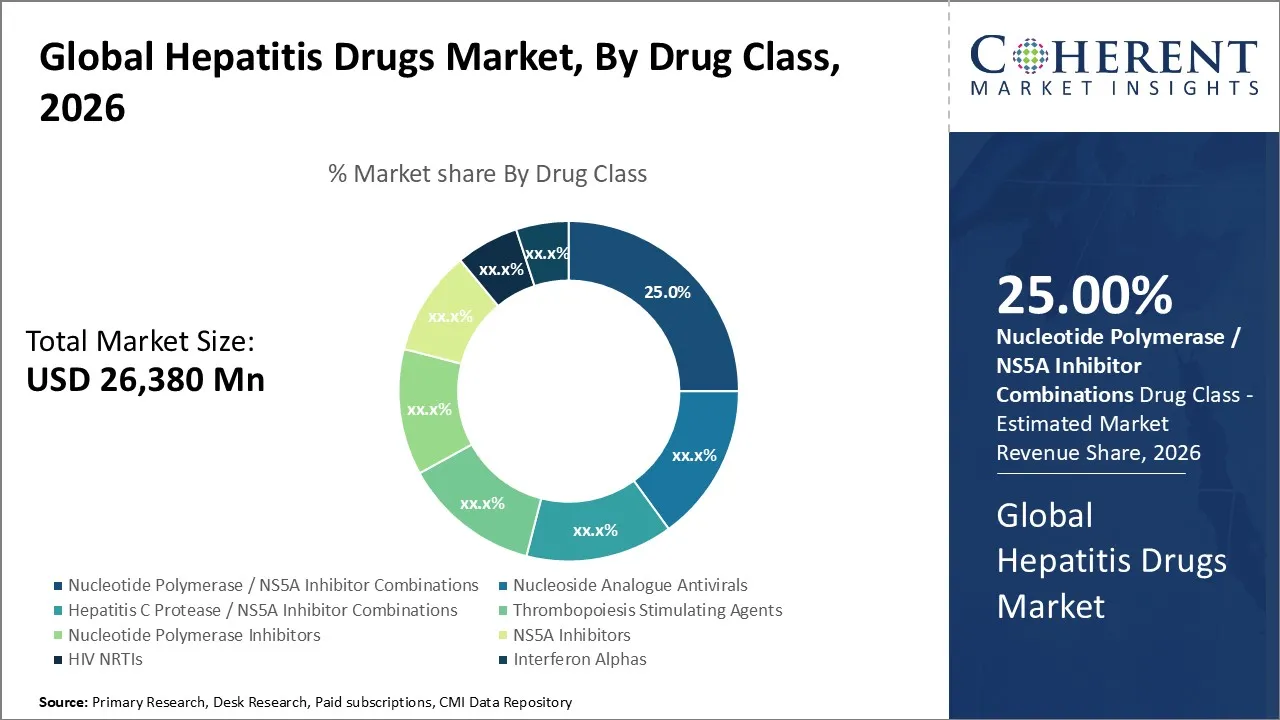
Hepatitis Drugs Market Insights, By Drug Class – Nucleotide Polymerase / NS5A Inhibitor Combinations lead due to high efficacy
On the basis of the drug class, the nucleotide polymerase/NS5A inhibitor combinations market is expected to have the largest market share of 25% in 2026, owing to its high effectiveness in the treatment of Hepatitis C. This is because these combinations offer a shorter treatment duration, higher cure rates, and fewer side effects than monotherapies.
For instance, in May 2025, Atea Pharmaceuticals announced positive Phase II results for its once-daily oral combination of bemnifosbuvir (a nucleotide NS5B polymerase inhibitor) and ruzasvir (an NS5A inhibitor) for the treatment of hepatitis C virus (HCV) infection.
Hepatitis Drugs Market Insights, By Disease Type – Hepatitis C dominates due to prevalence and targeted therapies
By disease type, the hepatitis C segment is projected to account for the largest market share of 50% in 2026, as the prevalence of Hepatitis C fuels the demand for specialized treatments. The rising screening campaigns, early diagnosis efforts, and focus on the eradication of the disease have also fueled the demand for the market. The chronic nature of Hepatitis C fuels the demand for specialized drug treatments.
For instance, in June 2025, the U.S. Food and Drug Administration (FDA) approved an expanded indication for MAVYRET® (glecaprevir/pibrentasvir) as the first and only direct-acting antiviral treatment approved to treat both acute and chronic infections of the hepatitis C virus (HCV) in adults and children aged three years and older without cirrhosis or with compensated cirrhosis.
Hepatitis Drugs Market Insights, By Route of Administration – Oral therapies preferred for convenience and compliance
By route of administration, the oral segment is expected to account for the highest market share of 70% in 2026, due to the patient preference for non-invasive treatment. The oral antiviral drugs have improved patient compliance and have reduced hospital visits compared to injectable antiviral drugs.
For instance, in May 2025, Atea Pharmaceuticals presented full results from its Phase 2 study of an eight‑week oral combination regimen of bemnifosbuvir (oral nucleotide NS5B polymerase inhibitor) and ruzasvir (oral NS5A inhibitor) at the EASL Congress 2025.
Hepatitis Drugs Market Insights, By Distribution Channel – Hospital pharmacies remain critical for therapy administration
Based on the distribution channel, the hospital pharmacies segment is expected to account for the largest market share of 45% in 2026, as hospitals play a crucial role in the administration of antiviral treatments. Hospitals offer professional supervision, proper dosing, and patient compliance, particularly in high-risk patients.
For instance, in August 2025, the Postgraduate Institute of Medical Education and Research (PGI) in Chandigarh, India, announced that it will start providing free comprehensive diagnostic services for viral hepatitis (A, B, C, and E) as part of the National Viral Hepatitis Control Program (NVHCP).
Regional Insights
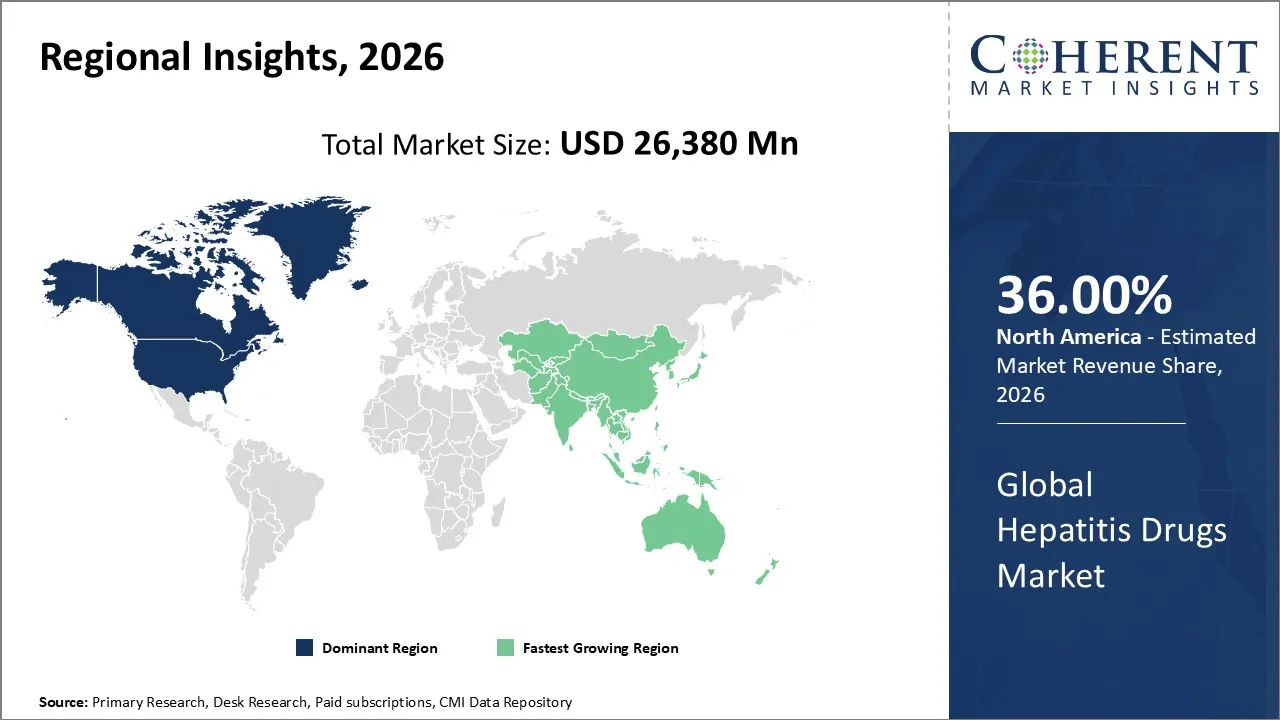
North America Hepatitis Drugs Market Analysis & Trends
North America is projected to lead the market for hepatitis medications in 2026, with a forecasted market share of 36%. The growth of the market in this region can be attributed to factors such as the high incidence of hepatitis infections, well-developed healthcare infrastructure, and a strong presence of major pharmaceutical companies.
For instance, in March 2025, the U.S. FDA approved the MAVYRET® (glecaprevir/pibrentasvir) treatment for both acute and chronic hepatitis C infections in adults and pediatric patients aged three years and older.
Asia Pacific Hepatitis Drugs Market Analysis & Trends
The Asia Pacific market is expected to be the fastest-growing due to increased health awareness, growing government efforts for the elimination of viral hepatitis, improved healthcare infrastructure, and the adoption of antiviral treatments. New domestic pharmaceutical firms are also increasing access to affordable and quality hepatitis treatment, thus fueling the growth of the market.
For instance,
Hepatitis Drugs Market Outlook for Key Countries
Is the U.S. hepatitis drugs market driven by innovation, screening programs, and early treatment adoption?
The hepatitis drugs market in the U.S. is still growing quickly. This is because of widespread screening programs, high healthcare spending, and the quick adoption of new antiviral therapies. Programs to get rid of hepatitis at the federal and state levels have sped up early diagnosis, which has led to a greater need for effective oral treatments for hepatitis B and C. The market is even stronger because there are big pharmaceutical companies there and the FDA keeps approving new drugs.
For instance, in December 2025, Mirum Pharmaceuticals acquired Bluejay Therapeutics for up to $820 million, obtaining worldwide rights to brevolitug, a late-stage monoclonal antibody candidate under development for the treatment of chronic hepatitis D, a serious type of viral hepatitis with no approved treatments available in the United States.
Is China’s large patient pool and government health focus accelerating hepatitis drug demand?
The hepatitis drugs market in China is growing rapidly due to the high prevalence of hepatitis B and increased government focus on controlling infectious diseases. The country’s vaccination programs, increased healthcare spending, and greater access to antiviral treatments are also encouraging higher diagnosis and treatment rates. Local pharmaceutical firms are also playing their part by developing affordable antiviral drugs for the large patient base.
For instance, in October 2025, China’s NMPA approved Pegbing, developed by Amoytop Biotech, as a functional cure-oriented therapy for chronic hepatitis B when used in combination with antiviral medication.
Market Report Scope
Hepatitis Drugs Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 26,380 Mn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 3.2% | 2033 Value Projection: | USD 32,906 Mn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | Merck & Co. Inc., Gilead Sciences Inc., AbbVie Inc., Bristol Myers Squibb Company, F. Hoffmann-La Roche Ltd., LAURUS Labs, Zydus Cadila, Hetero Healthcare Limited, GlaxoSmithKline PLC., and Cipla Inc. | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Hepatitis Drugs Market Driver
Rising prevalence of hepatitis B and C infections
The rising incidence of hepatitis B and hepatitis C infections in both developed and developing areas has been a key driving factor for the hepatitis drugs market. As per global health authorities, there are millions of people who are yet to be diagnosed and treated, thereby leading to continuous demand for antiviral drugs. The rising awareness programs and early diagnosis have led to increased treatment rates. Moreover, the chronic nature of hepatitis infections often leads to combination therapies, thereby driving continuous demand for hepatitis drugs.
Hepatitis Drugs Market Opportunity
Development and launch of innovative oral and combination therapies
The market for hepatitis drugs offers great opportunities in the development and launch of new and innovative oral drugs and fixed-dose combinations. The pharmaceutical industry is working towards shorter treatment regimens, higher cure rates, and fewer side effects to improve patient compliance. There is also a growing opportunity in the development of drugs for unmet needs such as functional cures for hepatitis B and hepatitis D. In addition, increased access to generic antiviral drugs in developing countries and increased government support for hepatitis elimination programs are expected to create great opportunities in the market.
Analyst Opinion (Expert Opinion)
- The market for hepatitis medications is at a crossroads, transitioning from volume-based antiviral medication distribution to outcome-based therapeutic development. Although efficacious treatments exist, hepatitis B and C continue to be substantially underdiagnosed and undertreated. Based on global health projections, more than 350 million people worldwide are estimated to be living with chronic hepatitis B and C infection together, although fewer than 25% are even aware of their status, and an even smaller percentage have received appropriate treatment. This diagnostic-treatment disconnect has remained both a weakness and a demand driver for hepatitis medications.
- By contrast, hepatitis B is the most strategic opportunity and the biggest scientific challenge in the market. The existing nucleos(t)ide analogs are very effective at inhibiting viral replication, but less than 5-7% of patients receiving these treatments have achieved functional cure, making it necessary to treat the disease for life. This has led to a paradoxical market situation where there is stable recurring demand in the market today, but increasing pressure for a cure tomorrow.
- Regionally, conviction among analysts is strongest in markets with policy-driven targets for the elimination of the disease, particularly in the U.S., Europe, and Asia-Pacific. Nations that have already removed fibrosis-stage restrictions and incorporated hepatitis drugs into public reimbursement schemes have shown higher treatment initiation rates.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Top Strategies Followed by Hepatitis Drugs Market Players
- Established pharmaceutical players prioritize pipeline innovation and lifecycle management. Leading companies like Gilead Sciences, AbbVie, Bristol Myers Squibb, and GSK, which have been allocating 15-25% of their annual revenues to R&D, with hepatitis being one of the major areas of focus. The companies are actively working on next-generation antivirals, fixed-dose oral combinations, and functional cure strategies for hepatitis B, which include capsid inhibitors, antisense oligonucleotides, and immune-modulating therapies.
- Mid-sized companies compete through differentiation and regional penetration. Mid-tier biopharma companies target cost-effective oral treatments, regional approvals, and collaborations with public health systems, especially in the Asia-Pacific and Latin American regions. Mid-tier companies usually license candidates in late-stage development, target generic or branded-generic antivirals, and collaborate with governments to distribute drugs via national hepatitis elimination programs. Pricing and volume-based hospital tenders are key to their strategies.
- Smaller players and biotechs target unmet clinical niches. Emerging companies target high unmet need segments such as hepatitis B functional cure, hepatitis D, and treatment-resistant patients. Emerging companies use platform technologies such as RNA interference, monoclonal antibodies, and therapeutic vaccines, in contrast to incremental antivirals. Collaborations with large pharmaceutical companies, academic institutions, and research programs supported by governments are critical.
Emerging Startups in the Hepatitis Drugs Market
- Startups advancing functional cure approaches for hepatitis B are gaining attention. Biotech companies such as Vir Biotechnology, Arbutus Biopharma, and Assembly Biosciences are developing immune-based therapies, capsid assembly modulators, and RNA-targeting agents aimed at achieving sustained viral suppression or functional cure. These approaches move beyond lifelong viral suppression and could redefine long-term treatment paradigms.
- RNA-based and antibody-driven innovation is reshaping early-stage pipelines. A number of startups are using siRNA, antisense oligonucleotides, and monoclonal antibodies to focus on the viral replication or entry process. These kinds of technologies make it possible to target things very precisely with very little harm to the body as a whole. This makes the startups good candidates for acquisition or partnership by big pharmaceutical companies.
- Some new companies are working on simpler oral treatment plans and cheaper formulations that are good for developing countries. These plans fit with the WHO's plans to get rid of hepatitis. These kinds of businesses might work with NGOs, health organizations, and generic drug makers to reach more places in developing countries.
Hepatitis Drugs Industry News
- In January 2026, GSK announced positive Phase III results for bepirovirsen, an investigational antisense oligonucleotide therapy for chronic hepatitis B (CHB). Trials (B-Well 1 & 2) demonstrated significant functional cure potential. GSK plans global regulatory submissions based on these data.
- In May 2025, Gilead Sciences announced it would present new information at the European Association for the Study of the Liver (EASL) Congress 2025, including information about experimental treatments like bulevirtide (for hepatitis D).
- In December 2025, Mirum Pharmaceuticals announced it will acquire acquire Bluejay Therapeutics for up to $820 million. This would give Mirum global rights to brelovitug, a late-stage monoclonal antibody drug that targets chronic hepatitis D, a rare and severe form of viral hepatitis that has no approved treatments.
Market Segmentation
- Drug Class Insights (Revenue, USD Mn, 2026 - 2033)
- Interferon Alphas
- HIV NRTIs
- Nucleotide Polymerase / NS5A Inhibitor Combinations
- Hepatitis C Protease / NS5A Inhibitor Combinations
- NS5A Inhibitors
- Nucleotide Polymerase Inhibitors
- Nucleoside Analogue Antivirals
- Thrombopoiesis Stimulating Agents
- Disease Type Insights (Revenue, USD Mn, 2026 - 2033)
- Hepatitis B
- Hepatitis C
- Others
- Route of Administration Insights (Revenue, USD Mn, 2026 - 2033)
- Oral
- Injection
- Distribution Channel Insights (Revenue, USD Mn, 2026 - 2033)
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Regional Insights (Revenue, USD Mn, 2026 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC Countries
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
- North America
- Key Players Insights
- Merck & Co. Inc.
- Gilead Sciences Inc.
- AbbVie Inc.
- Bristol Myers Squibb Company
- Hoffmann-La Roche Ltd.
- LAURUS Labs, Zydus Cadila
- Hetero Healthcare Limited
- GlaxoSmithKline PLC.
- Cipla Inc
Sources
Primary Research Interviews
- Pharmaceutical Manufacturers & Brand Managers (Merck, Gilead, AbbVie, Roche, etc.
- Clinical Researchers & Medical Experts in Hepatology
- Hospital Pharmacy Heads & Procurement Managers
- Doctors & Specialists Treating Hepatitis B & C Patients
- Regulatory Affairs Experts & Market Access Managers
- Pharma Distributors & Wholesalers
- Patients & Patient Advocacy Groups
- Others
Databases
- U.S. FDA Drug Database
- ClinicalTrials.gov
- European Medicines Agency (EMA) Database
- World Health Organization (WHO) Global Health Observatory
- CDC (Centers for Disease Control and Prevention) Data
- Statista
- PubMed Clinical Data
- Others
Magazines
- Pharmaceutical Executive
- FiercePharma
- Pharma Times
- Pharmaceutical Technology
- Drug Development & Delivery
- Others
Journals
- Journal of Hepatology
- Liver International
- Clinical Gastroenterology and Hepatology
- Hepatology
- World Journal of Gastroenterology
- Others
Newspapers
- The Wall Street Journal (Health & Pharma Section)
- Financial Times (Healthcare Section)
- New York Times (Health Section)
- Reuters (Healthcare & Pharma News)
- Bloomberg News (Pharma & Life Sciences)
- Others
Associations
- American Association for the Study of Liver Diseases (AASLD)
- European Association for the Study of the Liver (EASL)
- World Hepatitis Alliance (WHA)
- National Organization for Rare Disorders (NORD) – Hepatitis Related
- Others
Public Domain Sources
- U.S. FDA Publications & Drug Approvals
- CDC Hepatitis Surveillance Reports
- WHO Global Hepatitis Reports
- National Institutes of Health (NIH) Clinical Studies Reports
- World Bank – Health & Hepatitis Indicators
- Others
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of Information for the Last 8 Years
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Hepatitis Drugs Market is estimated to be valued at USD 26,380 Mn in 2026, and is expected to reach USD 32,906 Mn by 2033.
The CAGR of the Hepatitis Drugs Market is projected to be 3.2% from 2026 to 2033.
Key growth drivers include rising treatment adoption due to improved early diagnosis and screening programs, increasing prevalence of hepatitis infections globally, expanding access to direct-acting antiviral medications, and innovation in biologic and personalized medicines.
Major restraints include high costs of innovative drug therapies limiting access in low-income regions, inadequate healthcare infrastructure in some markets, and challenges in diagnosing patients early enough for effective treatment initiation.
In terms of drug class, Nucleotide Polymerase / NS5A Inhibitor Combinations segment is estimated to dominate the market in 2026.
Major pharmaceutical companies in the hepatitis drugs space include Merck & Co. Inc., Gilead Sciences Inc., AbbVie Inc., Bristol Myers Squibb Company, F. Hoffmann-La Roche Ltd., LAURUS Labs, Zydus Cadila, Hetero Healthcare Limited, GlaxoSmithKline PLC., and Cipla Inc. and several others developing innovative therapies and antiviral agents.
North America is expected to remain a leading regional market due to advanced healthcare infrastructure, high disease awareness, and strong treatment uptake, while Asia-Pacific is seen as a rapidly growing region driven by large patient populations and expanding treatment access.