

Pemetrexed Market Size and Trends: 2026-2033
Pemetrexed market is estimated to be valued at USD 2,494.2 Mn in 2026 and is expected to reach USD 2,907.6 Mn by 2033, exhibiting a compound annual growth rate (CAGR) of 2.2% from 2026 to 2033.
Key Takeaways
- Based on Strength, the 500 mg segment is expected to lead the market with approximately 62% share in 2026.
- Based on Distribution Channel, the Hospital Pharmacies segment is expected to hold the largest share of approximately 60% in 2026.
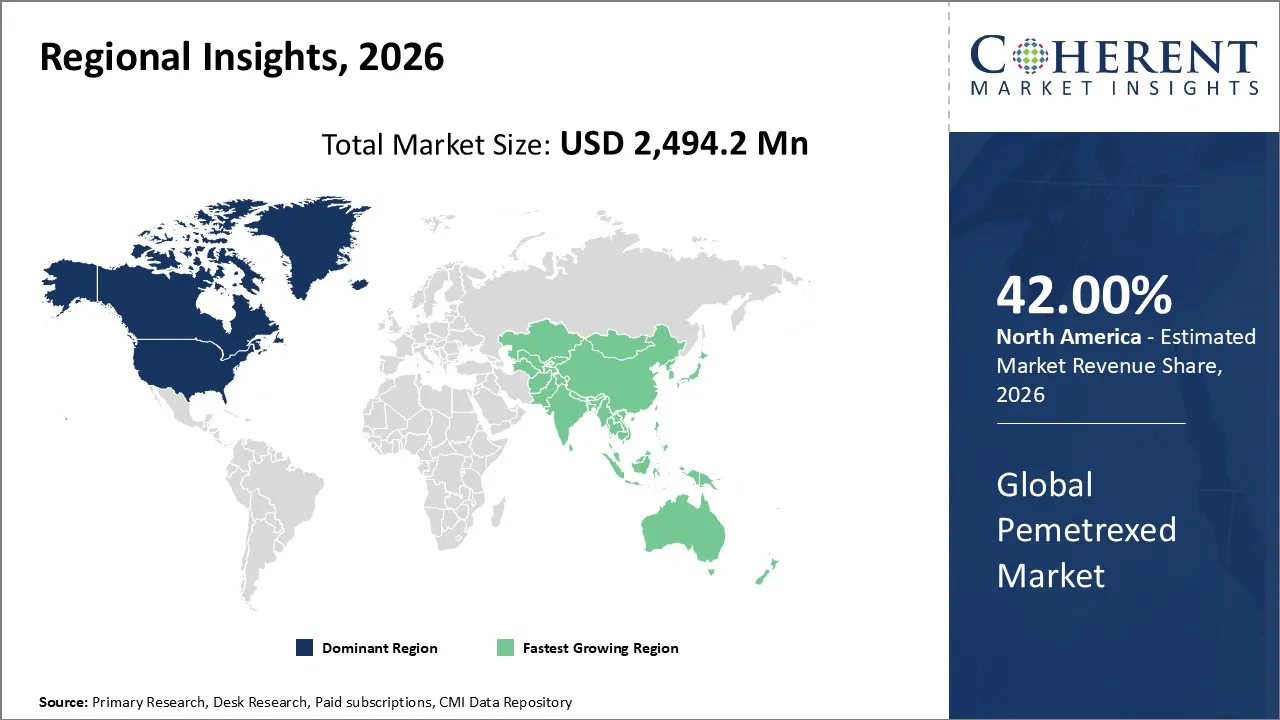
- Based on Region, North America is set to lead the pemetrexed market with 42% share in 2026. While, Asia Pacific is anticipated to be the fastest growing region.
Market Overview
Increase in incidence of lung cancer and malignant pleural mesothelioma worldwide is one of the major factor fueling demand for chemotherapy drugs involving pemetrexed. Pemetrexed, used as part of combination chemotherapy, is commonly applied in chemotherapy treatment of non-small cell lung cancer, which accounts for a large share of worldwide cancer incidence rates. Increasing general public awareness of the importance of early diagnosis of cancers, along with improved access to oncology treatment services, also contributes to steady growth in chemotherapy treatment of cancer.
Current Events and Its Impacts on the Pemetrexed Market
Current Events | and its impact |
Regulatory and Patent Landscape Changes |
|
Geopolitical Trade Tensions and Supply Chain Disruptions |
|
How is product innovation driving growth in the pemetrexed market?
- Advanced Combination Regimens: Adding pemetrexed with checkpoint inhibitors of immune systems, like PD-1/PD-L1, along with platinum-based chemotherapeutic agents, has resulted in enhanced survival rates in non-small cell lung cancer, thus increasing its usage.
- Ready-to-Use (RTU) Formulations: Preparation of premixed or ready-to-dilute injectables for immediate use can decrease the preparation time, avoid dosing confusion, and increase patient safety during hospital-based oncological
- Generic Product Launches: The launch of cost-effective generic products, especially after patent expiry, has become one factor increasing access in emerging markets, thereby increasing treatment penetration rates.
- Improved Drug Stability & Packaging: Advances in vial stability, lyophilized powder, and more effective packaging ensure better shelf life of the drug and safe transportation of the drug.
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Segmental Insights

Pemetrexed Market Insights, By Strength – 500 mg dominates due to standard oncology dosing practices
Based on strength, the 500 mg segment is likely to generate the highest level of market share, considered to be 62% of the total market share in 2026. Pemetrexed 500 mg vials are generally employed in the treatment of non-small cell lung cancer and malignant pleural mesothelioma with platinum-based regimens in combination with immunotherapy.
For instance, in April 2024, Amneal Pharmaceuticals launched PEMRYDI RTU, a pemetrexed formulation in ready-to-use injectables, including the 500 mg/50 mL vial preparation, which does not require reconstitution, dilution, or refrigeration.
Pemetrexed Market Insights, By Distribution Channel – Hospital pharmacies lead due to institutional chemotherapy administration
Based on distribution channel, the hospital pharmacies segment is expected to contribute the highest market share of around 60% in 2026. As pemetrexed is administered intravenously and under strict medical supervision, a significant number of treatments take place in the oncology departments of hospitals and specialty cancer centers. Hospital pharmacies manage the procurement, storage, preparation, and dispensing of drugs according to regulatory standards for cytotoxic medications.
For instance, Amneal Pharmaceuticals and Shilpa Medicare jointly announced the commercial launch of "PEMRI DI RTU," the first "Ready to Use" Pemetrexed Injection that does not require reconstitution, dilution, and refrigeration.
Regional Insights
North America Pemetrexed Market Analysis & Trends
North America is poised to account for the largest share of 42% in the pemetrexed market in 2026. Advanced healthcare infrastructure, a high prevalence of lung cancer and malignant pleural mesothelioma, strong reimbursement policies, and early adoption of chemotherapy treatments are some of the factors contributing to market growth in the region. Demand from hospital pharmacies and oncology centers remains high as pemetrexed continues to be a standard chemotherapy drug used in the treatment regimens.
For instance, in January 2025, Johnson & Johnson announced that Health Canada had given its Notice of Compliance (NOC) to RYBREVANT (amivantamab) in combination with carboplatin and pemetrexed to treat patients with locally advanced or metastatic non-small cell lung cancer (NSCLC) expressing certain EGFR mutations and who had previously received therapy.
Asia Pacific Pemetrexed Market Analysis & Trends
The Asia Pacific market is expected to be the fastest-growing market for pemetrexed because of the increasing rate of cancer incidence, investment in health infrastructure, and increasing access to chemotherapy and cancer awareness regarding early detection of cancer. The availability of generics of pemetrexed at a lower cost is driving the market in emerging countries such as China, India, and Japan.
For instance, in January 2026, Shilpa Medicare highlighted the growing use of PEMRYDI RTU® in hospital pharmacies across Asia Pacific, emphasizing its ready-to-use formulation that reduces preparation time and supports safe, efficient administration of chemotherapy in institutional settings.
Pemetrexed Market Outlook for Key Countries
Is the U.S. pemetrexed market benefitting from expanded institutional adoption and formulation innovations?
The United States pemetrexed market is still rising due to an increase in cancer prevalence, well-developed healthcare infrastructure, and rising institutional use of chemotherapy. It has remained a consistent drug in chemotherapy regimens used to treat NSCLC and malignant pleural mesothelioma, with an established support base generated from hospital pharmacy networks.
For instance, in April 2024, Amneal Pharmaceuticals launched PEMRYDI RTU® in the U.S. — a ready‑to‑use pemetrexed injection available in 500 mg and 100 mg strengths that eliminates reconstitution and refrigeration requirements.
Is China’s healthcare expansion driving pemetrexed adoption?
China’s rapid expansion of healthcare infrastructure and growing access to oncology treatments are driving increased adoption of pemetrexed therapies. The government’s focus on improving cancer diagnostics and treatment availability, along with expanded reimbursement coverage, supports institutional procurement of chemotherapy drugs and broadens the patient base that can access pemetrexed.
For instance, in June 2024, China’s National Medical Products Administration (NMPA) approved AstraZeneca’s Tagrisso (osimertinib) in combination with pemetrexed and platinum‑based chemotherapy.
Market Report Scope
Pemetrexed Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 2,494.2 Mn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 2.2% | 2033 Value Projection: | USD 2,907.6 Mn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | Eli Lilly and Company, Stada Arzneimittel AG, Eagle Pharmaceuticals, Inc, Fresenius Kabi USA, Teva Pharmaceuticals USA, Inc, Biocon, Pfizer Inc., Apotex Inc, Dr. Reddy’s Laboratories Ltd, Cadila Pharmaceuticals., Accord Healthcare, Accure Labs Pvt. Ltd, Shanghai Henlius Biotech, Inc., Janssen Global Services, LLC, and Checkpoint Therapeutics, Inc. | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Pemetrexed Market Driver
Increasing prevalence of lung cancer and mesothelioma
The increasing prevalence of NSCLC and malignant pleural mesothelioma, especially in North America and the Asia Pacific, propels the demand for pemetrexed. Since the medication represents a first-line chemotherapeutic agent in standard treatment regimen, hospital pharmacies and oncology centers are also posting regular growth in consumption. The growing awareness about early detection of cancer and better diagnostic skills further enhances the adoption of pemetrexed in clinical practice.
Pemetrexed Market Opportunity
Introduction of ready‑to‑use formulations and generic alternatives
The ready-to-use pemetrexed injections offer growth potential, simplifying the hospital pharmacy process by eliminating major steps of reconstitution and refrigeration. Besides this, the increasing availability of generic pemetrexed formulations in major markets such as the U.S., China, and Europe ensures cost-effective options for healthcare providers, thus improving access to treatment and driving market growth. There is also an opportunity to integrate pemetrexed into combination therapies with targeted agents, increasing its usage across diverse patient populations.
Analyst Opinion (Expert Opinion)
- The rapidly evolving pemetrexed market is driven by the established role in first-line treatment regimens for non-small cell lung cancer and malignant pleural mesothelioma. Strong adoption into hospital and oncology pharmacy channels, especially with the introduction of ready-to-use formulations, streamlines drug preparation and reduces handling errors.
- Geographically, North America continues to lead due to early adoption and comprehensive reimbursement coverage, while Asia Pacific, with China as a forerunner in that region, is a formidable growth for building clinical evidence. The approvals for combination therapies are expected to encourage hospitals towards stocking higher inventory levels to meet the surging demand within China.
- Overall, pemetrexed’s market trajectory is being actively shaped by formulation innovation, hospital pharmacy workflow optimization, and integration into combination regimens with targeted therapies. The combination of operational efficiency and clinical flexibility positions pemetrexed as a backbone of modern oncology, making it unlikely that any emerging chemotherapeutic agent will unseat it in the near term, particularly in institutional settings where reliable, versatile treatment options are essential.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Top Strategies Followed by Pemetrexed Market Players
- Established pharmaceutical companies focus on formulation innovation and regulatory compliance. Leading companies such as Eli Lilly, Merck & Co., and Amneal Pharma who are putting significant efforts into the development of ready-to-use injections, new vials, and combination therapy. They are mainly focused on clinical trials as well as post-marketing surveillance for the drugs. Partnering with hospitals as well as oncology networks is common for the accessibility of the drugs.
- Mid-sized players compete on affordability and supply chain efficiency. These firms use low-cost manufacturing processes, local production facilities, and bulk procurement of raw materials. They offer generic versions of pemetrexed, thereby enhancing market access-particularly in regions with tight hospital procurement budgets-without compromising on quality or regulatory standards.
- Smaller pharmaceutical firms specialize in niche segments. Some focus on biosimilar development, packaging innovations, or region-specific distribution strategies. These companies often use digital platforms for marketing and hospital engagement or form partnerships with specialty pharmacies to reach targeted patient populations. Collaboration with local research institutions or oncology associations helps enhance credibility and expand reach.
Emerging Startups in the Pemetrexed Market
- Innovation in drug delivery and formulation is a primary focus. Startups are exploring pre-filled syringes, ready-to-use formats, and temperature-stable formulations to improve hospital workflow and patient safety. Successful adoption of these innovations could reshape chemotherapy administration standards.
- Sustainability and cost efficiency are increasingly considered. Some emerging companies aim to optimize manufacturing to reduce waste and energy consumption or develop cost-effective generic versions that maintain quality standards while improving affordability for healthcare systems.
- Targeting underserved hospital and regional markets is another key strategy. Startups provide tailored distribution solutions for smaller clinics or hospitals in emerging markets, forming partnerships with local oncology networks to ensure consistent drug availability and support adherence to treatment protocols.
Pemetrexed Industry News
- In December 2024, Eli Lilly announced the launch of a new formulation of pemetrexed for advanced lung cancer treatment, highlighting continued innovation for its flagship chemotherapy product.
- In June 2024, The European Medicines Agency (EMA) announced the withdrawal of the marketing authorization for Pemetrexed Krka in the EU, indicating shifts in product availability among generic players.
- In April 2024, Amneal Pharmaceuticals, in partnership with Shilpa Medicare, launched PEMRYDI RTU®, a ready‑to‑use pemetrexed injection in the U.S. market
Market Segmentation
- Strength Insights (Revenue, USD Mn, 2026 - 2033)
- 100mg
- 500mg
- Distribution Channel Insights (Revenue, USD Mn, 2026 - 2033)
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Regional Insights (Revenue, USD Mn, 2026 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC Countries
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
- North America
- Key Players Insights
- Eli Lilly and Company
- Stada Arzneimittel AG
- Eagle Pharmaceuticals, Inc
- Fresenius Kabi USA
- Teva Pharmaceuticals USA, Inc
- Biocon
- Pfizer Inc.
- Apotex Inc
- Reddy’s Laboratories Ltd
- Cadila Pharmaceuticals.
- Accord Healthcare
- Accure Labs Pvt. Ltd
- Shanghai Henlius Biotech, Inc.
- Janssen Global Services, LLC
- Checkpoint Therapeutics, Inc.
Sources
Primary Research Interviews
- Oncology & Hematology Physicians
- Hospital Pharmacists & Oncology Pharmacy Managers
- Pharmaceutical Company Brand Managers (Pemetrexed & Chemotherapy Portfolios)
- Clinical Trial Coordinators & Research Scientists
- Oncology Treatment Centers & Hospital Administrators
- Regulatory Affairs Experts
- Medical Supply Chain & Distribution Managers
- Others
Databases
- U.S. Food and Drug Administration (FDA) Database
- European Medicines Agency (EMA) Database
- ClinicalTrials.gov
- PubMed
- PharmaProjects / Informa Pharma Intelligence
- Elsevier Pharma Database
- Others
Magazines
- Pharmaceutical Executive
- PharmaTimes
- Oncology Times
- Fierce Pharma
- Pharmaceutical Technology
- Others
Journals
- Journal of Clinical Oncology
- The Lancet Oncology
- Cancer Chemotherapy and Pharmacology
- Expert Opinion on Pharmacotherapy
- International Journal of Oncology
- Others
Newspapers
- The Wall Street Journal (Healthcare Section)
- Financial Times (Pharma & Healthcare Section)
- Reuters Health
- Bloomberg News (Healthcare & Pharma)
- The New York Times (Health Section)
- Others
Associations
- American Society of Clinical Oncology (ASCO)
- International Association for the Study of Lung Cancer (IASLC)
- Oncology Nursing Society (ONS)
- Pharmaceutical Research and Manufacturers of America (PhRMA)
- European Society for Medical Oncology (ESMO)
- Others
Public Domain Sources
- FDA Drug Approvals & Labeling Documents
- EMA Public Assessment Reports
- National Cancer Institute (NCI) Publications & Reports
- World Health Organization (WHO) Oncology Reports
- Centers for Disease Control and Prevention (CDC) Cancer Statistics
- Others
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of Information for the Last 8 Years
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Pemetrexed Market is estimated to be valued at USD 2,494.2 Mn in 2026, and is expected to reach USD 2,907.6 Mn by 2033.
The CAGR of the Pemetrexed Market is projected to be 2.2% from 2026 to 2033.
Increasing prevalence of lung cancer and mesothelioma, expansion of hospital and oncology pharmacy networks, and adoption of guideline-based chemotherapy regimens are the primary factors driving market growth.
High cost of treatment, availability of alternative chemotherapy drugs, and regulatory hurdles in certain regions are some of the key factors restraining market growth.
The 500 mg segment is expected to dominate the market in 2026 due to its standard dosing preference and widespread clinical usage.
North America is projected to lead the Pemetrexed Market in 2026, due to advanced healthcare infrastructure, high adoption of chemotherapy regimens, and early access to new formulations.
Eli Lilly and Company, Dr. Reddy’s Laboratories Ltd., Amneal Pharmaceuticals, Teva Pharmaceuticals, Pfizer Inc., Accord Healthcare, Biocon, Stada Arzneimittel AG, Cadila Pharmaceuticals, Eagle Pharmaceuticals, Fresenius Kabi USA, Shanghai Henlius Biotech, Janssen Global Services, and Checkpoint Therapeutics, Inc. are among the key players in the market.