
Poly Adenosine Diphosphate-Ribose Polymerase Market Size and Share Analysis- 2026 To 2033
The Poly Adenosine Diphosphate-Ribose Polymerase Market size is anticipated to grow at a CAGR of 9.2%, with USD 8.57 Bn in 2026, and is expected to reach USD 15.87 Bn in 2033. The primary drivers are largely defined by the rising prevalence of ovarian, breast, prostate, and pancreatic cancers, increasing adoption of targeted cancer therapies, growing use of biomarker-based patient selection, and expanding clinical applications of PARP inhibitors. In July 2026, the U.S. FDA accepted for Priority Review Pfizer’s supplemental application for Talzenna (talazoparib) + Xtandi (enzalutamide) for men with HRR gene-mutated metastatic castration-sensitive prostate cancer (mCSPC).
Key Takeaways
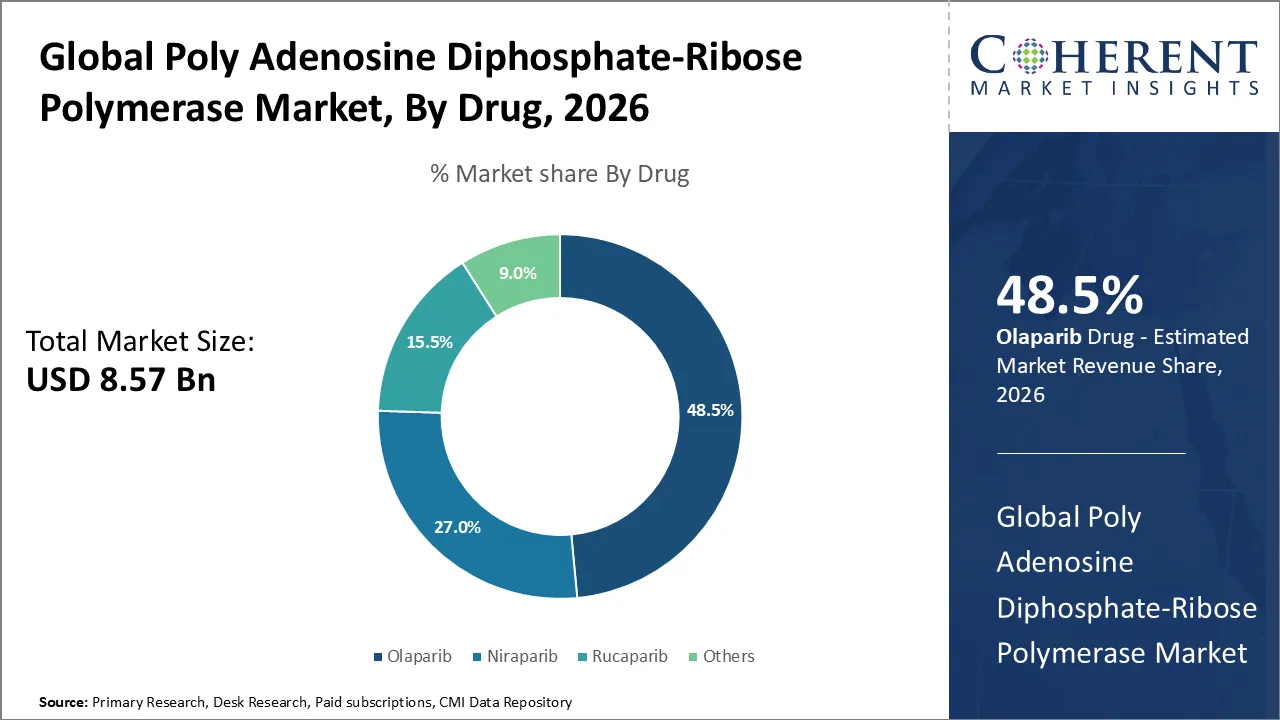
- The olaparib segment is estimated to dominate the market with 48.5% in 2026. The segment’s growth is supported by the broad use of Lynparza (olaparib) across ovarian, breast, pancreatic, and prostate cancers, strong physician familiarity, and its established position in BRCA- and HRR-associated tumors. AstraZeneca said U.S. sales of Lynparza (olaparib) were USD 1.434 Bn in 2025, up 8% from USD 1.332 Bn in 2024, driven by market-share gains across ovarian, breast and prostate cancer indications.
- Ovarian cancer segment is expected to lead with 52.0% in 2026. The segment’s growth is attributed to the established use of PARP inhibitors in first-line and recurrent ovarian cancer maintenance therapy, particularly for patients with BRCA mutation and homologous recombination deficiency. The American Cancer Society estimates that in 2026 there will be about 21,010 new cases of ovarian cancer and 12,450 deaths in the U.S. This will continue to drive the demand for targeted treatment approaches.
- Hospital pharmacies segment is anticipated to have maximum distribution channel with 58.0% in 2026. The specialist-led nature of PARP inhibitor prescribing, treatment initiation within oncology centers, the need for close monitoring and the concentration of advanced cancer care in the hospital and cancer-center settings support the leadership of the segment. Current approvals of additional indications for PARP inhibitors (including the recent US approvals for Rubraca [rucaparib] and Akeega [niraparib plus abiraterone acetate] in prostate cancer) are likely to continue to flow through hospital-based oncology channels.
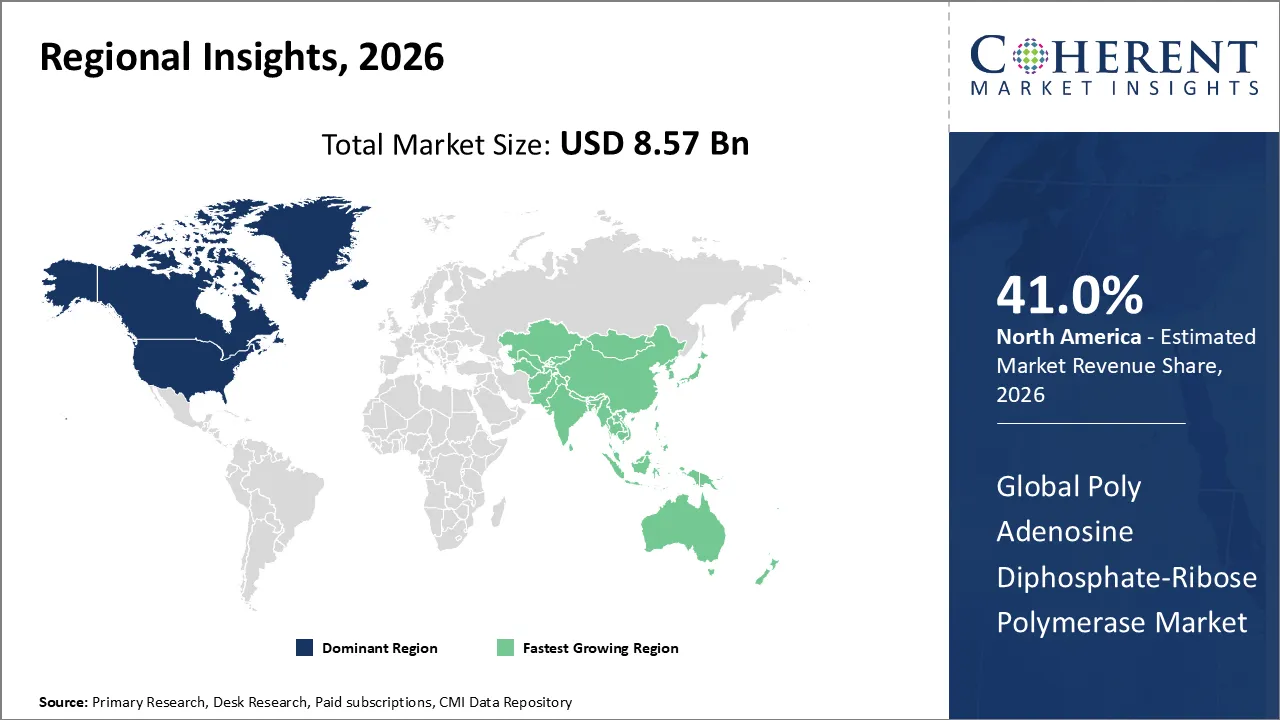
- North America is expected to lead with a share of 41.0% in 2026. The region’s growth is driven by high adoption of targeted oncology therapies, broad-based BRCA/HRR biomarker testing, strong oncology infrastructure, and continued regulatory expansion of PARP inhibitors. The U.S. FDA approved Rubraca for BRCA-mutated metastatic castration-resistant prostate cancer and Akeega for BRCA2-mutated metastatic castration-sensitive prostate cancer on a routine basis in December 2025, broadening the addressable PARP inhibitor population.
Market Drivers
Rising Burden of BRCA- and HRR-Associated Cancers is Driving the Poly Adenosine Diphosphate-Ribose Polymerase Market
The Poly Adenosine Diphosphate-Ribose Polymerase Market is gaining momentum due to the high incidence of cancers for which PARP inhibitors have established or expanding therapeutic roles including breast, ovarian, prostate and pancreatic cancers. PARP inhibitors target defects in DNA damage repair pathways and are particularly relevant to tumors with BRCA1/BRCA2 mutations and other defects in homologous recombination repair. In the U.S., the American Cancer Society estimates about 333,830 new cases of prostate cancer and 321,910 new cases of invasive breast cancer in 2026.
The worldwide burden of cancer is increasing as well. The American Cancer Society estimates that globally there were around 21 million new cancer cases diagnosed in 2024, and that number is expected to rise to around 34 million per year by the year 2050, just from population growth.
Expansion of PARP Inhibitors into New Cancer Settings is Accelerating Market Growth
Regulatory expansion beyond the traditional ovarian cancer treatment is emerging as another major driver for the PARP inhibitor market. PARP inhibitors are becoming more integrated into treatment strategies for prostate, breast, and pancreatic cancers, and combination regimens are expanding their use to earlier disease stages and biomarker-selected patient populations.
In December 2025, the US Food and Drug Administration (FDA) approved Akeega (niraparib and abiraterone acetate) plus prednisone for the treatment of adults with BRCA2-mutated metastatic castration-sensitive prostate cancer. The approval was based on the Phase III AMPLITUDE trial, in which 696 patients with HRR gene-mutated mCSPC were enrolled, marking the continued expansion of PARP-based therapy into earlier prostate cancer treatment settings.
Current Events and Their Impact on the Poly Adenosine Diphosphate-Ribose Polymerase Market
Current Event | Description and its Impact |
FDA Expands PARP Inhibitor Use in BRCA2-Mutated Metastatic Castration-Sensitive Prostate Cancer (2025) |
|
FDA Grants Regular Approval to Rubraca for BRCA-Mutated Metastatic Prostate Cancer (2025) |
|
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Segmental Insights
Why is Olaparib Acquiring the Largest Share?
On the basis of drug, the olaparib segment is estimated to account for the largest Poly Adenosine Diphosphate-Ribose Polymerase Market share of 48.5% in 2026. The segment’s dominance is supported by the broad clinical use of Lynparza (olaparib) across ovarian, breast, prostate, pancreatic, and endometrial cancers, its long-established regulatory presence, and extensive adoption in biomarker-selected BRCA/HRR-positive patient populations.
AstraZeneca reported USD 3.279 billion in Lynparza revenue in 2025 and described the drug as the leading PARP inhibitor based on total prescription volume. The company also reported that Lynparza was approved in 114 countries and maintained a standard-of-care position in advanced ovarian cancer.
In September 2026, AstraZeneca said Lynparza (olaparib) continues to be studied in early and metastatic breast cancer patients with inherited BRCA mutations in collaboration with Merck.
Why is Ovarian Cancer Acquiring the Largest Share?
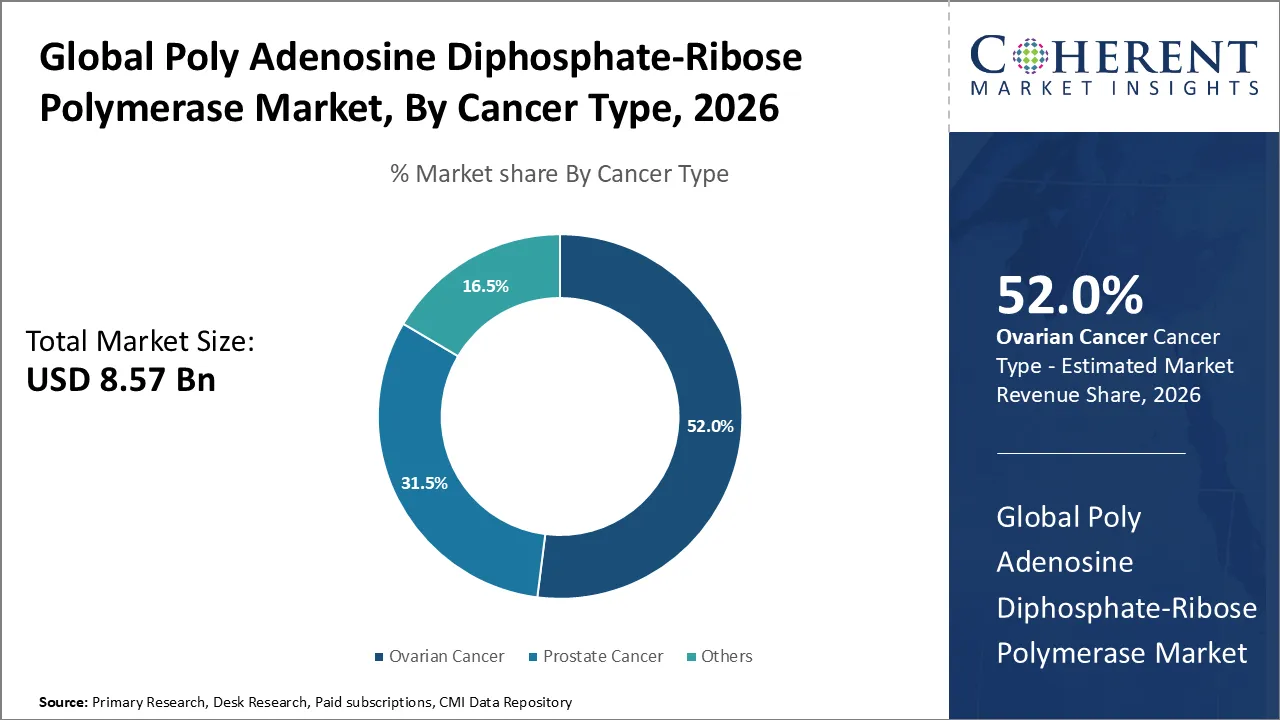
Based on cancer type, ovarian cancer segment is expected to be the leading segment with 52.0% share in 2026. The segment growth is driven by the established use of PARP inhibitors as a maintenance therapy in advanced epithelial ovarian, fallopian tube, and primary peritoneal cancers, especially in patients with BRCA mutations or homologous recombination deficiency (HRD).
In March 2026, the U.S. FDA approved an updated MyChoice CDx indication, changing it from a complementary diagnostic to a companion diagnostic for Zejula (niraparib). The assay is used to identify ovarian cancer patients with BRCA1/2 mutations and/or a positive genomic instability score who may be eligible for niraparib treatment.
Why are Hospital Pharmacies Acquiring the Largest Share?
On the basis of distribution channel, the hospital pharmacies segment is estimated to account for the largest share of 58.0% in 2026. The segment’s dominance is owing to the specialist-driven nature of PARP inhibitor treatment, requirements for biomarker testing and treatment monitoring, management of adverse events, and the concentration of complex oncology treatment within hospitals and integrated cancer centers.
In June 2025, the American Society of Health-System Pharmacists (ASHP) reported that >75% of hospitals in the United States employ pharmacists to provide direct patient care to most inpatients and 56.9% have pharmacists involved in oncology care. This highlights the expanding role of the hospital pharmacist in the care of complex cancer therapies.
In April 2026, ASHP reported that U.S. hospital drug spending increased 9.6% in 2025, with high-cost oncology and immune-modulating therapies among the major contributors, while cancer medicines remained one of the largest and fastest-growing categories across hospitals and clinics.
Poly Adenosine Diphosphate-Ribose Polymerase Market Trends
- The growing use of combination therapies with PARP inhibitors is changing treatment approaches, particularly in prostate cancer. As of 2025, FDA records have noted that three PARP inhibitors are approved alongside androgen receptor pathway inhibitors for biomarker-selected metastatic castration-resistant prostate cancer: olaparib + abiraterone, niraparib + abiraterone, and talazoparib + enzalutamide.
- Geographic commercialization of current PARP inhibitors is enhancing access in emerging oncology markets. GSK's Zejula (niraparib) was introduced in India in August 2025 for advanced ovarian cancer; the company noted it's a once-daily oral PARP inhibitor approved as first-line maintenance monotherapy for all eligible biomarker groups.
- Market development is also being influenced by increasing regulatory attention to the long-term safety profile of PARP inhibitors. In January-March 2025, the U.S. FDA identified vasculitis as a potential safety signal under evaluation for the PARP inhibitor class including Lynparza, Rubraca, Talzenna, Zejula and Akeega. This trend is increasing the importance of pharmacovigilance, adverse-event monitoring, and benefit-risk optimization as PARP inhibitors move into earlier treatment settings.
Regional Insights
North America Dominates Owing to Strong Precision Oncology Infrastructure and Expanding PARP Inhibitor Approvals
The North America region is estimated to account for 41.0% of the Poly Adenosine Diphosphate-Ribose Polymerase Market share in 2026. The region’s dominance is owing to high adoption of precision oncology, widespread BRCA/HRR testing, strong availability of approved PARP inhibitors, advanced cancer-treatment infrastructure, and continued regulatory expansion across prostate, ovarian, breast, and pancreatic cancers.
AstraZeneca also reported that its U.S. oncology sales reached USD 11.187 billion in 2025, up 18% from USD 9.510 billion in 2024. This strong oncology spending and treatment uptake provides a favorable commercial environment for targeted therapies such as PARP inhibitors.
In May 2026, Pfizer announced detailed Phase III TALAPRO-3 results showing that Talzenna (talazoparib) + Xtandi (enzalutamide) improved radiographic progression-free survival by more than 50% in men with HRR gene-mutated metastatic castration-sensitive prostate cancer.
Asia Pacific Poly Adenosine Diphosphate-Ribose Polymerase Market Trends
Asia Pacific is expected to be the fastest-growing region over the forecast period. The regional market growth is owing to the increasing cancer burden, improving access to precision oncology, wider availability of BRCA/HRR testing, entry of global oncology companies, and commercialization of PARP inhibitors across major markets such as India, China, and Japan.
In August 2025, GSK launched Zejula (niraparib) in India as a once-daily PARP inhibitor for first-line maintenance treatment of advanced ovarian cancer. GSK stated that India has approximately 35,000 patients receiving treatment for Stage III/IV ovarian cancer, of whom around 5,000 could be eligible for PARP inhibitor therapy.
Expanding Regulatory Approvals and Precision Oncology Infrastructure are Accelerating the Poly Adenosine Diphosphate-Ribose Polymerase Market in the United States
The U.S. Poly Adenosine Diphosphate-Ribose Polymerase (PARP) market is thriving, driven by the rising use of PARP inhibitors for prostate, ovarian, breast, and pancreatic cancers, the widespread availability of BRCA/HRR testing, and the continued support from the FDA for biomarker-selected oncology therapies.
In May 2026, Pfizer announced the Phase III TALAPRO-3 results, which indicated that Talzenna (talazoparib) combined with Xtandi (enzalutamide) improved radiographic progression-free survival by over 50% for men with HRR gene-mutated metastatic castration-sensitive prostate cancer. The company also reported an estimated 77% probability of remaining progression-free at three years, supporting potential expansion of PARP inhibitor use into earlier prostate cancer treatment settings.
China Poly Adenosine Diphosphate-Ribose Polymerase Market Trends
China is expected to witness strong growth in the Poly Adenosine Diphosphate-Ribose Polymerase Market owing to increasing availability of domestically developed PARP inhibitors, expanding biomarker-directed treatment, rising cancer incidence, and regulatory approvals across ovarian, breast, and prostate cancers.
In June 2025, China’s National Medical Products Administration approved senaparib capsules (Paishuning), a domestically developed Class 1 innovative PARP inhibitor from Shanghai IMPACT Therapeutics, for first-line maintenance treatment of advanced epithelial ovarian, fallopian tube, or primary peritoneal cancer following response to platinum-based chemotherapy. Source: National Medical Products Administration
Who are the Major Companies in Poly Adenosine Diphosphate-Ribose Polymerase Industry
Some of the major key players in Poly Adenosine Diphosphate-Ribose Polymerase Market are AstraZeneca plc, Johnson & Johnson Services, Inc., GlaxoSmithKline plc, Clovis Oncology, Inc., Pfizer Inc., Merck & Co., Inc., AbbVie Inc., Bristol-Myers Squibb Company, BeiGene, Ltd., and Takeda Pharmaceutical Company Limited.
Key News
- In October 2025, GSK reported that the U.S. FDA granted Orphan Drug Designation to niraparib (Zejula) for malignant glioma, including glioblastoma. Niraparib is being evaluated in the Phase III GLIOFOCUS trial for newly diagnosed MGMT-unmethylated glioblastoma, representing expansion of PARP inhibition beyond its established ovarian-cancer use.
Market Report Scope
Poly Adenosine Diphosphate-Ribose Polymerase Market Report Coverage
Report Coverage | Details | ||
Base Year: | 2025 | Market Size in 2026: | USD 8.57 Bn |
Historical Data for: | 2020 to 2024 | Forecast Period: | 2026 to 2033 |
CAGR: | 9.2% | 2033 Value Projection: | USD 15.87 Bn |
Geographies covered: |
| ||
Segments covered: |
| ||
Companies covered: | AstraZeneca plc, Johnson & Johnson Services, Inc., GlaxoSmithKline plc, Clovis Oncology, Inc., Pfizer Inc., Merck & Co., Inc., AbbVie Inc., Bristol-Myers Squibb Company, BeiGene, Ltd., and Takeda Pharmaceutical Company Limited. | ||
Growth Drivers: |
| ||
Restraints & Challenges: |
| ||
Analyst Opinion
- The Poly Adenosine Diphosphate-Ribose Polymerase Market is increasingly shifting toward earlier-line treatment and broader prostate cancer use. In December 2025, the U.S. FDA approved Akeega (niraparib + abiraterone acetate) for BRCA2-mutated metastatic castration-sensitive prostate cancer, marking the first PARP inhibitor approval in this earlier metastatic disease setting.
- The market is also trending toward PARP inhibitor combinations with androgen receptor pathway inhibitors, especially in prostate cancer. In May 2026, Pfizer reported that Talzenna (talazoparib) + Xtandi (enzalutamide) improved radiographic progression-free survival by >50% in HRR-mutated metastatic castration-sensitive prostate cancer, with an estimated 77% probability of remaining progression-free at three years. This supports the continued development of combination-based PARP strategies beyond established monotherapy settings.
- Biomarker-driven patient selection is becoming a key part of PARP inhibitor commercialization. FDA-authorized companion diagnostics have already associated PARP therapies like Akeega with BRCA1/2 testing, and newer approvals are requiring more and more confirmation of actionable DNA-repair alterations prior to treatment. This trend is strengthening the interdependence between PARP inhibitor demand and precision-oncology diagnostic infrastructure.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- By Drug (Revenue, USD Bn, 2021-2033)
- Olaparib
- Rucaparib
- Niraparib
- Others
- By Cancer Type (Revenue, USD Bn, 2021-2033)
- Prostate Cancer
- Ovarian Cancer
- Others
- By Distribution Channel (Revenue, USD Bn, 2021-2033)
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- By Region (Revenue, USD Bn, 2021-2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Rest of Latin America
- Europe
- Germany
- U.K.
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- South Africa
- Central Africa
- North Africa
- North America
Sources
Primary Research Interviews
- Medical oncologists specializing in ovarian, breast, prostate, and pancreatic cancers
- Molecular pathologists and genomic testing specialists
- Oncology pharmacists and hospital pharmacy heads
- Clinical researchers involved in PARP inhibitor trials
- R&D and medical affairs executives from oncology pharmaceutical companies
- Oncology procurement managers and formulary decision-makers
- Key opinion leaders (KOLs) in precision oncology and DNA damage response therapies
Databases
- U.S. Food and Drug Administration (FDA)
- National Cancer Institute (NCI)
- ClinicalTrials.gov
- World Health Organization (WHO)
- International Agency for Research on Cancer (IARC)
- European Medicines Agency (EMA)
- National Medical Products Administration (NMPA), China
Magazines
- The ASCO Post
- OncLive
- Cancer Network
- Pharmaceutical Technology
- BioPharma Dive
Journals
- Journal of Clinical Oncology
- The Lancet Oncology
- New England Journal of Medicine
- Nature Reviews Cancer
- Clinical Cancer Research
- Annals of Oncology
- JAMA Oncology
Newspapers
- The Wall Street Journal
- Financial Times
- The New York Times
- Reuters
- The Economic Times
Associations
- American Society of Clinical Oncology (ASCO)
- European Society for Medical Oncology (ESMO)
- American Association for Cancer Research (AACR)
- National Comprehensive Cancer Network (NCCN)
- Society of Gynecologic Oncology (SGO)
- American Society of Health-System Pharmacists (ASHP)
Public Domain Sources
- Company Annual Reports and Investor Presentations
- FDA Drug Approval and Labeling Databases
- EMA Regulatory and Assessment Reports
- Clinical Trial Registries and Published Trial Results
- National Cancer Institute Cancer Statistics
- American Cancer Society Cancer Facts & Figures
- SEC Filings of Pharmaceutical and Biotechnology Companies
- Company Press Releases and Pipeline Updates
- Peer-reviewed Publications on PARP Inhibitors and DNA Damage Response Therapies
- Patent Databases such as WIPO, USPTO, and Google Patents
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of Information for the Last 10 Years
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Poly Adenosine Diphosphate-Ribose Polymerase Market is expected to reach USD 15.87 Bn in 2033, increasing from USD 8.57 Bn in 2026.
Major players operating in the global Poly Adenosine Diphosphate-Ribose Polymerase Market include AstraZeneca plc, Johnson & Johnson Services, Inc., GlaxoSmithKline plc, Clovis Oncology, Inc., Pfizer Inc., Merck & Co., Inc., AbbVie Inc., Bristol-Myers Squibb Company, BeiGene, Ltd., and Takeda Pharmaceutical Company Limited.
The high treatment cost and development of drug resistance are the key factors hampering growth of the market.
The increasing prevalence of ovarian, breast, prostate, and pancreatic cancers, along with rising adoption of PARP inhibitors in BRCA- and HRR-mutated cancers, is boosting demand for PARP inhibitor therapies.
The Poly Adenosine Diphosphate-Ribose Polymerase Market is anticipated to grow at a CAGR of 9.2% between 2026 and 2033.
Among regions, North America is estimated to account for the largest market share, with approximately 41.0% in 2026, supported by high adoption of precision oncology, widespread BRCA/HRR testing, strong oncology infrastructure, and continued regulatory expansion of PARP inhibitors.
PARP inhibitors are targeted cancer therapies that interfere with DNA-damage repair pathways and are particularly relevant for tumors with BRCA1/BRCA2 mutations and other homologous recombination repair abnormalities.