

Prosthetic Liners Market Size and Trends - 2026 to 2033
The Prosthetic Liners Market is estimated to be valued at USD 360 Mn in 2026 and is expected to reach USD 560 Mn by 2033, growing at a compound annual growth The rate (CAGR) of 6.5% from 2026 to 2033.
Key Takeaways
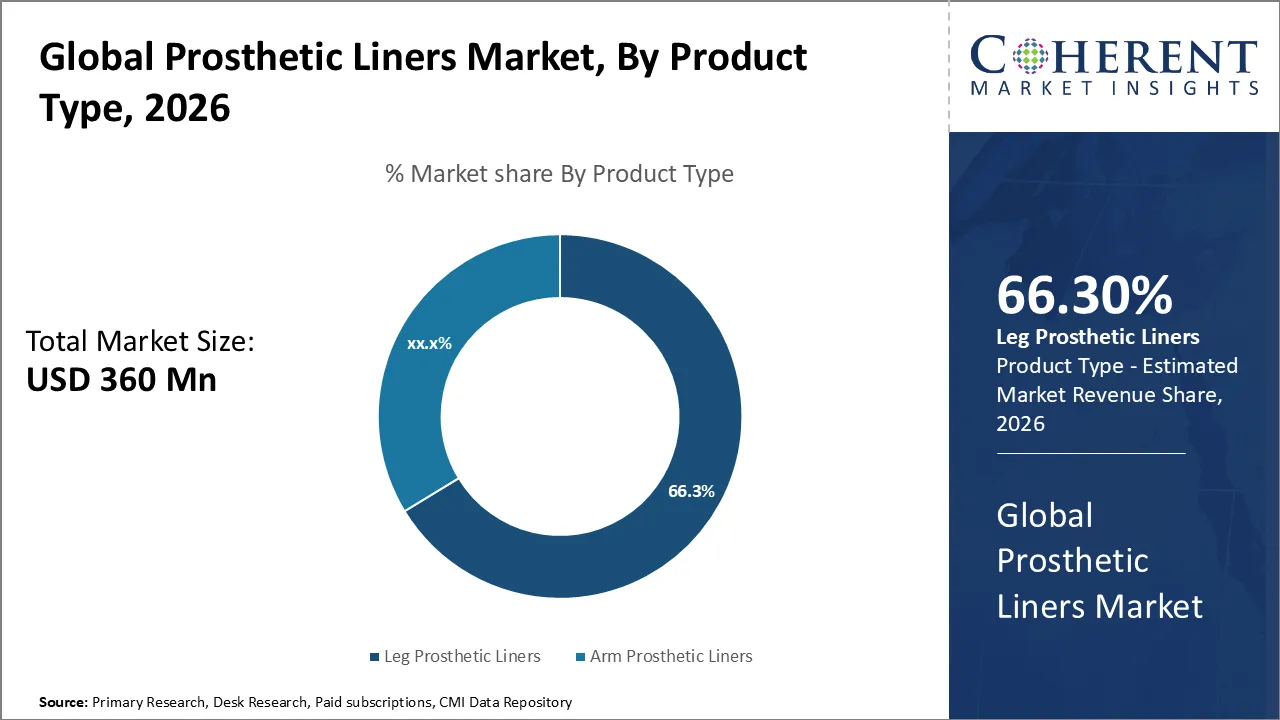
- Based on Product Type, the Leg Prosthetic Liners segment is expected to lead the market with 66.30% share in 2026, due to higher incidence of lower-limb amputations and replacement frequency.
- Based on Material, the Silicone segment is expected to hold 48.70% share of the market in 2026 driven by comfort, durability, and skin-friendly properties.
- Based on Distribution Channel, the Hospitals segment is expected to hold 62.50% share of the market in 2026 driven by primary prescriptions, reimbursement linkages, and clinical fittings.
- Based on Region, North America is set to lead the market with 39.40% share in 2026. While, Asia Pacific is anticipated to be the fastest growing region.
Market Overview
The prosthetic liners market is advancing significantly driven by its critical role in enhancing patient comfort, residual limb health, and the overall functionality of modern prosthetic systems. The increasing demand for higher-performance interface solutions and tightening clinical safety standards, particularly regarding skin integrity, moisture management, and infection control, are expected to drive market growth over the forecast period.
The modern prosthetic liners are sophisticated interface solutions mainly categorized as Silicone, Thermoplastic Elastomer (TPE), or Polyurethane systems that deliver a cushioned friction-reducing layer between the residual limb and the prosthetic socket, allowing for a stable and comfortable fit that accommodates subtle anatomical variations. These instruments are integral to advanced rehabilitation frameworks, particularly in transtibial and transfemoral prosthetic applications. This is due to their ability to provide pressure distribution and reduce skin fatigue during extended daily use.
Current Events and Its Impacts on the Prosthetic Liners Market
Current Event | Description and the Impact |
Geopolitical and Healthcare Policy Developments
|
|
Technological Innovations and R&D Advancements
|
|
Societal Trends and Demographic Shifts |
|
Segmental Insights
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Prosthetic Liners Market Insights, By Product Type – Leg Prosthetic Liners Lead Due to Higher Incidence of Lower-Limb Amputations
In terms of product type, the leg prosthetic liners segment contributes the highest share of 66.30% in 2026 of the market. The growth is because lower limb amputation occurs more frequently than upper limb cases. The increasing prevalence of diabetes, vascular disease, and traumatic injuries is driving a high demand for these targeted solutions. The liners manage the intense weight-bearing forces that users generate during walking or standing. Manufacturers now produce advanced suspension and suction liners that enhance stability, reduce skin friction, and restore patient mobility. The increasing geriatric population leads to a heightened demand for durable, high-performance leg liners. In addition, the ongoing need for dependable lower extremity support in daily activities and long-term rehabilitation also drives growth in this segment.
Prosthetic Liners Market Insights, By Material – Silicone Leads with Comfort and Durability
In terms of material, the silicone segment contributes the highest share of 48.70% in the market in 2026. The growth is owing to its ability to provide exceptional biocompatibility, hypoallergic properties, and simple maintenance routines. The material provides superior cushioning that minimizes shear forces between the residual limb and the prosthetic socket. This assists in improving user comfort and limb health. The manufacturers are incorporating dermatological activities like aloe vera to support skin hydration and reduce inflammation during prolonged use. As a result, silicone remains the preferred choice among active amputees and healthcare providers. This is due to its ability to retain structural integrity under high pressure and offer a cool, breathable interface.
Prosthetic Liners Market Insights, By Distribution Channel – Hospitals Leads with Reimbursement Linkages
In terms of distribution channel, the hospitals segment contributes the highest share of 62.50% in the market in 2026 because they act as the first point of care for patients immediately following amputation surgery. In these facilities, orthopedic surgeons and prosthetists collaborate to prescribe, fit, and calibrate the initial medical devices. The modern hospitals integrate cutting-edge diagnostic tools with dedicated rehabilitation centers to ensure seamless patient care. Furthermore, favorable reimbursement policies and direct procurement contracts between hospital networks and manufacturers streamline the delivery of high-quality liners. Hospitals function as the essential hub for professional fitting and patient education as global healthcare infrastructure expands.
Regional Insights
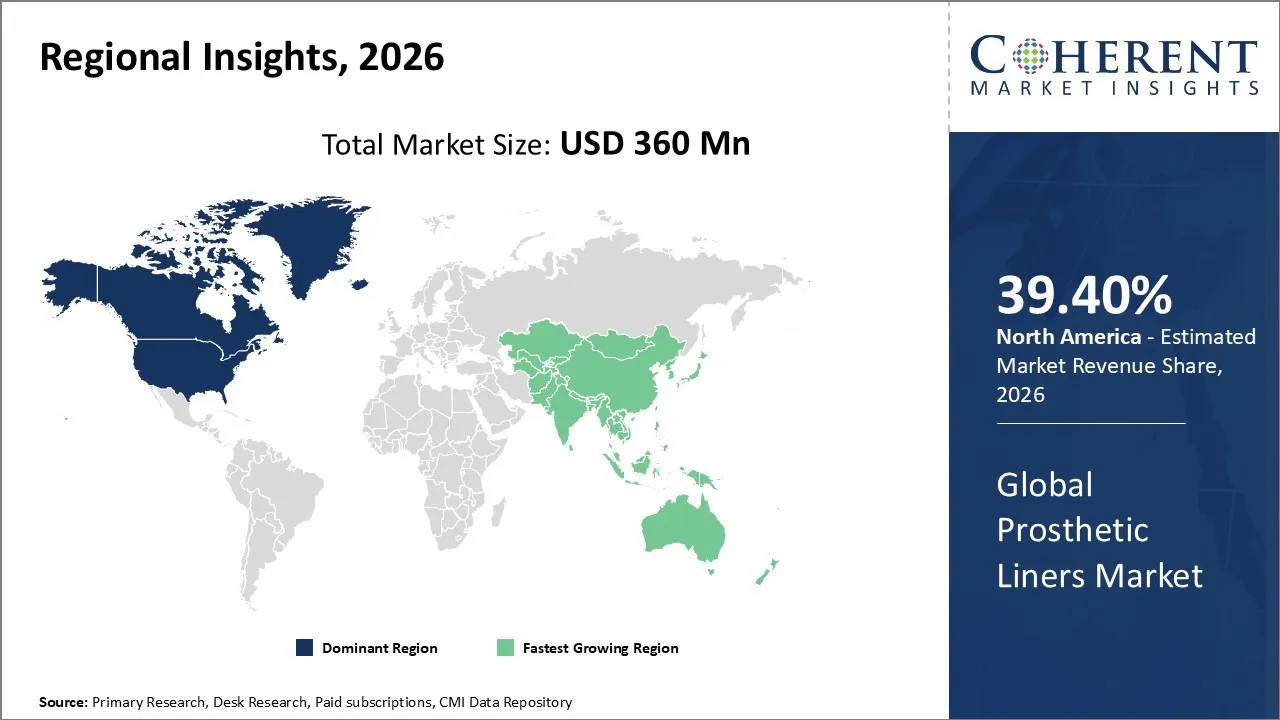
North America Prosthetic Liners Market Analysis & Trends
North America has remained the dominant region with 39.40% in 2026 of the global Prosthetic Liners Market over the past decade. The growth is due to a sophisticated healthcare infrastructure and a high concentration of market leaders like WillowWood and ALPS south. The region boasts comprehensive insurance reimbursement policies that make premium, high-cost liners accessible to a larger patient population. In addition, the persistent rise in diabetes and peripheral vascular diseases is expected to sustain long-term demand for sophisticated lower limb prosthetic systems. The ongoing R&D investments in the US and Canada are playing a critical role in speeding up the diffusion of advanced prosthetic technologies, including 3D printed custom liners and microprocessor-integrated systems. These factors ensure that North America remains the primary hub for innovation and high-value consumption in the prosthetic liners industry.
Asia Pacific Prosthetic Liners Market Analysis & Trends
The Asia Pacific region has emerged as the fastest-growing market throughout the forecast period. The increasing urbanization and a surge in traumatic injuries from road accidents substantially increase the demand for mobility aids in countries like India and China. The improving healthcare infrastructure and the rising disposable incomes allow more patients to access rehabilitative care. In addition, government initiatives aimed at supporting the disabled population and expanding public health coverage speed up the uptake of medical devices. The local manufacturers area is also focusing on cost-effective production methods to provide affordable solutions tailored to emerging economies. The growing awareness regarding Amotte rehabilitation ensures that the Asia Pacific market expands its global footprint and manufacturing influence.
Prosthetic Liners Market Outlook Country-Wise
The US Prosthetic Liners Market Trends
The US is a primary revenue contributor to the global prosthetic liners market owing to its highly advanced healthcare systems. The substantial presence of industry leaders like WillowWood and ALPS South is propelling continuous innovation in material science and custom 3D printed designs. Comprehensive reimbursement coverage and an extensive clinical infrastructure ensure consistent demand for premium, long-lasting prosthetic liners. In addition, the increasing prevalence of vascular diseases and traumatic injuries sustains a steady replacement cycle. As a result, the country of the US continues to lead as the world's most mature and commercially valuable market for prosthetic solutions.
China Prosthetic Liners Market Trends
China is witnessing growth due to its rapidly aging population and rising rates of diabetes-related amputations. The growing geriatric demographics substantially increase the demand for comfortable, high-performance liners like silicone and thermoplastic elastomers. The improving healthcare infrastructure and growing health coverage allow for more patients to access advanced rehabilitative care. The local manufacturers prioritize cost-effective production to meet the needs of the broadening middle class. These combined factors ensure that China continues to strengthen its manufacturing influence and market share in the global prosthetic liners industry.
Market Report Scope
Prosthetic Liners Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 360 Mn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 6.5% | 2033 Value Projection: | USD 560 Mn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | Ottobock SE & Co. KGaA, Össur HF, WillowWood Global LLC., ALPS South, Chas. A. Blatchford & Sons Ltd, Fillauer Inc., Streifeneder USA Inc., ST&G USA Corporation, and College Park Industries Inc. | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Prosthetic Liners Market Drivers
Increasing prevalence of amputations
The rising prevalence of limb amputations is a major driver of growth in the prosthetics market. Chronic conditions such as diabetes and peripheral vascular disease frequently lead to lower limb amputations, as severe complications remain difficult to manage. The road accidents, industry incidents, and conflict-related injuries are driving a substantial rise in the number of individuals requiring prosthetic care. The elderly are experiencing more age-related vascular conditions and falls, thus necessitating surgical interventions. These factors create an urgent need for sophisticated liners that prioritize skin health, moisture control, and comfort. The manufacturers are responding to this pressure by innovating rapidly and developing advanced materials to serve a growing patient base. This continual development ensures that users maintain their mobility and achieve a significantly higher quality of life.
Increasing development of new materials
The development of novel materials for prosthetic liners, including thermoplastic elastomer (TPE), polyurethane, copolymer, silicone, and medical-grade mineral oil gel, is expected to drive market growth. These prosthetic liners are designed to reduce friction-related injuries and enhance patient comfort. For example, Iceross liners, created by Össur, are recommended for users with low to high activity levels, where stability and suspension are crucial. Additionally, increased awareness of the advantages of prosthetic liners among the public has contributed to a rise in demand. Furthermore, the growing incidence of diabetes, which has resulted in a higher number of limb amputations, is also fueling growth in the prosthetic liners market.
Analyst Opinion (Expert Opinion)
The prosthetic liners market demonstrates structurally stable and demand-resilient characteristics, supported by consistent replacement cycles and rising prosthetic utilization globally. Industry assessments indicate that lower-limb prosthetic liners account for more than two-thirds of total demand, reflecting the higher incidence of lower-extremity amputations and the need for frequent liner replacement due to wear, hygiene, and fit optimization requirements.
From a materials standpoint, silicone liners dominate adoption, representing roughly half of total installations, due to their durability, skin compatibility, and ability to manage pressure distribution effectively. Thermoplastic elastomers and polyurethane liners together contribute a significant secondary share, favored in applications requiring flexibility, lightweight performance, and enhanced comfort for active users.
Hospitals and prosthetic & orthotic clinics collectively represent the primary procurement channels, accounting for a majority of liner fittings, while outpatient rehabilitation centers are showing measurable increases in utilization as decentralized care models expand. Regionally, North America and Europe together contribute more than 60% of global demand, supported by established reimbursement systems, advanced rehabilitation infrastructure, and higher prosthetic penetration rates. Asia-Pacific is emerging as a key volume-driven region, fueled by improving access to assistive technologies and expanding rehabilitation services.
Technological differentiation is becoming a competitive factor, with sensor-enabled liners, antimicrobial coatings, and digitally customized designs increasingly featured in new product pipelines. Despite innovation, skin irritation and pressure-related complications remain reported among a significant portion of users, reinforcing the importance of material innovation and personalized fitting solutions.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Prosthetic Liners Industry News
- In June 2025, British healthtech TG0 has developed a smart prosthetic liner that uses ultra-soft, wireless sensor materials to monitor pressure and comfort, with the intention of reducing device abandonment rates.
- In June 2025, the Richard Whitehead Foundation Beneficiaries Programme unveiled its ‘Class of 2025’ with Nissan Possibilities Project support. Nissan Possibilities Project funding provides the latest Össur sports prosthetics, improving mobility and connecting amputees to a new community.
- In May 2024, CEAS seniors developed the QL Plus amputee cooling liner at the CEAS Expo in 2025. The QL Plus amputee cooling liner aims to empower leg amputees. This innovative prosthetic liner and socket system, created by a team of CEAS seniors, provides a solution that is currently unavailable on the market by passively regulating moisture and temperature.
- In September 2023, WillowWood introduced a new brand identity to reflect its expansion into new product lines and technologies. WillowWood now offers the META® Line of high-performance feet, the Alpha Control® myoelectric liner for upper limb bionic prosthetics, and the PDAC-approved INTUY™ Knee, in addition to recent liner innovations like Alpha SmartTemp® gel liners that reduce sweat and moisture.
Market Segmentation
- Product Type Insights (Revenue, USD Mn, 2026 - 2033)
- Leg Prosthetic Liners
- Arm Prosthetic Liners
- Material Insights (Revenue, USD Mn, 2026 - 2033)
- Silicone
- Thermoplastic Elastomer (TPE)
- Polyurethane
- Distribution Channel Insights (Revenue, USD Mn, 2026 - 2033)
- Hospital
- Retail Channel
- Online Channel
- Regional Insights (Revenue, USD Mn, 2026 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- North Africa
- Central Africa
- South Africa
- Key Players Insights
- Ottobock SE & Co. KGaA
- Össur HF
- WillowWood Global LLC.
- ALPS South
- Chas. A. Blatchford & Sons Ltd
- Fillauer Inc.
- Streifeneder USA Inc.
- ST&G USA Corporation
- College Park Industries Inc.
Sources
Primary Research Interviews
- Prosthetic Liner Manufacturers
- Prosthetic & Orthotic (P&O) Clinics
- Certified Prosthetists & Orthotists (CPOs)
- Rehabilitation Center Specialists
- Biomedical Engineers – Prosthetics
- Raw Material Suppliers (Silicone, TPE, Polyurethane)
- Others
Databases
- Bloomberg Terminal
- Thomson Reuters Eikon
- IHS Markit
- Euromonitor International
- S&P Global Market Intelligence
- Statista
- Others
Magazines
- O&P Edge Magazine
- The O&P Almanac
- Medical Device Network
- Orthotics & Prosthetics News
- Healthcare Design Magazine
- Others
Journals
- Journal of Prosthetics and Orthotics
- Prosthetics and Orthotics International
- Journal of Rehabilitation Research & Development (JRRD)
- Clinical Biomechanics
- Journal of Biomedical Materials Research
- Others
Newspapers
- Financial Times
- The Wall Street Journal
- Reuters
- Bloomberg News
- The Economic Times (Healthcare Section)
- Others
Associations
- American Academy of Orthotists and Prosthetists (AAOP)
- International Society for Prosthetics and Orthotics (ISPO)
- British Association of Prosthetists and Orthotists (BAPO)
- Orthotic & Prosthetic Alliance (OPA)
- World Health Organization (WHO) – Assistive Technology
- Others
Public Domain Sources
- U.S. Food and Drug Administration (FDA) – Medical Devices Database
- Centers for Medicare & Medicaid Services (CMS)
- National Institutes of Health (NIH)
- World Health Organization (WHO)
- OECD Health Statistics
- European Commission – Medical Devices Regulation (MDR)
- Others
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of Information for the Last 8 Years
Definition: The Prosthetic Liners market comprises the global industry dedicated to the development, manufacturing, and sale of soft interface layers that are worn between the residual limb and the prosthetic socket. They line the play, playing an essential role in preserving skin health by mitigating friction and ensuring balanced pressure across the limb. The manufacturers utilize medical-grade materials like silicone, urethane, or thermoplastic elastomers to improve user comfort and suspension. The market is growing in response to healthcare providers' increasing focus on improving outcomes for amputees with traumatic or chronic etiologies. The research and development efforts are directed toward material durability and advanced skin hygiene solutions to promote long-term patient mobility.
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Prosthetic Liners Market is estimated to be valued at USD 360 Mn in 2026, and is expected to reach USD 560 Mn by 2033.
The CAGR of the Prosthetic Liners Market is projected to be 6.5% from 2026 to 2033.
Growing awareness about the benefits of prosthetic liners among the populace is one of the major factors driving the growth of the Prosthetic Liners Market.
Stringent government standards for product approvals, and regulation guidelines for product pricing is one of the major factors hampering the growth of the Prosthetic Liners Market.
In terms of product type, the leg prosthetic liners segment is estimated to dominate the market revenue share in 2026.
Ottobock SE & Co. KGaA, Össur HF, WillowWood Global LLC., ALPS South, Chas. A. Blatchford & Sons Ltd, Fillauer Inc., Streifeneder USA Inc., ST&G USA Corporation, and College Park Industries Inc. are the major players.
North America is expected to lead the Prosthetic Liners Market in 2026.