

Urea Formaldehyde Market Size and Forecast – 2026-2033
Urea Formaldehyde Market is estimated to be valued at USD 16,783.9 Mn in 2026 and is expected to reach USD 21,310.5 Mn in 2033, exhibiting a compound annual growth rate (CAGR) of 3.5% from 2026 to 2033.
Key Takeaways
- Based on Application, Particle Board dominates a significant share of 42.2% of the global market share driven by the increasing demand for cost-effective bonding agents in furniture manufacturing and modular construction.
- Based on End User Industry, the Automobiles industry, it dominates the global market share, due to the application of urea formaldehyde in automotive primers and tire manufacturing.
- Based on Region, Asia Pacific is projected the largest share of 56.87% of the global urea formaldehyde market in 2026, fuelled by economic growth, a rapidly expanding furniture industry, and increased government investments in the construction sector.
Market Overview
The global market for urea formaldehyde is experiencing stable growth with increased demand from the construction, automobile, and furniture sectors. The chemical is used widely in adhesive and resin manufacturing because of its excellent bonding property, low cost, and adaptability. Demand is further driven by the trend of substituting conventional wooden panels with engineered wood products like MDF and particle board. Yet, regulatory limitations and increasing environmental issues related to formaldehyde emissions present significant challenges to market growth.
Current Events and Their Impact on Urea Formaldehyde Market
Current Events | Description and its impact |
Global Economic Slowdown |
|
Fluctuations in Raw Material Prices |
|
Geopolitical Tensions and Trade Disputes |
|
Segmental Analysis

- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Urea Formaldehyde Market Insights, By Application - Rising Dominance of Particle Board and Sustainable Innovations in Adhesives
Based on application, the market is segmented into Particle Board, Wood Adhesives, Plywood, Medium Density Fiberboard, and Other Applications. Out of which, Particle Board is expected to dominate the global market over the forecast period and this is attributed to the increasing demand for urea formaldehyde as bonding agent in particle board. Moreover, urea formaldehyde gives cost-effective benefits over other substitute. The addition of nanocellulose to UF adhesives has been shown to enhance the mechanical properties of particleboards, such as bending strength and internal bond strength, while also reducing formaldehyde emissions by up to 31.25%. Wood Adhesives segment is also expected to witness significant growth in the near future and this is owing to the growing use of urea formaldehyde as adhesive in exterior and semi-exterior wood panels application. It is also used in preparation and bonding of both low- and high-pressure paper overlays and laminates. However, environmental concerns have prompted research into alternatives. For example, chemists have developed a non-toxic glue for plywood using glucose and citric acid, aiming to replace traditional UF adhesives. In plywood manufacturing, UF adhesives are commonly used for gluing dry veneers.
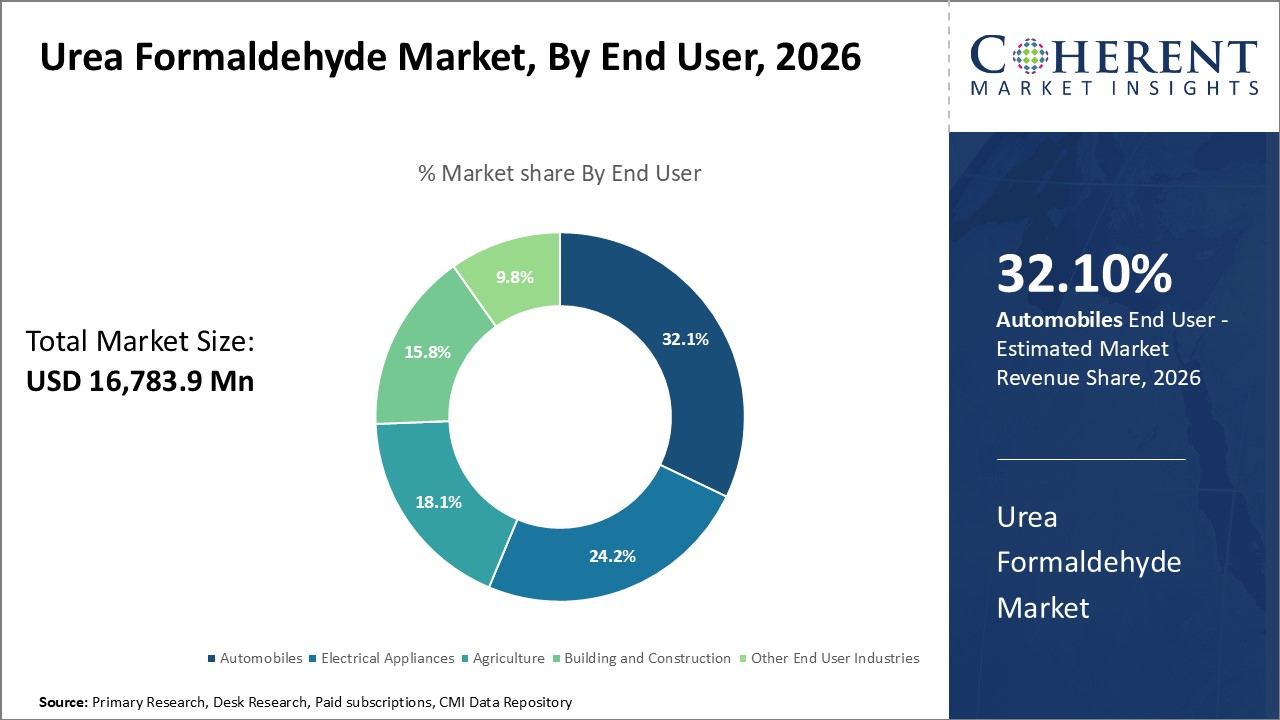
Urea Formaldehyde Market Insights, By End User - Expanding Role of UF Resins in Automotive
Based on End User industry, the market is segmented into Automobiles, Electrical Appliances, Agriculture, Building and Construction, and Other End User Industries. Out of which, Automobiles is expected to dominate the global market over the forecast period. Booming automotive production is accelerating the urea formaldehyde market growth. Global motor vehicle production saw a nearly 11 percent increase in 2023 compared to the previous year, reaching approximately 94 million units. Urea formaldehyde is widely used as an amino plastic resin which is used to produce automobiles tires in order to improve the bonding of rubber to tire cord. Moreover, urea formaldehyde also finds application as automotive primers.
Regional Insights

Asia Pacific Urea Formaldehyde Market Analysis and Trends
Regionally, Asia Pacific is estimated to account for the largest share of the 56.87% global urea formaldehyde resins market. As the region undergoes rapid economic growth, it is predicted to generate lucrative business opportunities for urea formaldehyde market players. In addition, the rapidly developing furniture industry in the region is also fuelling demand for this product. Furthermore, the high GDP growth rate in the region is also contributing to growth of the urea formaldehyde market. Besides, the government is investing heavily in the construction sector in the region, thereby bolstering the demand for urea formaldehyde. For the fiscal year 2024-25, the government has increased its capital expenditure by 11.1%, reaching $133 billion, or 3.4% of GDP. These investments are expected to drive growth in the construction sector and support the development of advanced infrastructure across the country. This is further propelling the urea formaldehyde market demand in APAC.
Europe Urea Formaldehyde Market Trends
In Europe, the urea formaldehyde resins market is anticipated to grow at a moderate pace. Countries such as Germany and members of the European Union are gradually increasing their consumption, driven by steady expansion in construction and automotive industries. Regulatory support for eco-friendly and sustainable building materials is also shaping product demand. Additionally, the focus on improving building energy efficiency and reducing emissions is likely to promote the use of high-performance materials like urea formaldehyde in various industrial applications. Europe has stricter regulations on formaldehyde use than the United States, especially in cosmetics, where the use of free formaldehyde is now forbidden due to its carcinogenic properties.
India Urea Formaldehyde Market Trends
"Neem coating of urea prevents its misuse by chem industry" discusses the Indian government's initiative to neem-coat all domestically produced urea to curb its diversion for non-agricultural uses, particularly in the chemical industry. This policy aims to ensure that subsidized urea is primarily used for agricultural purposes, thereby reducing its availability for industrial applications. By restricting the diversion of urea to non-agricultural sectors, the availability of urea for manufacturing urea formaldehyde resins may be affected, potentially leading to increased costs or the need for alternative sourcing strategies for industrial users. This development underscores the importance of regulatory policies in shaping the dynamics of chemical markets in India, particularly for industries dependent on key raw materials like urea.
United States Urea Formaldehyde Market Trends
The U.S. formaldehyde market, which includes urea formaldehyde resins, exhibited remarkable price stability. This stability is attributed to balanced supply and demand dynamics, stable feedstock costs (such as methanol and natural gas), and effective management of production and regulatory costs by industry players. Urea formaldehyde resins are extensively used in the production of particleboard, medium-density fiberboard (MDF), and plywood, which are essential materials in the construction and furniture industries. The U.S. Environmental Protection Agency (EPA) has implemented regulations to limit formaldehyde emissions from wood products. This has led manufacturers to develop low-emission urea formaldehyde resins to comply with these standards and address health concerns, further accelerating the urea formaldehyde market growth.
Global Urea Formaldehyde Market Trends:
Growing Demand in Furniture Industry
Urea formaldehyde resins are extensively used in producing plywood, particleboard, and medium-density fiberboard (MDF), which are integral to construction and furniture manufacturing. The increasing demand for affordable and durable materials in these sectors is propelling market growth. For instance, according to an article published by the Niir Project Consultancy Services, a typical UF-85 Urea Formaldehyde application utilizes synthetic resin adhesives in wood products, laminates, and engineered boards. This thermosetting polymer hardens during the curing process, resulting in a highly durable and strong material. This is further accelerating the urea formaldehyde market demand.
Global Urea Formaldehyde Market Opportunities:
Increasing demand for consumer electronic and automobile is a trend
There is a high demand for good quality resins in automobile and electronic will favor the market growth. For instance, urea formaldehyde is used in various electrical applications, such as knobs, desk lamps, fuse boxes, switches, etc. Growing construction activities, along with house renovation activities across the world, is projected to augment the demand for urea formaldehyde resins in the electrical sector.
Global Urea Formaldehyde Market Restraints:
Strict government regulation due to health hazards associated urea is hindering market growth
According to the National Toxicology Program, formaldehyde is a proven human carcinogen as of 2011. Government restrictions on formaldehyde emissions might slow the market's expansion for urea formaldehyde. Emission regulations for formaldehyde from composite wood products are established by the Formaldehyde Standards for Composite Wood Products Act of 2010.
Market Report Scope
Urea Formaldehyde Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 16,783.9 Mn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 3.5% | 2033 Value Projection: | USD 21,310.5 Mn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | Hexion, BASF SE, Georgia-Pacific Chemicals, Hexza Corporation Berhad, Metadyena, Jiangsu sanmu group Co. Ltd, Ashland, ARCL Organics Ltd., Kronoplus Limited, Advachem, Qafco, Sabic, Acron Group, Asta Chemicals, Melamin KemiÄÂna Tovarna D.D. KoÄÂevje, and Arclin Inc. | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Global Urea Formaldehyde Market: Key Developments
- In October 2024, Unilin announced a €20 million investment to launch industrial-scale MDF recycling at its Bazeilles site in France. The initiative, offered through Unilin Technologies, aims to address the recycling challenge of MDF and HDF products, such as laminate flooring, which are difficult to recycle due to the use of urea-formaldehyde adhesive.
- In September 2024, Kanoria Chemicals & Industries increased its formaldehyde production capacity in Gujarat by launching a new plant that utilizes the latest metal oxide-based technology.
- In February 2019, Georgia-Pacific Chemicals has developed LEAF® (Low Emission Adhesive Formaldehyde) resins, designed to meet stringent environmental standards. These resins comply with green building certifications and regulations, offering manufacturers a sustainable option for wood adhesive applications.
- In July 2018, BASFincreased the prices for all its Kauramin and Kaurit impregnating resins in Europe by EUR 30 per metric ton, effective from August 2018.
Analyst Opinion (Expert Opinion)
- The Chinese government's commitment to a USD 13 trillion investment in housing projects will significantly accelerate the demand for urea formaldehyde-based resins, especially in the production of particleboard and medium-density fiberboard (MDF). These materials are essential for the construction of residential and commercial spaces. The push to meet housing demand in urban areas, along with ongoing infrastructure projects, is expected to fuel a substantial increase in UF resin consumption across the region.
- Additionally, as India’s automotive sector continues to grow at an impressive 25%, particularly with the rise of manufacturing hubs, UF resin demand for automotive interior components is forecasted to increase by 18% annually. This trend reflects India’s growing position as a manufacturing powerhouse for both domestic and international automotive brands.
- The European Union’s tightening formaldehyde emission standards, under the REACH regulations, have added compliance costs for producers. It is estimated that meeting these stricter requirements will add USD 12-18 per ton to the cost of European UF resins. These regulations are pushing companies to develop low-emission alternatives, creating a shift in product formulations.
- The California Air Resources Board (CARB) Phase-III standards, which mandate a 40% reduction in volatile organic compounds (VOCs) by 2026, will require substantial reformulations in UF resins. These changes will impact product performance and production timelines, adding to the complexity of the market in North America.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- By Application (Revenue, USD Bn, 2026–2033)
- Particle Board
- Wood Adhesives
- Plywood
- Medium-Density Fibreboard (MDF)
- Other Applications
- By End User (Revenue, USD Bn, 2026–2033)
- Automobiles
- Electrical Appliances
- Agriculture
- Construction
- Others
- By Regional Insights (Revenue, USD Bn, 2026–2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East & Africa
- GCC Countries
- Israel
- South Africa
- Rest of Middle East & Africa
- North America
- Key Player Insights (Revenue, USD Mn, 2021 - 2033)
- Hexion Inc.
- BASF SE
- Georgia-Pacific Chemicals
- Hexza Corporation Berhad
- Metadynea
- Jiangsu Sanmu Group Co. Ltd
- Ashland
- ARCL Organics Ltd.
- Kronoplus Limited
- Advachem
- QAFCO (Qatar Fertiliser Company)
- SABIC (Saudi Basic Industries Corporation)
- Acron Group
- Asta Chemicals
- Melamin Kemijska Tovarna d.d. Kočevje
- Arclin Inc.
Sources
Primary Research Interviews from the Following Stakeholders:
- Product managers and polymer scientists at UF resin manufacturing companies
- Procurement heads at furniture, construction, and wood panel processing industries
- Government officials from ministries of chemicals, industrial development, and urban infrastructure
- Environmental compliance officers and material safety experts
- R&D directors involved in thermosetting resin innovation and bio-based substitutes
Databases:
- United Nations Industrial Development Organization (UNIDO)– Polymer and Resin Manufacturing Data
- U.S. Geological Survey (USGS)– Industrial Chemicals and Resins Statistics
- OECD Chemical Safety and Biosafety Database
- European Chemicals Agency (ECHA)– Formaldehyde Risk Assessment and Regulatory Dossiers
- World Bank Open Data – Industrial Manufacturing & Emissions
Magazines & Journals:
- Polymer-Plastics Technology and Engineering (Taylor & Francis)
- Industrial & Engineering Chemistry Research (ACS Publications)
- Journal of Applied Polymer Science
- Wood Science and Technology (Springer)
- Construction and Building Materials Journal (Elsevier)
- International Journal of Adhesion and Adhesives
News Outlets:
- Bloomberg Chemicals & Materials Section
- Reuters (Commodities and Industrial Materials)
- The Economic Times – Chemicals & Infrastructure
- Chemical Watch News & Analysis
- Financial Times – Global Manufacturing Reports
- LiveMint – India’s Furniture and Building Industry Coverage
Associations:
- American Chemistry Council (ACC)– Formaldehyde Panel
- European Panel Federation (EPF)– Composite Panels and Resins Reports
- Indian Chemical Council (ICC)– Policy Reports on UF and Formaldehyde Use
- National Association of Home Builders (NAHB)– Material Use Trends in Construction
- The Adhesive and Sealant Council (ASC)– Applications in Wood Adhesives and Laminates
Public Domain Sources:
- U.S. Environmental Protection Agency (EPA)– Formaldehyde Standards for Composite Wood Products Act
- Ministry of Chemicals and Fertilizers (India)– Annual Reports and Polymer Market Studies
- EU REACH Regulation Database – Substance Registration on Formaldehyde
- Ministry of Environment, Forest and Climate Change (India)– Emission and Toxicity Guidelines
- United Nations Environment Programme (UNEP)– Reports on Industrial Emissions from Resin Usage
- Occupational Safety and Health Administration (OSHA)– Formaldehyde Exposure Limits and Safety Guidelines
Proprietary Elements:
- CMI Data Analytics Tool, and Proprietary CMI Existing Repository of information for last 8 years
*Definition: Urea-formaldehyde (UF) is a polymer that can be produced by oxidation of methanol. The reaction between methanol and urea leads to the formation of a resin, called UF-resin, which is suitable for the production of a variety of interior products.
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Urea Formaldehyde Market is estimated to be valued at USD 16,783.9 Mn in 2026, and is expected to reach USD 21,310.5 Mn by 2033.
The CAGR of the Urea Formaldehyde Market is projected to be 3.5% from 2026 to 2033.
Increasing demand for medium density fiberboard and growing demand for practice board from furniture sector are fuelling the market.
The Particle Board segment is the leading component segment in the market.
Strict government regulation due to health hazards is the major factors restraining market.
Hexion, BASF SE, Georgia-Pacific Chemicals, Hexza Corporation Berhad, Metadyena, Jiangsu sanmu group Co. Ltd, Ashland, ARCL Organics Ltd., Kronoplus Limited, Advachem, Qafco, Sabic, Acron Group, Asta Chemicals, Melamin Kemicna Tovarna D.D. Kocevje, and Arclin Inc.