

Veterinary Oncology Market Analysis & Forecast - 2026 to 2033
Global veterinary oncology market is estimated to be valued at USD 907.8 Mn in 2026 and is expected to reach USD 2,006.8 Mn by 2033, exhibiting a compound annual growth rate (CAGR) of 12.0% from 2026 to 2033.
Key Takeaways
- By Animal Type, the companion animal segment is estimated to dominate the veterinary oncology market with a 60.8% share in 2026.
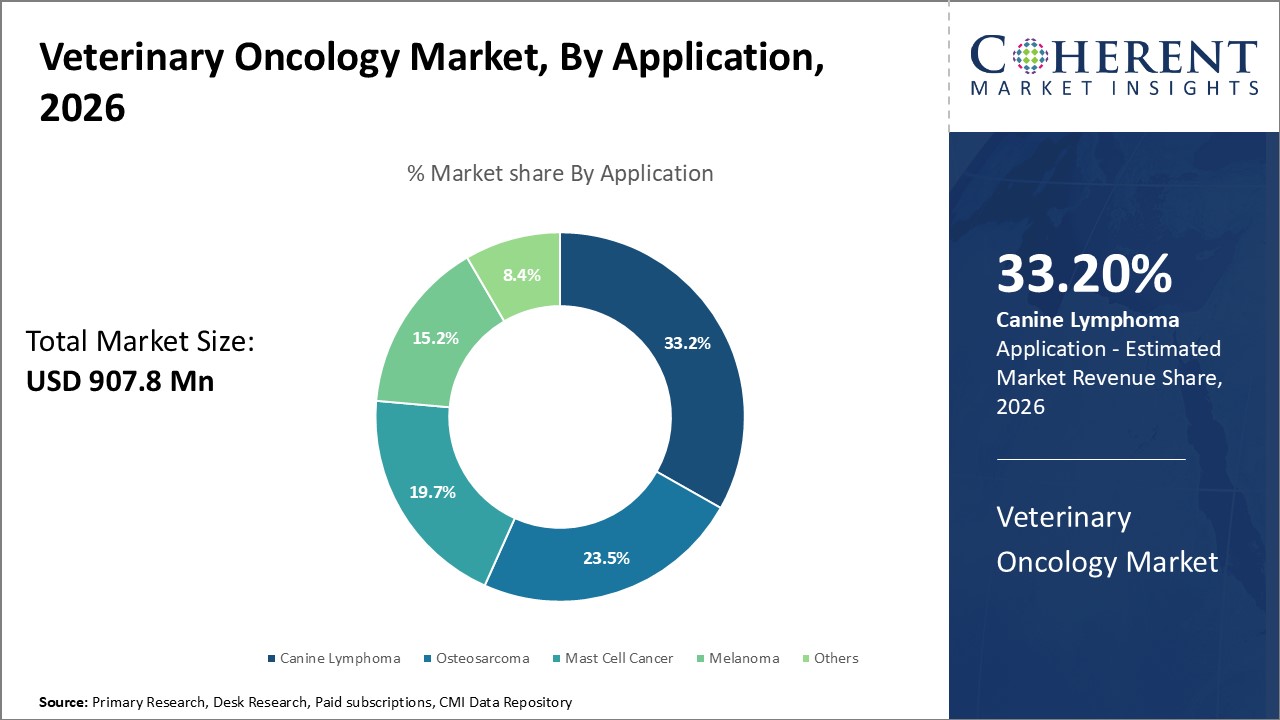
- By Application, the canine lymphoma segment is projected to lead the application category with a 33.2% market share in 2026.
- By Distribution Channel, the hospital pharmacies segment is expected to hold 41.7% of the market share in 2026.
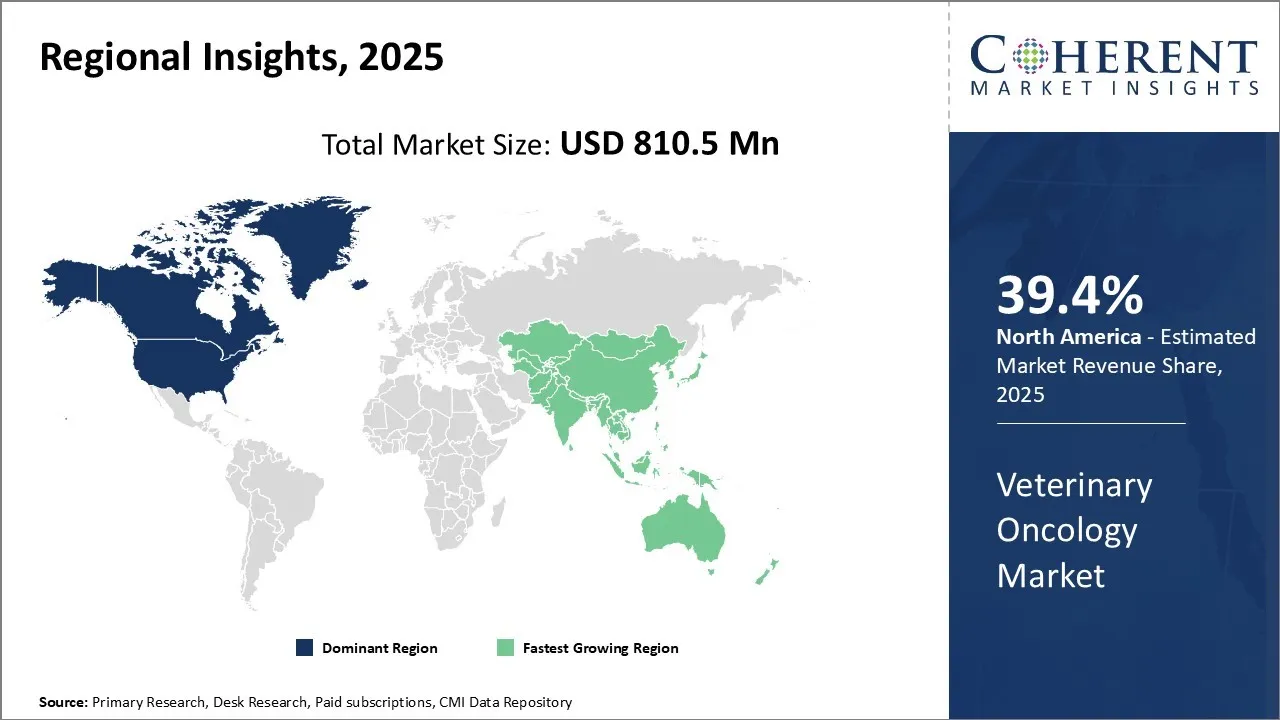
- By Region, North America is anticipated to maintain its dominance in the veterinary oncology market with a 39.4% share in 2026.
Market Overview
The global veterinary oncology market is expanding steadily, driven by rising pet ownership, increased awareness of animal health, and advancements in cancer diagnostics and treatments. Companion animals dominate the market due to growing emotional attachment and spending on pet care. Canine lymphoma leads among cancer types treated. Hospital pharmacies are key distribution hubs, offering specialized care.
Current Events and its Impact on the Veterinary Oncology Market
Current Event | Description and its impact |
Rise in Pet Cancer Cases Globally |
|
Increased Pet Insurance Adoption |
|
Expansion of Veterinary Specialty Clinics |
|
Veterinary Oncology Market Trends
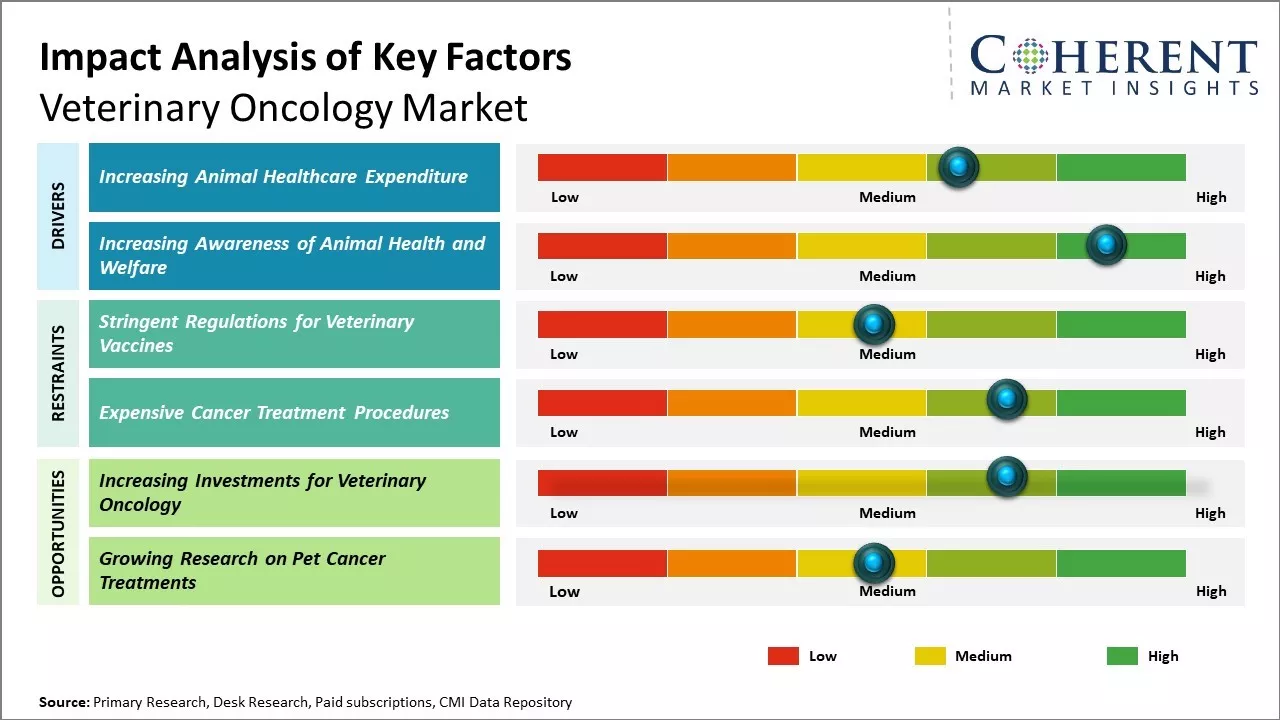
- Increasing Animal Healthcare Expenditure
Increasing animal healthcare expenditure is expected to drive the global veterinary oncology market Iover the forecast period. For instance, in May 2023, the North American Pet Health Insurance Association (NAPHIA) released its 2023 State of the Industry (SOI) report showing that the North American pet health insurance sector grew by 23.5% in In-Force GWP over 2022.
- Increasing Awareness of Animal Health and Welfare
Increasing awareness of animal health and welfare and shifts in demographics and lifestyles leading to increased spending on pet healthcare are expected to drive the market growth over the forecast period. For instance, in May 2021, - Petco Health and Wellness Company, Inc., a complete partner in pet health and wellness, launched Together Strong, a pet cancer awareness campaign that brings two- and four-legged survivors together to highlight how routine preventative care is as vital for pets as it is for humans in the fight against cancer.
Along with the campaign and in partnership with PetDx, a molecular diagnostics company aiming to revolutionize the detection, characterization and management of cancer in pets, Petco will begin offering OncoK9 a ground-breaking multi-cancer early detection test for dogs – at its full-service vet hospitals in select locations.
- Stringent Regulations for Veterinary Vaccines
Stringent regulations for veterinary vaccines across various geographies are proving to be a major restraining factor for the growth of the global veterinary oncology market. Regulatory authorities across countries have implemented strict norms and guidelines for the development, manufacturing and approval of new veterinary vaccines to ensure safety, efficacy, and quality.
Complying with these complex regulations involves extensive clinical trials, comprehensive documentation and significant investments of both time and funds. This lengthens the overall product development lifecycle considerably and delays the market introduction of new oncology vaccines.
Opportunities in the veterinary oncology market
- Increasing Investments for Veterinary Oncology
Increasing investments for veterinary oncology healthcare is expected to offer lucrative opportunities in the market. For instance, in December 2021, PetDx, the start up behind an early cancer-detecting blood test for dogs, raised the funding of USD 62 million to get canine cancer-detecting tech to vets across the U.S. OncoK9 can detect 30 cancers from a blood draw in front of more veterinarians and become a standard test in pet clinics across the country.
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Segmental Insights

Veterinary Oncology Market Insights, By Animal Type
The companion animal segment is estimated to dominate the veterinary oncology market with a 60.8% share in 2026. This growth is primarily driven by the rising trend of pet ownership worldwide, especially in urban areas. Dogs and cats are increasingly treated as family members, leading to heightened awareness and demand for advanced veterinary care.
As cancer becomes one of the leading causes of death among pets, the demand for timely and effective oncology treatment options continues to rise sharply in this segment.
Veterinary Oncology Market Insights, By Application
The canine lymphoma segment is projected to hold 33.2% of the veterinary oncology market in 2026. The large global population of dogs, combined with the high incidence of lymphoma, is driving demand for accurate diagnostics and effective treatments. This segment’s growth is also supported by advancements in chemotherapy and immunotherapy protocols, along with increasing veterinary awareness and availability of specialized cancer care for dogs.
Veterinary Oncology Market Insights, By Distribution Channel
The hospital pharmacies segment is expected to dominate the distribution channel category, holding 41.7% of the market share in 2026. Veterinary hospitals play a critical role in dispensing specialized oncology medications and offering integrated cancer care services. Their access to advanced facilities and trained professionals allows for more comprehensive treatment options, including chemotherapy and radiation, which supports this segment’s leading position in the market.
Regional Insights
North America Veterinary Oncology Market Analysis and Trends
North America is anticipated to maintain its dominance in the global veterinary oncology market with a 39.4% share in 2026. This leadership is driven by strong economic conditions, high pet ownership rates, and greater awareness regarding pet healthcare. In the U.S. and Canada, increasing disposable incomes enable pet owners to invest in premium veterinary services, including advanced cancer diagnostics and treatments. The region also benefits from a well-established veterinary infrastructure, widespread availability of oncology specialists, and robust insurance coverage for pets.
Continuous innovation by pharmaceutical companies and the presence of veterinary teaching hospitals further strengthens North America’s position as the global leader in animal cancer care. Additionally, growing collaborations between research institutions and veterinary clinics support the development and accessibility of cutting-edge therapies such as immunotherapy and precision medicine.
Europe Veterinary Oncology Market Analysis and Trends
Europe is expected to witness strong growth in the veterinary oncology market over the forecast period, supported by rising pet adoption and increasing prioritization of animal welfare. Countries such as Germany, France, and the UK are seeing a surge in pet healthcare expenditure, which includes early cancer detection and treatment services. The region's strict regulatory framework and strong veterinary education systems have resulted in a high standard of oncology care across both urban and rural settings.
Additionally, European governments and NGOs are actively promoting preventive veterinary healthcare and funding research into animal diseases, including cancer. The growing presence of pet insurance, coupled with expanding veterinary clinic networks, is making oncology treatments more accessible. With its commitment to quality care and innovation, Europe is emerging as a key hub for veterinary oncology development and adoption.
Veterinary oncology market Dominating Countries
United States and Canada
The United States and Canada are the leading countries in the global veterinary oncology market, with North America projected to account for 39.4% of the market share in 2026. The U.S. boasts a highly developed veterinary healthcare infrastructure, widespread pet insurance coverage, and a growing focus on companion animal wellness, all of which contribute to high adoption rates of advanced cancer diagnostics and therapies.
Canada complements this with increasing pet ownership, expanding veterinary service networks, and government support for animal health research. Together, these countries dominate the regional market through clinical advancements, research collaborations, and the availability of specialized veterinary oncology services.
Market Report Scope
Veterinary Oncology Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 907.8 Mn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 12.0% | 2033 Value Projection: | USD 2,006.8 Mn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | Zoetis Inc., Elanco, AB Science, Boehringer Ingelheim International GmbH, Zenoaq, VetDC, Morphogenesis, Inc., Karyopharm Therapeutics, Inc., Regeneus Ltd., AdvaVet, Inc., Rhizen Pharmaceutical SA., PetCure Oncology, Varian Medical Systems, Accuray Incorporated, Merck Animal Health, Regeneus Ltd., and VolitionRx Limited | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Analyst Viewpoint – Veterinary Oncology Market
- The global veterinary oncology market is witnessing robust growth, fueled by the rising prevalence of cancer in companion animals and increased awareness among pet owners regarding advanced treatment options. Analysts emphasize that the companion animal segment continues to dominate, supported by higher rates of pet adoption and willingness to invest in specialized veterinary care, particularly in developed regions like North America and Europe.
- Technological innovations such as targeted therapies, immunotherapies, and precision diagnostics are transforming the treatment landscape. Experts note a growing preference for FDA-approved oncology drugs like Tanovea and Palladia, which are improving clinical outcomes and expanding therapeutic choices. Veterinary oncologists are also exploring minimally invasive procedures and personalized treatment protocols to balance efficacy with quality of life.
- Regionally, North America leads the market due to its advanced veterinary infrastructure, strong pet insurance penetration, and high disposable income. Analysts foresee growing demand in Asia Pacific and Latin America as veterinary awareness and healthcare expenditure increase.
Veterinary Oncology Market: Key Development
- In April 2025: VolitionRx presented its Q Vet Cancer Test at the 2025 WVC Conference. This non-invasive epigenetic blood test detects multiple cancers in dogs and is aimed at early-stage diagnosis in general veterinary practices. Its ease of use and affordability make it highly accessible, potentially improving outcomes through earlier treatment.
- In January 2025: IDEXX Laboratories launched Cancer Dx, a low-cost blood test for early canine lymphoma detection. Priced at just $15 and designed to be part of routine wellness exams, the test promotes early intervention and expands access to oncology diagnostics in general veterinary clinics.
- In April 30, 2024: To prepare for increased demand, ELIAS Animal Health opened an expanded GMP-compliant facility in Lenexa, Kansas. The plant supports production of ECI®, reflecting ELIAS’s readiness for commercialization ahead of full licensure.
- In April 10, 2024: ELIAS Animal Health appointed Brian Segebrecht as Chief Revenue Officer to drive commercialization strategy for ECI. His appointment marks a significant step in ELIAS’s transition from research to market-ready solutions in veterinary oncology.
Market Segmentation
- By Animal Type (Revenue, USD Mn, 2021 - 2033)
- Companion Animal
- Equine
- Canine
- Feline
- Livestock Animal
- By Therapy Type (Revenue, USD Mn, 2021 - 2033)
- Chemotherapy
- Combination Therapy
- Immunotherapy
- Targeted Therapy
- By Mode of Administration (Revenue, USD Mn, 2021 - 2033)
- Oral
- Intravenous
- By Application (Revenue, USD Mn, 2021 - 2033)
- Canine Lymphoma
- Osteosarcoma (OSA)
- Mast Cell Cancer
- Melanoma
- Others
- By Distribution Channel (Revenue, USD Mn, 2021 - 2033)
- Hospital Pharmacies
- Government Agencies
- Retail Pharmacies
- By Region (Revenue, USD Mn, 2021 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC Countries
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
- Company Profiles
- Zoetis Inc.
- Elanco
- AB Science
- Boehringer Ingelheim International GmbH
- Zenoaq
- VetDC
- Morphogenesis, Inc.
- Karyopharm Therapeutics, Inc.
- Regeneus Ltd.
- AdvaVet, Inc.
- Rhizen Pharmaceutical SA.
- PetCure Oncology
- Varian Medical Systems
- Accuray Incorporated
- Merck Animal Health
- VolitionRx Limited
- Regeneus Ltd.
Sources
The Stakeholders Consulted
- Veterinary oncologists and clinicians at companion animal hospitals
- Manufacturers and suppliers of veterinary oncology therapeutics and diagnostics
- Veterinary pharmaceutical companies and biotech firms
- Regulatory authorities and animal health certification agencies
- Veterinary research institutions and academic collaborators
- Animal healthcare distributors and hospital procurement departments
- Pet insurance companies and veterinary service providers
- Pet owners (for behavior, treatment preference, and awareness assessment)
Databases Opened
- U.S. Food and Drug Administration (FDA) – Animal Drugs & Biologics Database
- European Medicines Agency (EMA) – Veterinary Medicines Information
- American Veterinary Medical Association (AVMA) – Pet Demographics & Oncology Trends
- World Organisation for Animal Health (WOAH) – Animal Health Data
- National Cancer Institute (NCI) – Comparative Oncology Program
- ClinicalTrials.gov – Veterinary Oncology Trials
- ScienceDirect, SpringerLink – Veterinary Medicine and Oncology Journals
Magazines & Trade Publications
- Today’s Veterinary Business
- Veterinary Practice News
- DVM360 Magazine
- Animal Pharm News
- Vet Record (BMJ) – Oncology & Diagnostics
- Pet Product News International
Scientific and Industry Journals
- Journal of Veterinary Internal Medicine
- Veterinary and Comparative Oncology (Wiley)
- Journal of Veterinary Medical Science
- Journal of Small Animal Practice
- Frontiers in Veterinary Science – Oncology Section
- PLOS ONE – Veterinary Oncology Research
Newspapers & Media Outlets
- The Wall Street Journal – Healthcare & Veterinary Business
- Bloomberg – Animal Health & Biotech Updates
- Reuters – Pet Care and Life Sciences Coverage
- The Economic Times – Pharma & Healthcare Section
- Business Standard – Biotechnology and Animal Welfare
Associations and Regulatory Bodies
- American College of Veterinary Internal Medicine (ACVIM) – Oncology Specialty
- U.S. FDA – Center for Veterinary Medicine (CVM)
- European Medicines Agency (EMA) – Veterinary Medicines Division
- World Small Animal Veterinary Association (WSAVA)
- Indian Veterinary Association (IVA)
- Canadian Veterinary Medical Association (CVMA)
Public Domain Sources
- USDA – Animal and Plant Health Inspection Service (APHIS) Reports
- National Institutes of Health (NIH) – Comparative Oncology Program
- European Commission – Animal Health and Welfare Reports
- World Organisation for Animal Health (WOAH) – Annual Reports
- World Bank – Global Health and Veterinary Service Indicators
Proprietary Research Elements
- CMI Data Analytics Tool
- Proprietary CMI Repository of Market Data (covering past 8 years)
- CMI Expert Interviews and Transcripts (focused on veterinary oncology trends, therapy adoption, and diagnostic innovation)
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Veterinary Oncology Market size is estimated to be valued at USD 907.8 Mn in 2026, and is expected to reach USD 2,006.8 Mn by 2033.
The CAGR of the Veterinary Oncology industry is projected to be 12.0% from 2026 to 2033.
Increasing animal healthcare expenditure and increasing awareness of animal health and welfare are the major factors driving the growth of the market.
Stringent regulations for veterinary vaccines and expensive cancer treatment procedures are the major factor hampering the growth of the global market.
In terms of Animal Type, Companion Animal is estimated to dominate the market revenue share in 2026.
Zoetis Inc., Elanco, AB Science, Boehringer Ingelheim International GmbH, Zenoaq, VetDC, Morphogenesis, Inc., Karyopharm Therapeutics, Inc., Regeneus Ltd., AdvaVet, Inc., Rhizen Pharmaceutical SA., PetCure Oncology, Varian Medical Systems, Accuray Incorporated, Merck Animal Health, Regeneus Ltd., and VolitionRx Limited are the major players.
North America is expected to lead the veterinary oncology industry.