

Urinary Catheters Market Analysis & Forecast: 2026-2033
The global urinary catheters market is estimated to be valued at USD 6.58 Bn in 2026 and is expected to reach USD 10.09 Bn by 2033, exhibiting a compound annual growth rate (CAGR) of 6.3% from 2026 to 2033.
Key Takeaways
- By Product Type, The Intermittent Catheter Segment is projected to lead the urinary catheters market in 2026, commanding a dominant 55.8% share.
- By Application, The Urinary Incontinence Sub-Segment is estimated to hold the largest market share of 40.6% in 2026.
- By End User, The Hospitals Segment is expected to maintain the largest share of 44.2% in 2026.
- By Region, North America is anticipated to dominate the market with an estimated 38.1% share in 2026.
Market Overview
The urinary catheters market is experiencing significant growth driven by rising prevalence of urinary disorders, increasing geriatric population, and advancements in catheter technology. For instance, the aging global population leads to higher incidences of urinary incontinence and retention, boosting catheter demand. Additionally, growing awareness and adoption of minimally invasive procedures have propelled the use of specialized catheters like Foley and intermittent catheters. Technological innovations, such as antimicrobial coatings and biocompatible materials, enhance patient safety and comfort, further expanding market adoption. For example, the introduction of antimicrobial-coated catheters has reduced infection rates in hospitals, encouraging healthcare providers to prefer these advanced options. These factors collectively contribute to the steady expansion of the urinary catheters market worldwide.
Current Events and Its Impact on the Urinary Catheters Market
Event | Description and Impact |
Aging Global Population Demographics and Rising Chronic Diseases |
|
Regulatory Harmonization and Medical Device Safety Standards |
|
Technological Innovation in Smart Medical Devices and Materials |
|
Pipeline Analysis
Innovation in urinary catheters is primarily focused on enhancing safety, comfort, and monitoring capabilities to improve outcomes in urinary catheterization procedures. Unlike pharmaceuticals, urinary catheters progress through R&D, regulatory clearances such as FDA 510(k), and CE marking rather than traditional clinical trial phases.
Current pipeline developments highlight antimicrobial and infection prevention technologies, such as silver-alloy coated catheters by Teleflex and ConvaTec, and nitric oxide-releasing catheters under clinical development by Novan Inc. These innovations aim to reduce catheter-associated urinary tract infections (CAUTIs), a major challenge in urinary catheter usage in hospitals.
Material innovation also plays a key role, with hydrogel-coated catheters improving patient comfort and biocompatibility, alongside emerging biodegradable catheter components under early research. Another important area is smart/connected catheters, including IoT-enabled monitoring devices and pressure-sensing Foley catheters, which provide real-time data to enhance patient management.
In terms of materials, the ongoing debate between latex vs silicone urinary catheters persists, with silicone favored for reduced allergic reactions and increased patient tolerance. Intermittent urinary catheters continue to gain prominence due to their benefits in minimizing infection risks and supporting self-catheterization.
Leading companies driving these innovations include Teleflex, Coloplast, ConvaTec, BD, and Boston Scientific.
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Patent Landscape
The urinary catheters market features a tight competition as a result of increased patents regarding infection control, catheter design improvement, and ensuring patients’ comfort. Many patents focus on antimicrobial silver-alloy and nitric oxide-releasing methods, made to combat catheter-associated urinary tract infections (CAUTIs). Major medical device corporations, Teleflex, Coloplast, ConvaTec, and BD, own a large portfolio of these patents creating a competitive edge for them in the market.
Also, material inventions feature patents on hydrophilic and biodegradable catheter parts to augment biocompatibility and lessen detrimental impact on the environment. Patented smart catheters with IoT and sensor-based systems for monitoring VA catheter systems show the rising attraction to digital health integration in the urinary catheters sector.
Patent applications are still mostly made in North America, Europe, and Asia-Pacific seeing as these areas have advanced research and development infrastructures and regulatory climates. There is a gradual rise in patent applications in emerging markets as manufacturers look to protect local tailored innovations. All in all, the urinary catheter patent market is still highly competitive but strategically focuses on stand out technology while aiming for evolving clinical and patient needs.
Reimbursement Scenario
The worldwide market for urinary catheters is submerged in a reimbursement quagmire shaped by diverse coding systems, governing bodies, and insurance frameworks. In the United States, urinary catheters are reimbursed primarily under Medicare Part B as a Durable Medical Equipment. Urinary catheters are reimbursed as DME with rates between $1.20 to $25.00 per unit for intermittent, indwelling and external catheters.
Coverage necessitates medical necessity documentation, supplier enrollment, prior authorization for quantity limits which requires a declaration of need. Important reimbursement codes are HCPCS Level II A4338-A4358 for DME urinary catheters, and CPT codes 51701-51710 for the catheter insertion and management.
Medicaid coverage is state dependent, with about 38 states providing full reimbursement for catheters while some have limits with prior authorization. In Europe, reimbursement decisions are made by public health insurance systems and are influenced by the national health technology assessment bodies like NICE in the UK, G-BA in Germany, and HAS in France which directly affect catheter reimbursement.
Countries in the Asia Pacific such as Japan, China, and Australia have their reimbursement policies guided by their respective regulatory bodies PMDA, NMPA, and TGA. In summary, urinary catheter reimbursement is still spiraled in complexity and geographical disparities which restrict market access and adoption. This forces manufacturers to encounter countless regulations across different regions in order to have enduring coverage.
Prescribers’ Preference
Urinary catheter prescriber preferences are influenced by clinical effectiveness, patient safety, hospital policies, and patient-specific requires. Distinct group practitioners such as urologists, emergency medicine, rehab physicians, and family physicians follow specific patterns aligned to the stage of care and specific pathology.
Indwelling catheters such as Bard Lubricath® and Teleflex Rusch® Gold are used in acute care settings for postoperative drainage, critical care inotrope monitoring, and management of severe incontinence. Silicone Foley catheters are often used for short-term catheterization because of their biocompatibility.
Intermittent catheters are the most prescribed devices for patients with neurogenic bladder or chronic urinary retention. Urologists and rehabilitation physicians tend to favor products such as Coloplast SpeediCath® and Hollister VaPro® because of hydrophilic coatings which lowers urethral trauma, enhancing patient compliance.
For male incontinence, dementia, or patients with limited mobility, external catheters like Hollister InView® and Coloplast Conveen® are used in non-invasive, domiciliary settings. For recurrent infections, prescribers tend to use silver-alloy, or Bardex® I.C. and Arrow® Silver Soaker™ catheters, which are proven to reduce CAUTIs by 40 to 60%, and are often prescribed with antimicrobial coatings.
Market Concentration and Competitive Landscape
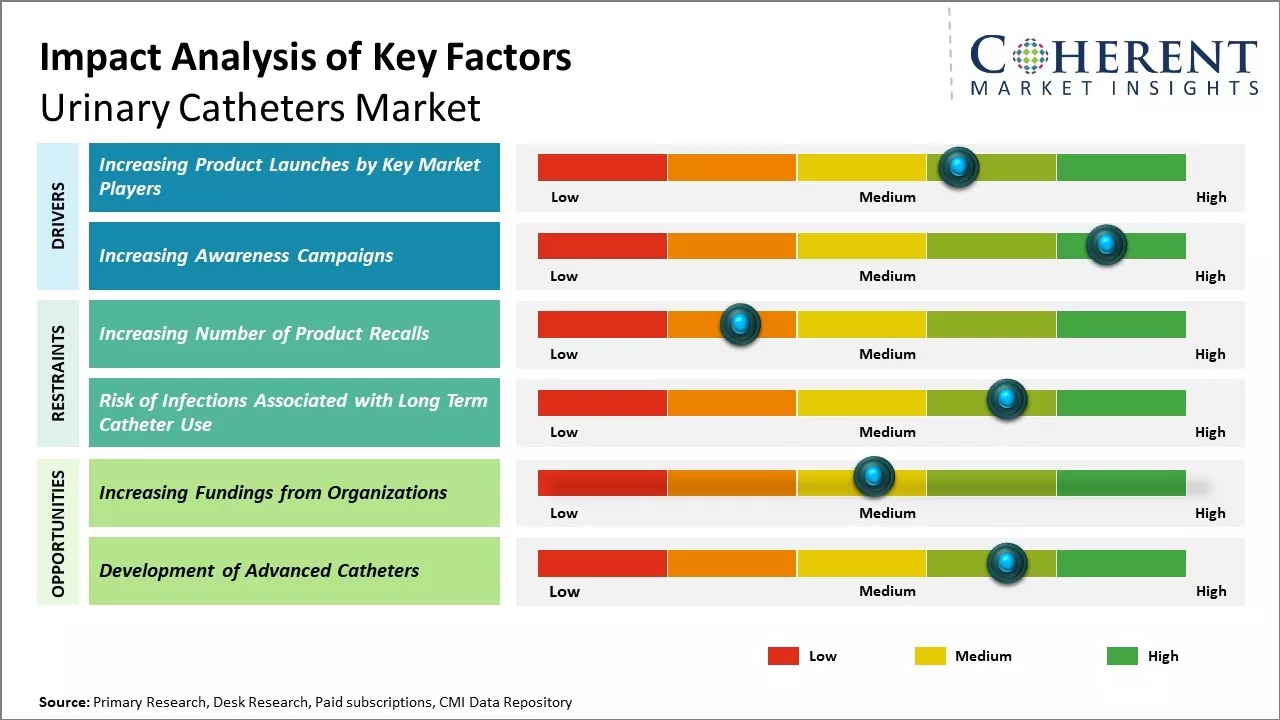
Increasing Product Launches by Key Market Players
Increasing adoption of organic growth strategies, such as product launches, by key market players is expected to drive the global urinary catheters market growth over the forecast period. For instance, in December 2021, Otsuka Pharmaceutical Factory, Inc., a healthcare company, announced that it had launched Actreen, an intermittent urological catheter, which is used during self-catheterization of patients who have lost the urge to urinate or usually have difficulty urinating.
Increasing Awareness Campaigns
Increasing initiatives taken by the market players in collaboration with government agencies by conducting awareness campaigns for the maintenance of women hygiene may act as a driver for the market growth over the forecast period.
For instance, in May 2022, Santex Products (Pvt.) Ltd., a female hygiene product offering company, and the United Nations Children's Fund (UNICEF), in collaboration with the School Education & Literacy Department, Government of Sindh, Pakistan, announced the launch of NoChuttiPlus campaign to educate adolescent girls about Menstrual Health and Hygiene (MHH), as risks associated with poor hygiene can directly affect reproductive health and cause urinary tract infections.
Market Challenges – Increasing Number of Product Recalls
Increasing number of product recalls by regulatory authorities, such as the U.S. Food and Drug Administration, is expected to hinder the market growth. For instance, in April 2020, the U.S. Food and Drug Administration recalled a class II device silicone foley catheter with a temperature sensor, which was manufactured by Covidien, a subsidiary of Medtronic, a medical device company. The device was recalled because the catheter failed to meet the established calibrated temperature sensing tolerance and correctly measure patient body temperatures that lead to an incorrect diagnosis and insufficient treatment.
Market Opportunities – Increasing Fundings from Organizations
Increasing adoption of inorganic growth strategies such as fundings is expected to offer lucrative growth opportunities in the market for the development of advanced urinary catheters. For instance, in August 2023, the Department of Biological Sciences at the University of Notre Dame, a private Catholic research university, Indiana, U.S. announced that it had been awarded funding from Open Philanthropy, a non-profit organization, for further development of a new type of urinary catheter that may reduce deaths from catheter-induced urinary tract infections (CAUTI).
Segmental Insights
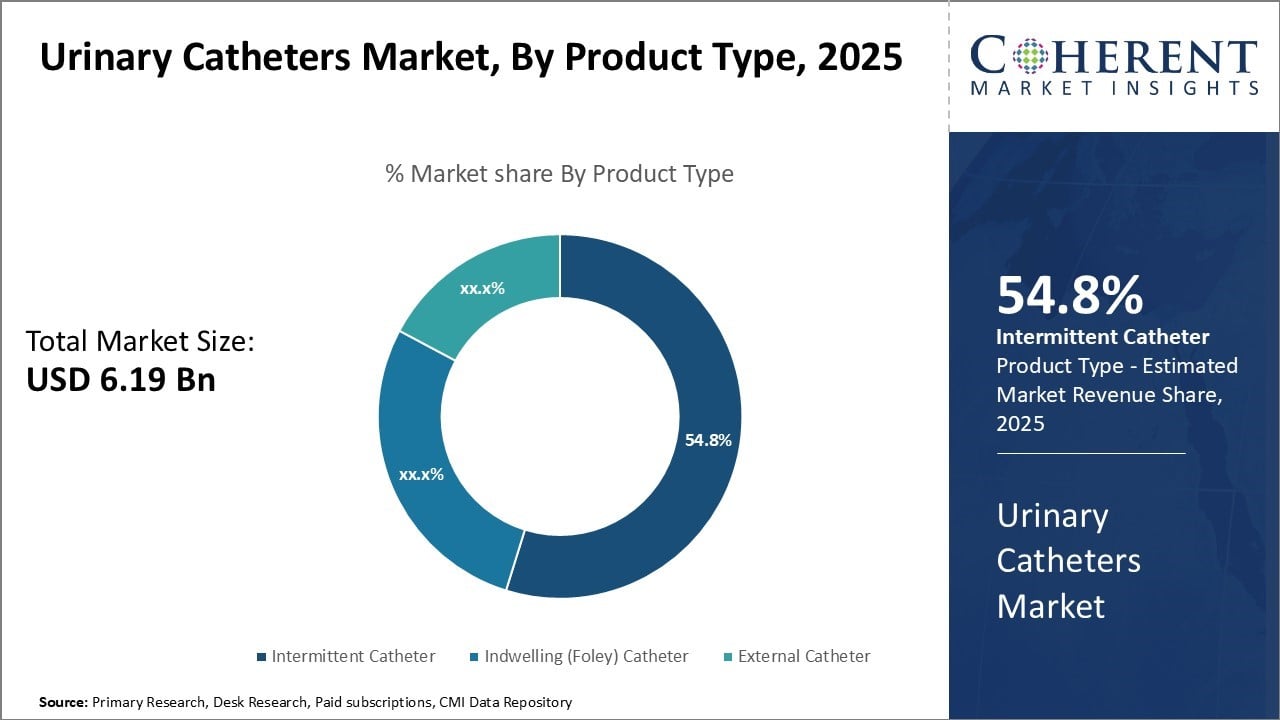
Global Urinary Catheters Market Insights, By Product Type
The product type segment includes intermittent catheter, indwelling (foley) catheter, and external catheter. The intermittent catheter sub-segment is estimated to hold 55.8% of the market share in 2026 owing to its convenience and cost-effectiveness compared to other product types.
Intermittent catheters allow flexible urination and do not require permanent insertion like an indwelling catheter. This makes intermittent catheters preferable for patients needing short-term catheterization. Their use is determined by the patient's urinary habits rather than being tied to a drainage bag continuously. This flexibility allows patients to lead relatively normal lifestyles.
From a cost perspective as well, intermittent catheters have a lower unit cost compared to indwelling catheters which require longer-term use and constant maintenance. Their single-use nature also eliminates risks of complications from long-term indwelling. The convenience and affordability factors, along with their non-invasiveness, make intermittent catheters highly attractive for patients requiring temporary relief from urinary problems.
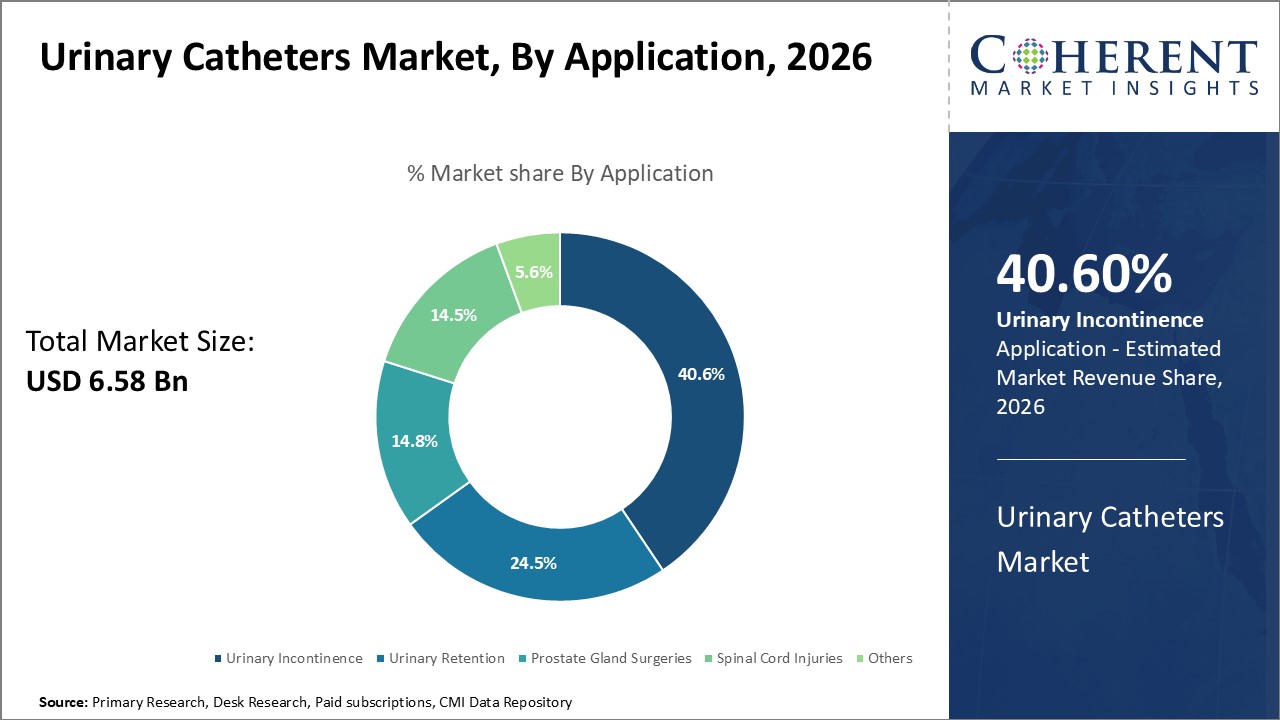
Global Urinary Catheters Market Insights, By Application
The application segment includes urinary incontinence, urinary retention, prostate gland surgeries, spinal cord injuries, and others. The urinary incontinence sub-segment is estimated to hold 40.6% of the market share in 2026 due to the growing burden of urinary incontinence. For instance, according to data published by American Urogynecologic Society, it was stated that the overall prevalence of urinary incontinence in adult U.S. women 20 years and older was 61.8%.
Urinary incontinence significantly impacts daily activities and social engagement of patients. If left untreated, it can lead to social isolation, depression and mobility issues. Catheters help regain independence and restore confidence for incontinent patients. Among all applications, urinary incontinence has wide scope for catheter usage given its association with aging, childbirth, obesity, and neurological disorders. Managing incontinence effectively is critical to uphold patients' dignity and improve their participation in social roles.
Global Urinary Catheters Market Insights, By End User
The end user segment includes hospitals, specialty clinics, ambulatory surgical centers, and others. The hospitals sub-segment is estimated to hold 44.2% of the market share in 2026 owing to their prominence in clinical excellence and enhanced access for patients. Being the preferred healthcare facilities for critical illnesses and injuries, hospitals witness high throughput of urological cases needing catheterization.
They are also increasingly focused on best practices to prevent healthcare-associated infections from improper catheter use. Furthermore, tertiary and quaternary hospital networks provide widespread coverage and role model clinical standards for other healthcare providers. This improves catheterization access for large patient volumes including those in remote areas.
Global Urinary Catheters Market - Regional Insights
North America Urinary Catheters Market Analysis and Trends
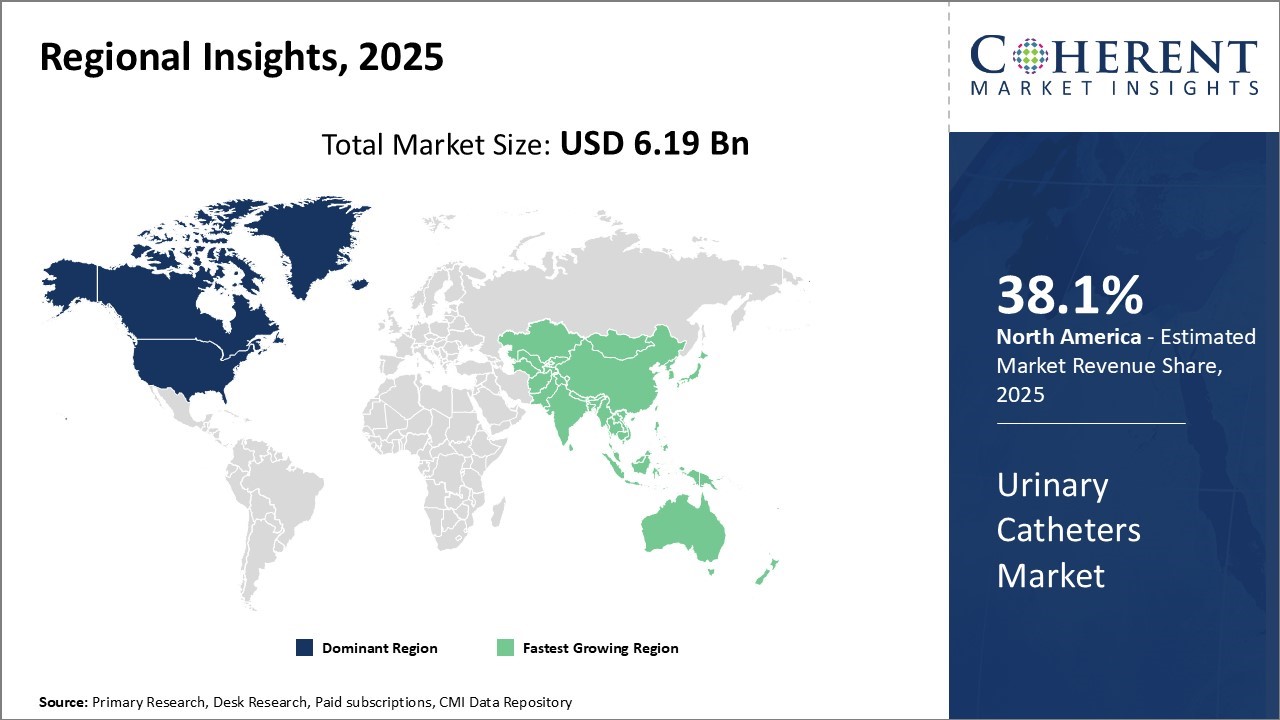
North America remains the dominant region in the global urinary catheters market, expected to hold around 38.1% of the market share by 2026. This leadership is fueled by the presence of major industry players and the region’s growing aging population, which drives demand for catheterization solutions.
The United States commands the largest share within North America, supported by a strong healthcare infrastructure, advanced catheter technologies, and favorable reimbursement policies that promote higher adoption rates. These factors collectively sustain steady market growth across the region.
Asia Pacific Urinary Catheters Market Analysis and Trends
The Asia Pacific (APAC) region is poised to be the fastest-growing market for urinary catheters over the forecast period. Rapid economic development, increasing healthcare investments, and expanding medical infrastructure in countries such as China, India, Japan, and South Korea are key growth drivers.
The rise in medical tourism and preference for cost-effective catheter devices further stimulate demand in the region. Additionally, the increasing prevalence of urinary disorders among the aging population is expected to accelerate catheter adoption, reinforcing APAC’s position as a dynamic and expanding market.
Dominating Countries in the Urinary Catheters Market
United States Urinary Catheters Market Analysis and Trends
The United States leads the North American market with its well-established healthcare ecosystem and advanced medical device manufacturing sector. The availability of cutting-edge urinary catheter technologies, combined with supportive reimbursement frameworks, fuels strong demand across hospitals, long-term care facilities, and outpatient settings.
China Urinary Catheters Market Analysis and Trends
China is a major growth driver in the Asia Pacific region, propelled by rising healthcare expenditures, rapid urbanization, and expanding geriatric demographics. Domestic manufacturers are innovating to meet the increasing need for affordable, high-quality urinary catheters.
India Urinary Catheters Market Analysis and Trends
India’s urinary catheters market is witnessing rapid growth due to improving healthcare infrastructure, increasing government initiatives to enhance urological care, and the rising prevalence of urinary disorders. Growing medical tourism is also a notable contributor to market expansion.
Japan Urinary Catheters Market Analysis and Trends
Japan’s aging population and sophisticated healthcare system support steady demand for advanced urinary catheter solutions. The country is investing in research and development, emphasizing minimally invasive and patient-friendly catheter technologies.
Market Report Scope
Urinary Catheters Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 6.58 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 6.3% | 2033 Value Projection: | USD 10.09 Bn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
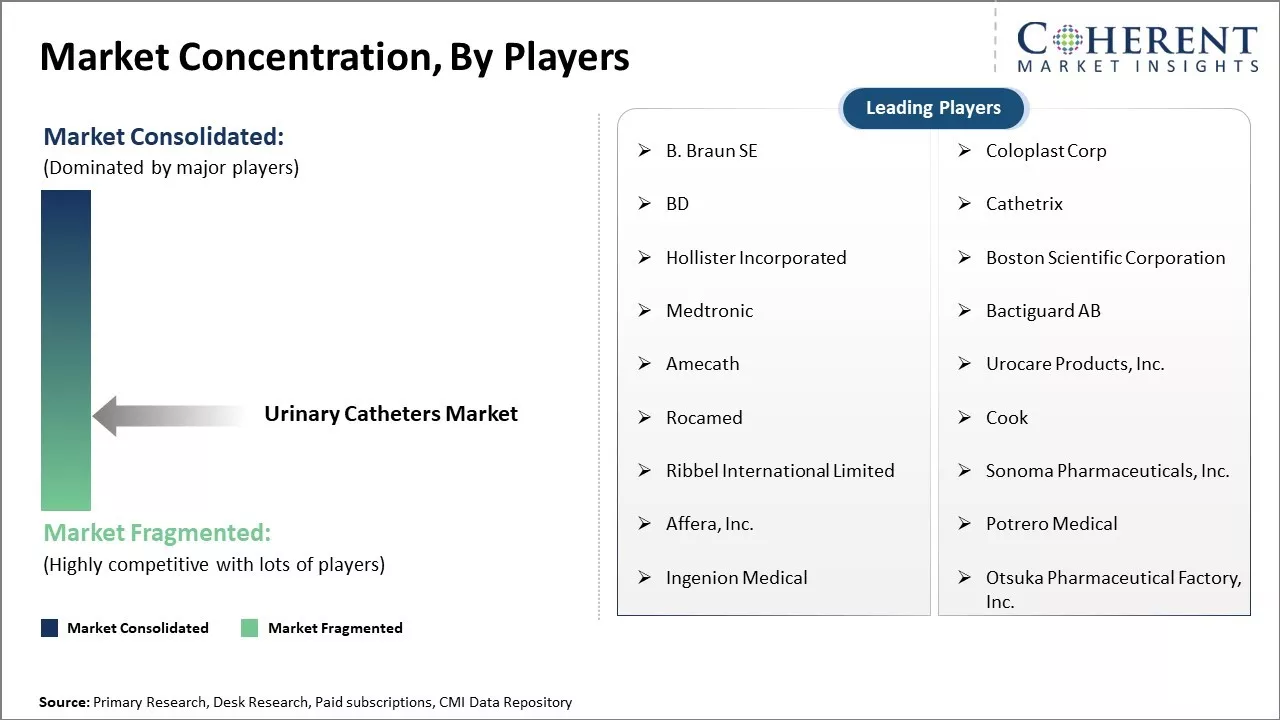
| Companies covered: | B. Braun SE, Coloplast Corp, BD, Cathetrix, Hollister Incorporated, Boston Scientific Corporation, Medtronic, Bactiguard AB, Amecath, Urocare Products, Inc., Rocamed, Cook, Ribbel International Limited, Sonoma Pharmaceuticals, Inc., Affera, Inc., Potrero Medical, Ingenion Medical, and Otsuka Pharmaceutical Factory, Inc. | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Analyst Viewpoint
- The market is underpinned by strong fundamentals, primarily driven by the global aging population with increased incidences of urinary incontinence, bladder dysfunction, and surgeries requiring catheter use.
- Rising prevalence of chronic diseases such as diabetes, neurological disorders, and spinal cord injuries further fuels demand across diverse healthcare settings.
- Advances in catheter technology — including antimicrobial coatings and hydrophilic materials — are improving patient comfort and reducing infection risks, boosting adoption among clinicians.
- The shift towards home healthcare and patient preference for self-catheterization, especially intermittent catheters, is opening new growth avenues.
- Key challenges include catheter-associated urinary tract infections (CAUTIs), which contribute to higher healthcare costs and complications.
- Regulatory complexities and reimbursement hurdles in certain regions limit market penetration.
- North America currently leads the market due to its advanced healthcare infrastructure, favorable reimbursement frameworks, and high disease awareness.
- Asia-Pacific is the fastest-growing region, supported by improving healthcare access, rising disposable incomes, and aging populations in countries such as China and India.
- The outlook remains optimistic with growth prospects tied to minimally invasive catheter technologies, expanded outpatient applications, and increased healthcare spending in emerging markets.
- Strategic growth for manufacturers will depend on innovation, regulatory navigation, and expanding presence in emerging economies.
Urinary Catheters Market Key Developments
- In June 2023, Convatec Inc., a medical device company, announced the launch of GentleCath Air, a new compact intermittent catheter for women, which is designed for ultimate discretion, convenience, and comfort.
- In February, 2023, Coloplast Corp, a global healthcare company, announced that it had launched new intermittent catheter, Luja, which is designed to reduce the risk of urinary tract infections.
- In July 2022, Otsuka Pharmaceutical Factory, Inc., a pharmaceutical company, announced the launch of OT-Balloon Catheter, an intermittent urological catheter. OT-Balloon Catheter is a reusable catheter for use during self-catheterization for people who have difficulty urinating spontaneously for various reasons. The catheter is temporarily implanted in the bladder by inflating the balloon at the tip of the catheter during the night or when going out.
- In March 2022, Sonoma Pharmaceuticals, Inc., a pharmaceutical company, announced that it had launched Microdox, a urinary tract infection catheter and bladder rinse in New Zealand, Australia, and South Africa. Microdox is a super-oxidized solution technology intended to treat and prevent infections in the urinary tract and bladder.
Market Segmentation
- Product Type Insights (Revenue, USD Bn, 2021 - 2033)
- Intermittent Catheter
- Ported Peripheral Intravenous Catheters (PIVC)
- Non-Ported Peripheral Intravenous Catheters (PIVC)
- Indwelling (Foley) Catheter
- External Catheter
- Application Insights (Revenue, USD Bn, 2021 - 2033)
- Urinary Incontinence
- Urinary Retention
- Prostate Gland Surgeries
- Spinal Cord Injuries
- Others
- End User Insights (Revenue, USD Bn, 2021 - 2033)
- Hospitals
- Specialty Clinics
- Ambulatory Surgical Centers
- Others
- Regional Insights (Revenue, USD Bn, 2021 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC Countries
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
- Key Players Insights
- B. Braun SE
- Coloplast Corp
- BD
- Cathetrix
- Hollister Incorporated
- Boston Scientific Corporation
- Medtronic
- Bactiguard AB
- Amecath
- Urocare Products, Inc.
- Rocamed
- Cook
- Ribbel International Limited
- Sonoma Pharmaceuticals, Inc.
- Affera, Inc.
- Potrero Medical
- Ingenion Medical
- Otsuka Pharmaceutical Factory, Inc.
Sources
Primary Research Interviews
- Medical Device Manufacturers and Key Players
- Healthcare Professionals and Urologists
- Hospital Procurement Managers
- Distributors and Supply Chain Partners
- Others
Databases
- Healthcare Market Research Database (BMI Research)
- Medical Device Intelligence Database
- Global Health Observatory (WHO)
- FDA Medical Device Database
- Others
Magazines
- Medical Device & Diagnostic Industry (MD+DI)
- Healthcare Purchasing News
- Urology Times Magazine
- Medical Product Outsourcing Magazine
- Others
Journals
- Journal of Urology
- International Urogynecology Journal
- Neurourology and Urodynamics
- Others
Newspapers
- Healthcare Finance News
- Modern Healthcare
- Fierce Healthcare
- Medical Device Network
- Others
Associations
- American Urological Association (AUA)
- Society of Urologic Nurses and Associates (SUNA)
- International Continence Society (ICS)
- Medical Device Manufacturers Association (MDMA)
- Others
Public Domain Sources
- Centers for Disease Control and Prevention (CDC)
- World Health Organization (WHO)
- U.S. Food and Drug Administration (FDA)
- European Medicines Agency (EMA)
- Others
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of information for last 8 years
*Definition: A urinary catheter is a hollow, partially flexible tube that collects urine from the bladder and leads to a drainage bag. Urinary catheters come in many sizes and types. Catheters are made from rubber and non-rubber materials such as silicone. It is important to use the correct type of catheter and a non-rubber catheter is used if one is allergic to latex. A urinary catheter is used when an individual is having problems urinating naturally. It allows the individual or patient to urinate and drain while having an obstruction in the tube that carries urine out of the bladder (urethra).
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Urinary Catheters Market size is estimated to be valued at USD 6.58 Bn in 2026, and is expected to reach USD 10.09 Bn by 2033.
The CAGR of the global Market is projected to be 6.3% from 2026 to 2033.
Increasing product launches by key market players and increasing awareness campaigns are the major factors driving the growth of the urinary catheters industry.
Increasing number of product recalls and risk of infections associated with long term catheter use are the major factors hampering the growth of the global market.
In terms of product type, intermittent catheter is estimated to dominate the market revenue share in 2026.
Braun SE, Coloplast Corp, BD, Cathetrix, Hollister Incorporated, Boston Scientific Corporation, Medtronic, Bactiguard AB, Amecath, Urocare Products, Inc., Rocamed, Cook, Ribbel International Limited, Sonoma Pharmaceuticals, Inc., Affera, Inc., Potrero Medical, Ingenion Medical, and Otsuka Pharmaceutical Factory, Inc. are the major players.
North America is expected to lead the global market.