

Gastric Motility Disorder Drug Market Size and Forecast — 2026-2033
The gastric motility disorder drug market is estimated to be valued at USD 64.41 Bn in 2026 and is expected to reach USD 95.58 Bn by 2033, exhibiting a compound annual growth rate (CAGR) of 5.8% from 2026 to 2033.
 The market is experiencing positive growth due to the increasing prevalence of gastric motility disorders worldwide. Various factors such as the growing geriatric population, changing lifestyle habits, and dietary changes are contributing to the rising cases of gastric disorders. Moreover, the ongoing development of novel and advanced drugs for the treatment of gastric motility disorders is further supporting the market growth. However, the expiry of patents of major drugs and stringent regulations for drug approval may hamper the market growth during the forecast period.
Rising incidence of gastric disorders
The global prevalence of gastric motility disorders has been increasing steadily over the past few decades. Various factors such as changing lifestyle patterns, unhealthy diets, and higher levels of stress have significantly contributed to the rising incidence of gastric issues across both developing and developed regions. People are leading increasingly hurried and stressful lives which is negatively impacting the functioning of their digestive system. Additionally, certain medical conditions like diabetes, neurological disorders, and gastric surgeries can predispose patients to developing gastric motility dysfunction over time. The growing patient pool of chronic gastric disorders indicates a growing need for more effective treatment options. Currently available medications are often found to produce unsatisfactory results or come with intolerable side-effects in many cases.
Insights, By Disorder Type
 Insights, By Disorder Type: Insufficient Digestive Enzymes Trigger Upper Tract Issues, Thus Driving the Segment Growth
The disorder type segment includes upper digestive tract and lower digestive tract. The upper digestive tract segment is estimated to hold 59.4% share of the market in 2026. The upper digestive tract, consisting of the esophagus, stomach, and small intestine, requires robust enzymatic function to properly break down food and facilitate stomach emptying. However, for various reasons, such as age, diet, stress, and underlying conditions, some individuals have impaired enzyme secretion. With incomplete digestion, contents move through the upper tract too quickly. Undigested particles then irritate and cause inflammation in the delicate lining over time. Symptoms like heartburn, nausea, vomiting, abdominal pain, and bloating develop. Proton pump inhibitors and H2 blockers provide relief by reducing stomach acid. However, addressing the root cause of insufficient enzymes can help manage upper tract issues more effectively in the long run. Focusing treatments on enhancing pancreatic enzyme output can aid complete breakdown and prevent the recurrence of discomfort.
Insights, By Drug Class
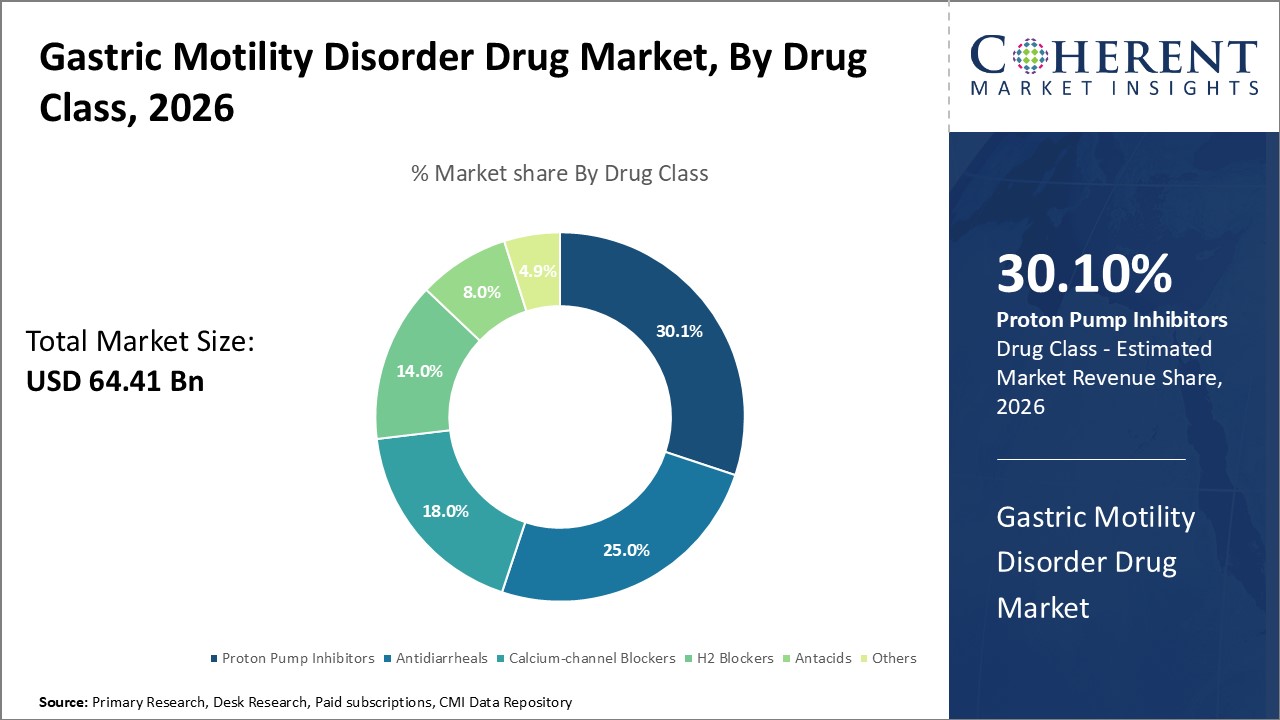
Insights, By Drug Class: Strong efficacy drives proton pump inhibitors segment growth
The drug class segment includes antacids, antidiarrheals, calcium-channel blockers, H2 blockers, proton pump inhibitors, and others. The proton pump inhibitors sub-segment is expected to account for 30.1% of the market share in 2026. Proton pump inhibitors work by blocking the final step in stomach acid production, significantly reducing the amount of acid secreted by stomach parietal cells. Their strong efficacy at relieving symptoms such as heartburn, acid reflux, and ulcers has made them the standard first line treatment recommended by organizations such as the National Health Service and World Gastroenterology Organization. Notable proton pump inhibitors include omeprazole, esomeprazole, lansoprazole, rabeprazole, and pantoprazole which are widely available internationally as both prescription and over-the-counter medications. Meanwhile, H2 blockers represent the fastest growing drug class segment within this market. H2 blockers function by reversibly blocking histamine receptors on parietal cells in the stomach, reducing stomach acid production. While not as potent as proton pump inhibitors, H2 blockers provide effective relief for mild to moderate gastric issues and have lesser side effect risk.
Insights, By Distribution Channel
Insights, By Distribution Channel: Convenience Cements Retail Pharmacy Dominance
The distribution channel segment includes hospital pharmacies, retail pharmacies, and online pharmacies. The retail pharmacies sub-segment is expected to hold 40.7% of the market share in 2026. Most retail pharmacy chains operate thousands of stores nationwide with long operating hours for 7 days a week. This omnipresent physical access means customers can simply walk in anytime to purchase medications advised by a doctor or for minor self-care issues. Fast service counter, self-check-out machines, drive-through, and home delivery options cater to immediate health needs efficiently. Pharmacists also provide prescription counseling as first line healthcare professionals. Buying digestive aid drugs from familiar retail faces reduces discomfort over sharing personal symptoms online or waiting to see a doctor. Household budget allotted for pharmacy co-pays also facilitates consistent treatment adherence within allocated healthcare spending. The extensive brick-and-mortar footprint firmly cements retail pharmacies as the dominant gastric motility disorder drug distribution mode.
Regional Insights
 North America has established itself as the dominant region in the gastric motility disorder drug market and is projected to hold 38.4% of the market share in 2026. The large pharmaceutical industry presence and stringent regulations have created a strong culture of clinical research and drug development in the U.S. Major drug manufacturers have set up their headquarters and research centers in the country, driving significant investments into developing novel therapies. Furthermore, the higher healthcare spending and adoption of advanced drugs have supported the market growth over the years.
Asia Pacific has emerged as the fastest growing regional market. The rising geriatric population and growing cases of functional gastrointestinal disorders like gastroparesis have fueled the demand. Countries like China and India are focusing on enhancing local manufacturing capabilities through pharmaceutical industry incentives and reforms. This has attracted Western companies to collaborate with domestic players to tap into the lucrative market opportunities. Several global pharmaceutical companies have established manufacturing facilities and distribution networks in Asia Pacific to strengthen their regional market position.
Market Players, Key Development, and Competitive Intelligence
 Ageing global population
Another important driver for the gastric motility drug market is the steadily ageing population worldwide. Advances in public healthcare have contributed to increased life expectancy which means the proportion of elderly individuals is growing in most countries and regions. This phenomenon has significant implications for the healthcare industry since the risk of developing gastric motility issues rises considerably with age. The elderly tend to experience higher rates of comorbidities like Parkinson's disease, diabetes, and arthritis - all of which can potentially impair normal stomach function over time. Age-related decline in lean muscle mass and immunity also renders older patients more prone to experiencing gastric emptying problems, nausea, vomiting, and discomfort after meals.
Key Developments
- On February 12, 2024, Takeda, a pharmaceutical company stated that the U.S. Food and Drug Administration (FDA) has approved EOHILIA (budesonide oral suspension), the first and only U.S. FDA-approved oral treatment for persons aged 11 and above with eosinophilic esophagitis (EoE).1 It will be accessible in convenient single-dose stick packs with 2 mg/10 mL by the end of February 2024.
- In December 2023, Vanda Pharmaceuticals Inc., a pharmaceutical company, stated that the U.S. FDA has accepted Vanda Pharmaceuticals Inc.’s New Drug Application (NDA) for tradipitant to treat gastroparesis symptoms. The U.S. FDA has established September 18, 2024 as the target deadline for its determination under the Prescription Drug User Fee Act (PDUFA).
- In April 2022, Ardelyx, Inc., a biopharmaceutical company founded with the mission of discovering, developing, and commercializing innovative first-in-class medicines that address significant unmet medical needs, announced the launch of IBSRELA, the first and only NHE3 inhibitor for the treatment of irritable bowel syndrome with constipation (IBS-C) in adults. IBSRELA is Ardelyx's first U.S. FDA-approved product.
- In February 2022, Evoke Pharma, Inc., a specialty pharmaceutical company, and EVERSANA Life Science Service LLC, an independent provider of global commercial services, extended their agreement to collaborate on the commercialization and distribution of Gimoti (metoclopramide) nasal spray in the U.S. until the end of 2026. Gimoti remains the most unique product for treating diabetic gastroparesis symptoms.
*Definition: The gastric motility disorder drug market involves pharmaceutical products that treat various gastric motility disorders like gastroparesis, gastroesophageal reflux disease, uncoordinated contractions of stomach muscles, and other conditions where stomach movements are disrupted. These drugs aim to improve stomach movement and emptying by regulating gastrointestinal hormones, stimulating stomach muscles, reducing acid production, and providing other relief from symptoms caused by improper stomach functioning.
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Market Report Scope
Gastric Motility Disorder Drug Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 64.41 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 5.8% | 2033 Value Projection: | USD 95.58 Bn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | Pfizer Inc., Takeda Pharmaceutical Company Limited, Janssen Pharmaceuticals, Sun Pharmaceutical Industries Ltd., AbbVie Inc., Boehringer Ingelheim, Eli Lilly and Company, Bristol Myers Squibb, Daiichi Sankyo Company, Limited, Bausch Health Companies, Mallinckrodt Pharmaceuticals, Endo Pharmaceuticals, Eisai Co., Ltd., Ferring Pharmaceuticals, UCB, Evoke Pharma, and Cadila Pharmaceuticals | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Analyst Opinion (Expert Opinion)
 Market Challenges – Limited treatment efficacy of existing drugs
The gastric motility disorder drug market faces several challenges. The lack of curative options and limited treatment efficacy of existing drugs is a major concern. Patients often experience various side effects from long-term medication usage. Additionally, the mechanisms underlying many gastric motility disorders are not fully understood yet, making drug development a complex process. Narrow markets for orphan drugs and lack of symptomatic diagnostic tools also hamper the commercialization of new treatment offerings.
Market Opportunities – Increase in research and development activities
The market presents attractive opportunities for companies willing to invest in research and development. With increasing awareness about gastrointestinal disorders, the demand for advanced treatment solutions is growing. Emerging technologies like drug delivery using gastric retainable systems can help overcome issues with poor drug absorption and retention. There is scope for the development of novel drugs targeting specific pathologies.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- Disorder Type Insights (Revenue, USD BN, 2021 - 2033)
- Upper Digestive Tract
- Achalasia
- Gastroesophageal Reflux Disease (GERD)
- Gastroparesis
- Dumping Syndrome
- Lower Digestive Tract
- Intestinal Pseudo-obstruction
- Small Intestinal Bacterial Overgrowth (SIBO)
- Pelvic Dyssynergia
- Hirschsprung’s Disease
- Upper Digestive Tract
- Drug Class Insights (Revenue, USD BN, 2021 - 2033)
- Antacids
- Antidiarrheals
- Calcium-channel Blockers
- H2 Blockers
- Proton Pump Inhibitors
- Others
- Distribution Channel Insights (Revenue, USD BN, 2021 - 2033)
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Regional Insights (Revenue, USD BN, 2021 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC Countries
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
- North America
- Key Players Insights
- Pfizer Inc.
- Takeda Pharmaceutical Company Limited
- Janssen Pharmaceuticals
- Sun Pharmaceutical Industries Ltd.
- AbbVie Inc.
- Boehringer Ingelheim
- Eli Lilly and Company
- Bristol Myers Squibb
- Daiichi Sankyo Company, Limited
- Bausch Health Companies
- Mallinckrodt Pharmaceuticals
- Endo Pharmaceuticals
- Eisai Co., Ltd.
- Ferring Pharmaceuticals
- UCB
- Evoke Pharma
- Cadila Pharmaceuticals
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Gastric Motility Disorder Drug Market is estimated to be valued at USD 64.41 Bn in 2026, and is expected to reach USD 95.58 Bn by 2033.
The CAGR of the Gastric Motility Disorder Drug Market is projected to be 5.8% from 2026 to 2033.
Rising incidence of gastric disorders and ageing global population are the major factors driving the growth of the gastric motility disorder drug market.
Limited treatment efficacy of existing drugs and high cost of treatment are the major factors hampering the growth of the gastric motility disorder drug market.
In terms of disorder type, upper digestive tract is estimated to dominate the market revenue share in 2026.
Pfizer Inc., Takeda Pharmaceutical Company Limited, Janssen Pharmaceuticals, Sun Pharmaceutical Industries Ltd., AbbVie Inc., Boehringer Ingelheim, Eli Lilly and Company, Bristol Myers Squibb, Daiichi Sankyo Company, Limited, Bausch Health Companies, Mallinckrodt Pharmaceuticals, Endo Pharmaceuticals, Eisai Co., Ltd., Ferring Pharmaceuticals, UCB, Evoke Pharma, and Cadila Pharmaceuticals are the major players.
North America is expected to lead the gastric motility disorder drug market.