

Cell Therapy Manufacturing Market Size and Forecast — 2026-2033
Global cell therapy manufacturing market is estimated to be valued at USD 6.51 Bn in 2026 and is expected to reach USD 17.65 Bn by 2033, exhibiting a compound annual growth rate (CAGR) of 15.3% from 2026 to 2033.
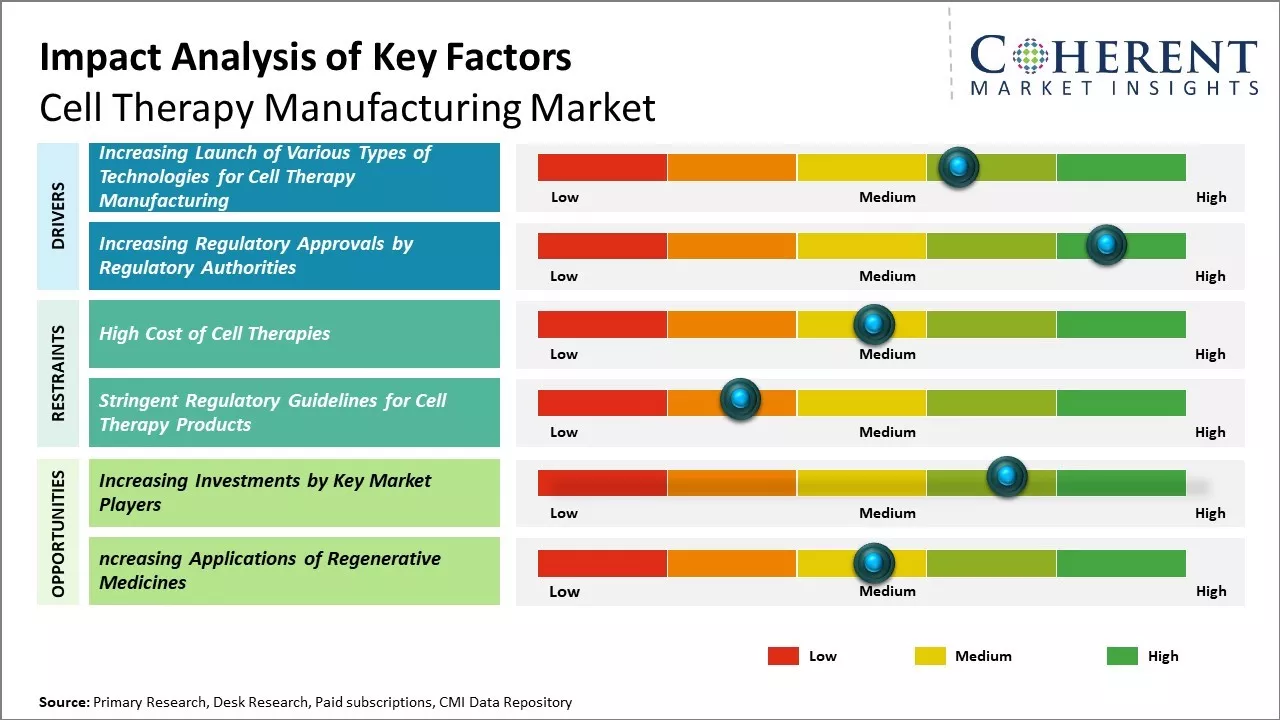 Increasing prevalence of chronic diseases such as cancer and cardiovascular diseases boosts demand for cell therapy products across the world. The advancements in cell therapy research and development and rise in the number of clinical trials are driving the market growth. Various market players are constantly focused on developing innovative cell therapy products, in order to expand their market share. Regulatory complexity and high costs involved can hamper the growth of the cell therapy manufacturing market.
Increasing Launch of Various Types of Technologies for Cell Therapy Manufacturing
Manufacturers are involved in developing and launching various types of technologies for cell therapy manufacturing, and this is expected to drive the growth of global cell therapy manufacturing market. For instance, in July 2022, INVETECH, a global company offering solutions, systems, and services to cell and gene therapy, announced the launch of new korus technology for autologous cell therapy production. Korus is a closed system for the production of autologous cell therapy.
Insights, By Therapy Type
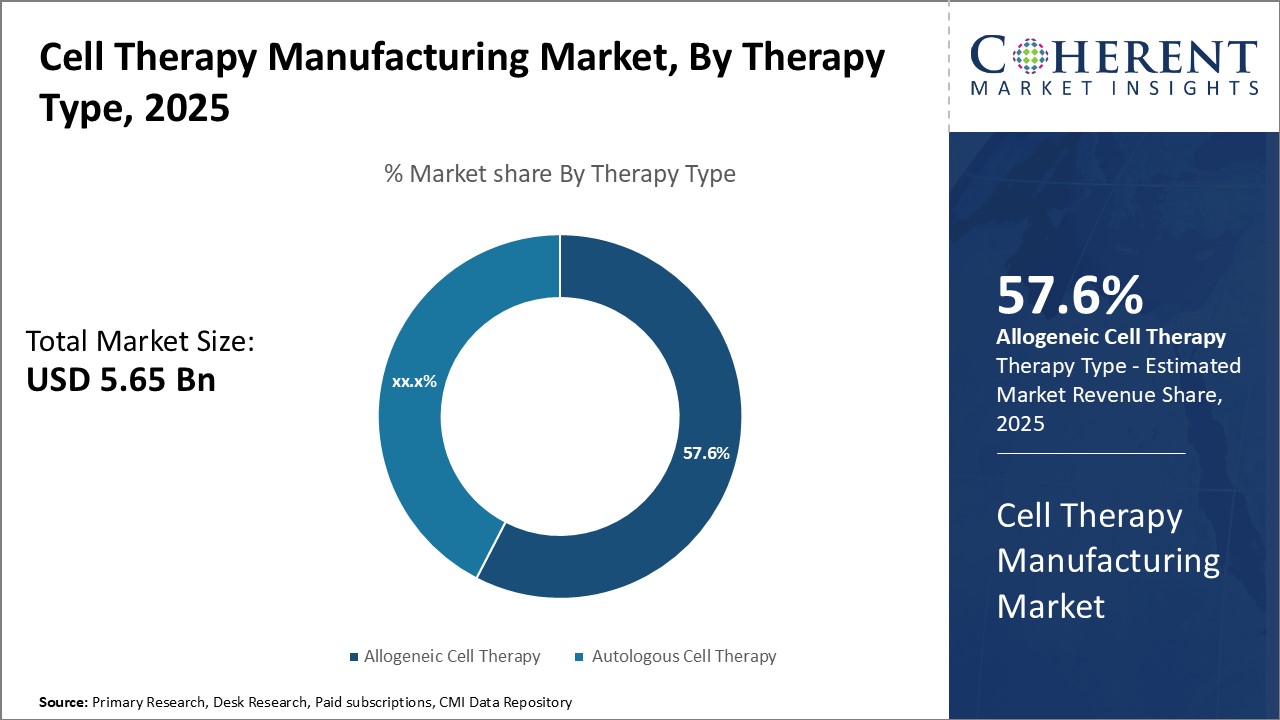 Insights, By Therapy Type: Immunological compatibility drives the growth of allogeneic cell therapy segment
Therapy Type segment is sub-segmented into allogeneic cell therapy and autologous cell therapy. Allogeneic cell therapy sub-segment is estimated to hold 58.6% of the market share in 2026 due to its immunological compatibility advantages over autologous therapies. Allogeneic cell therapy involves the use of donor cells that are not genetically identical to the recipient. With allogeneic cell therapies, large batches of unmodified donor cells can be mass produced in advance and stored for immediate off-the-shelf use by multiple patients. This efficient production process and immediacy of treatment provides significant advantages over customized autologous therapies.
Insights, By Manufacturing Purpose
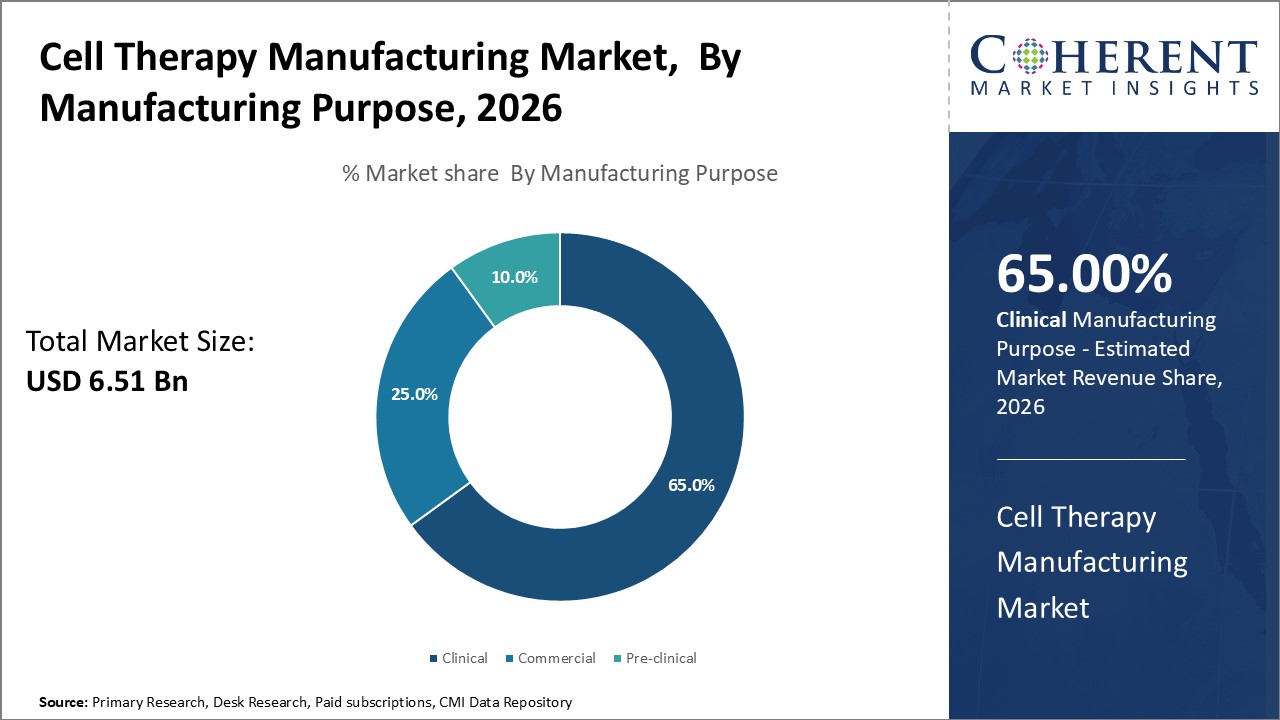
Insights, By Manufacturing Purpose: Regenerative medicine drives growth of clinical manufacturing uses
Manufacturing Purpose segment is sub-segmented into clinical, commercial, pre-clinical. The clinical sub-segment is estimated to hold 65% of the market share in 2026 due to the expanding applications of these therapies for regenerative medicine. The clinical manufacturing of cell therapies primarily serves research and trials focused on exploring the regenerative potential of cell treatments for various diseases. A major factor driving the clinical manufacturing segment is the growing body of evidence demonstrating the ability of cell therapies to reverse tissue damage, regenerate lost cells and structures, relieve symptoms, and potentially cure certain conditions. Promising clinical results have been shown for cell therapies applied to regenerate tissues affected by cardiovascular disease, neurological disorders, musculoskeletal injuries, and other degenerative conditions. The ability of cells like mesenchymal stem cells to differentiate into tissues like bone, cartilage, heart muscle and nerve cells underlies their therapeutic regenerative functions. Optimism around the continued progress and commercialization of new regenerative applications is sustaining strong investment in the clinical manufacturing of cell therapy products.
Insights, By Application
Insights, By Application: Increasing launch of joint venture for oncology
Application segment is sub-segmented into musculoskeletal, cardiovascular, gastrointestinal, neurological, oncology, dermatology, others. Oncology sub-segment is estimated to hold 34.6% of the market share in 2026 due to increasing launch of joint venture for oncology. For instance, in June 2022, the University of Texas MD Anderson Cancer Center and National Resilience, Inc., a biotechnology company, announced the launch of a joint venture, the Cell Therapy Manufacturing Center (CTMC), to accelerate the development and manufacturing of innovative cell therapies for patients with cancer.
Regional Insights
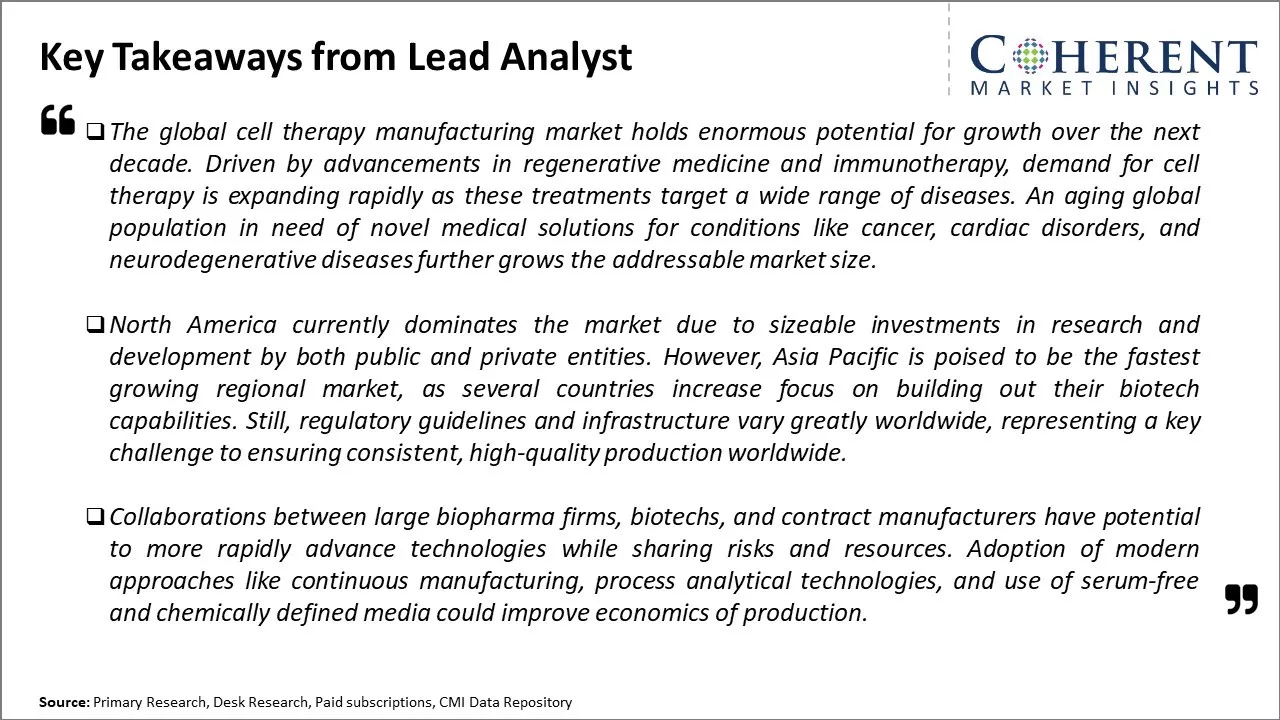
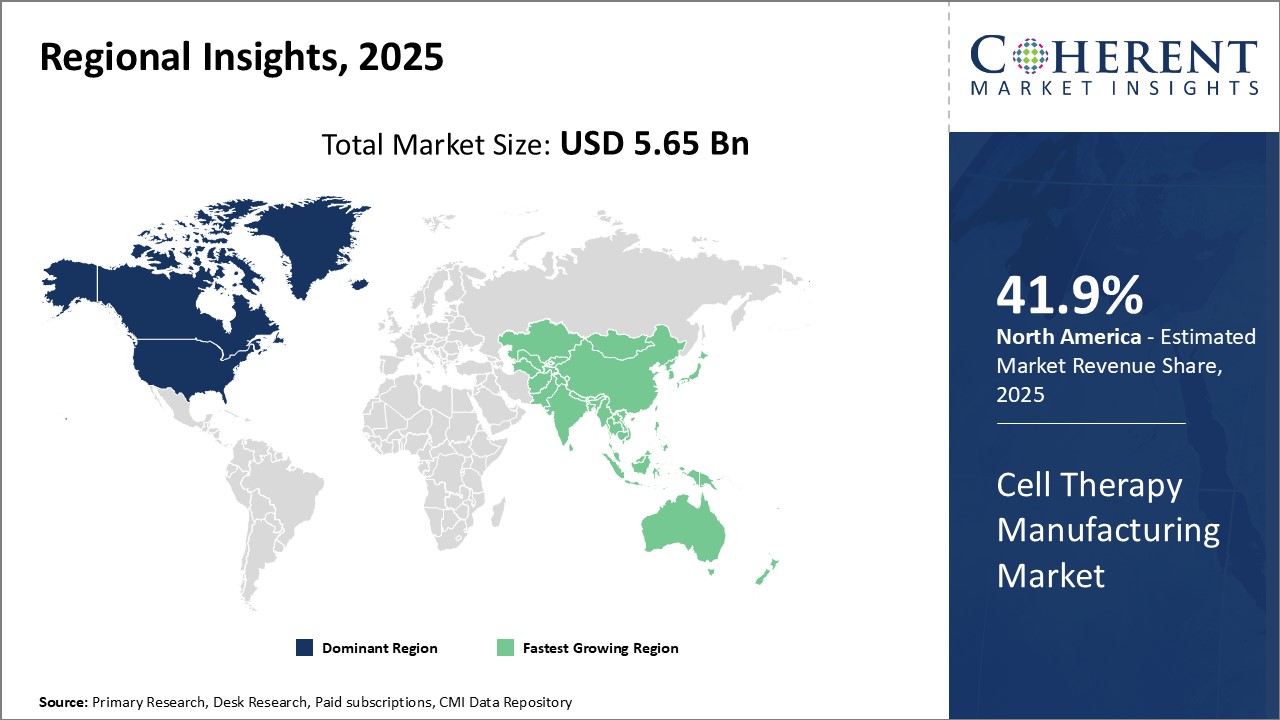 North America remains the dominant region in the global cell therapy manufacturing market and is estimated to hold 41.9% of the market share in 2026. The presence of leading biopharmaceutical companies and research institutions focused on cell therapies has fueled extensive research and development activities in the region. Countries like the U.S. have supportive regulations and reimbursement policies spurring clinical trials and commercialization of new cell therapy products. Access to capital for funding clinical trials along with increasing healthcare expenditure provides North American players an advantage. Several major players have set up their manufacturing facilities in the U.S. to cater to the large patient pool and tap into the growing demand. Over the years, these have built capabilities across the manufacturing value chain from cell sourcing and processing to final drug product formulation, storage, and distribution.
Asia Pacific has emerged as the fastest-growing regional market for cell therapy manufacturing. Countries like China and Japan recognize the potential of cell-based therapies, and are aggressively supporting industry growth. Their governments provide funding and infrastructure development initiatives to develop domestic capabilities. Lower operating costs and talent availability in the regions are attracting investments from global industry players seeking to expand production footprints. Local companies in Asia have ramped up technology innovations centered around process intensification. The rapid economic growth across Asia Pacific translates to increased healthcare spending and demand for advanced treatment options like cell therapies. This makes the region an attractive long-term investment destination for both regional as well as global manufacturers.
Market Players, Key Development, and Competitive Intelligence
 Increasing Regulatory Approvals by Regulatory Authorities
Manufacturers of cell therapy product are focusing on receiving regulatory approvals to enhance their cell therapy manufacturing process, and this is expected to drive the global cell therapy manufacturing market growth. For instance, in May 2022, Bristol Myers Squibb Company, a pharmaceutical company, announced that the U.S. Food and Drug Administration had approved Breyanzi (lisocabtagene maraleucel; liso-cel), a CD19-directed chimeric antigen receptor (CAR) T cell therapy, for the treatment of adult patients with relapsed or refractory chronic lymphocytic leukemia (CLL) or small lymphocytic lymphoma (SLL).
Key Developments
- In October 2023, Bayer AG, a pharmaceutical company, announced the opening of its first Cell Therapy Launch Facility in Berkeley, California, U.S. to create the capacity to bring cell therapies to patients on a global scale
- In May 2020, Takara Bio Inc., a biotechnology company, launched a new facility- the Center for Gene and Cell Therapy Processing II (CGCPII) in Shiga, Japan
*Definition: Cell therapy is the transplantation of human cells to replace or repair damaged tissue or cells. Numerous different types of cells may be used as part of a therapy or treatment for a number of diseases and disorders with the help of new technologies, inventive products, and infinite imagination. Hematopoietic (blood-forming) stem cells (HSC), skeletal muscle stem cells, mesenchymal stem cells, lymphocytes, dendritic cells, and pancreatic islet cells are a few of the cells that could be used.
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Market Report Scope
Cell Therapy Manufacturing Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 6.51 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 15.3% | 2033 Value Projection: | USD 17.65 Bn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
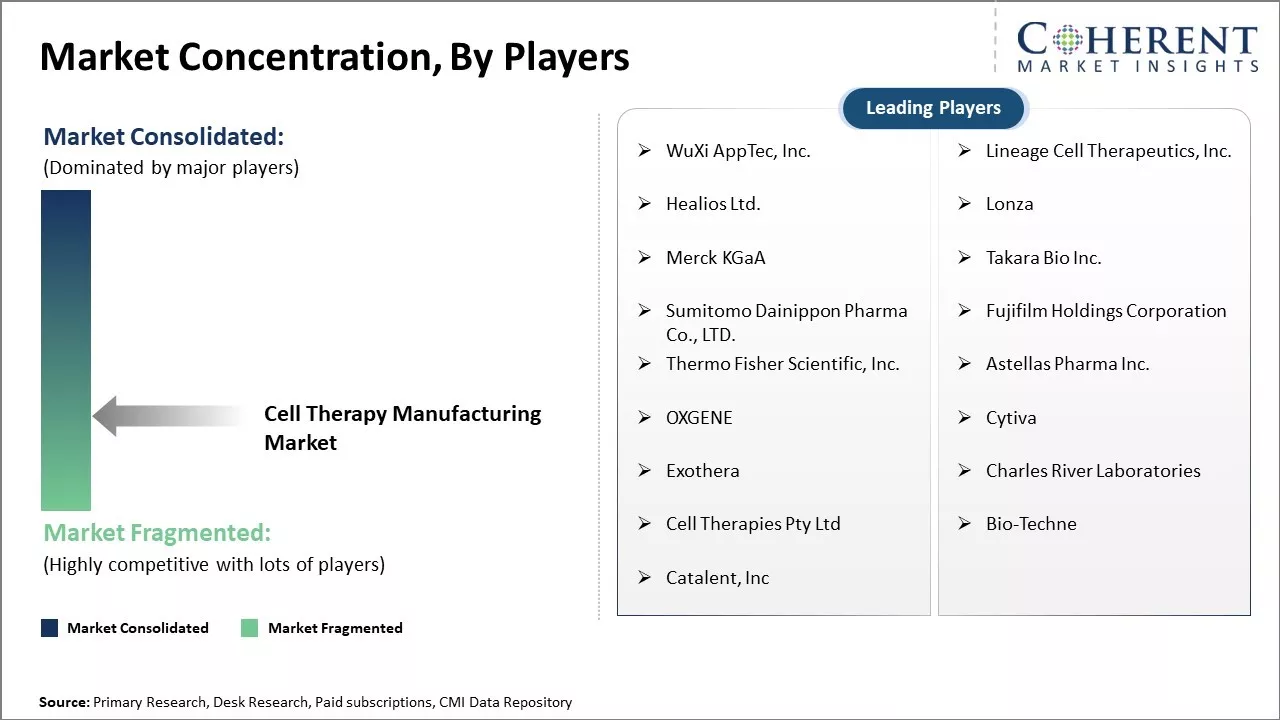
| Companies covered: | WuXi AppTec, Inc., Lineage Cell Therapeutics, Inc., Healios Ltd., Lonza , Merck KGaA, Takara Bio Inc., Sumitomo Dainippon Pharma Co., LTD., Fujifilm Holdings Corporation, Thermo Fisher Scientific, Inc., Astellas Pharma Inc., OXGENE, Cytiva, Exothera, Charles River Laboratories, Cell Therapies Pty Ltd, Bio-Techne, Catalent, Inc | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Analyst Opinion (Expert Opinion)
 Market Challenge – High Cost of Cell Therapies
High cost of cell therapies is one of the biggest challenges, with financial implications for patients, payers, and providers, and this is expected to hamper the market growth over the forecast period. For instance, in May 2022, chimeric antigen receptor (CAR) T-cell therapy tisagenlecleucel (Kymriah) received the U.S. FDA approval for the treatment of pediatric and young adult patients with relapsed or refractory B-cell precursor acute lymphoblastic leukemia (ALL).It costs around US$ 475,000 for a single infusion. This has resulted in limited adoption of such therapies, thus, hampering growth of the market. Moreover, in April 2022, Yescarta, a cell therapy, developed by Kite Pharma, Inc., a pharmaceutical company, was approved by the U.S. FDA for the treatment of certain B-cell lymphomas. The listed price for axicabtagene ciloleucel (Yescarta) in the U.S. is US$ 373,000.
Market Opportunity– Increasing Investments by Key Market Players
Increasing adoption of inorganic growth strategies such as investments is expected to drive growth of the global cell therapy manufacturing market. For instance, on February 6, 2024, AstraZeneca, a global pharmaceutical company, announced that it had invested US$ 300 million in a facility in Rockville, Maryland, U.S. for discovery and development of cell therapies. The aim of the investment is to launch its life-saving cell therapy platforms in the U.S. for critical cancer trials and future commercial supply.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- Therapy Type Insights (Revenue, USD Bn, 2021 - 2033)
- Allogeneic Cell Therapy
- Autologous Cell Therapy
- Technology Type Insights (Revenue, USD Bn, 2021 - 2033)
- Somatic Cell Technology
- Cell Immortalization Technology
- Viral Vector Technology
- Genome Editing Technology
- Cell Plasticity Technology
- 3D Technology
- Manufacturing Purpose Insights (Revenue, USD Bn, 2021 - 2033)
- Clinical
- Commercial
- Pre-clinical
- Application Insights (Revenue, USD Bn, 2021 - 2033)
- Musculoskeletal
- Cardiovascular
- Gastrointestinal
- Neurological
- Oncology
- Dermatology
- Others
- Regional Insights (Revenue, USD Bn, 2021 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
- North America
- Key Players Insights
- WuXi AppTec, Inc.
- Lineage Cell Therapeutics, Inc.
- Healios Ltd.
- Lonza
- Merck KGaA
- Takara Bio Inc.
- Sumitomo Dainippon Pharma Co., LTD.
- Fujifilm Holdings Corporation
- Thermo Fisher Scientific, Inc.
- Astellas Pharma Inc.
- OXGENE
- Cytiva
- Exothera
- Charles River Laboratories
- Cell Therapies Pty Ltd
- Bio-Techne
- Catalent, Inc
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Cell Therapy Manufacturing Market is estimated to be valued at USD 6.51 Bn in 2026, and is expected to reach USD 17.65 Bn by 2033.
The CAGR of the Cell Therapy Manufacturing Market is projected to be 15.3% from 2026 to 2033.
Increasing launch of various types of technologies for cell therapy manufacturing and increasing regulatory approvals by regulatory authorities are the major factors driving the growth of global cell therapy manufacturing market.
High cost of cell therapies and stringent regulatory guidelines for cell therapy products are the major factors hampering the growth of global cell therapy manufacturing market.
In terms of therapy type, allogeneic cell therapy segment is estimated to dominate the in 2026.
WuXi AppTec, Inc., Lineage Cell Therapeutics, Inc., Healios Ltd., Lonza , Merck KGaA, Takara Bio Inc., Sumitomo Dainippon Pharma Co., LTD., Fujifilm Holdings Corporation, Thermo Fisher Scientific, Inc., Astellas Pharma Inc., OXGENE, Cytiva, Exothera, Charles River Laboratories, Cell Therapies Pty Ltd, Bio-Techne, Catalent, Inc are the major players.
North America is expected to lead the global cell therapy manufacturing market.