

Electric Bus Market Size and Forecast — 2026-2033
The electric bus market is estimated to be valued at USD 50.45 Billion in 2026 and is expected to reach USD 150.52 Billion by 2033, growing at a compound annual growth rate (CAGR) of 16.9% from 2026 to 2033.
 The electric bus market is driven by the need to reduce emissions from public transport. Major cities around the world are focusing on replacing their existing bus fleets with electric buses to improve the urban air quality. Countries are offering subsidies and promoting the adoption of electric buses. Bus manufacturers are launching new electric bus models with greater range to address consumer concerns. Also, lowering battery prices and advancing battery technologies are making electric buses more viable compared to diesel buses. Widespread charging infrastructure development by national governments will further accelerate this transition and drive the electric bus market in the coming years.
Climate change concerns and demand for sustainable public transit
As the impacts of climate change become increasingly visible and hard to ignore, governments, and public transit agencies around the world are under pressure to reduce carbon emissions from vehicular traffic. Buses form a crucial part of urban public transportation networks, and the conventional diesel buses that are most commonly used have significantly higher carbon footprint compared to electric buses. Many cities are major sources of air and noise pollution, and electric buses offer a cleaner, greener alternative to transition away from fossil fuel dependent mass transit. Public awareness about sustainability and corporate social responsibility is also on the rise. More companies and organization are committed to reducing their environmental impact, and promoting the use of electric vehicles as part of their efforts. Transit agencies have recognized that shifting to electric buses can help them gain goodwill from environmentally conscious citizens and demonstrate leadership in climate action. The zero-tailpipe emission of electric buses makes them especially appealing for public transportation in urban areas struggling with air quality issues. Concerns over worsening urban air pollution and public demands for a shift towards renewable energy are a major driver that is compelling more cities and public agencies to actively support electric bus adoption.
For instance, as of March 2022, China had over 421,000 electric buses in operation, constituting approximately 99% of the global electric bus fleet. Stringent government mandates, environmental considerations, and an expanding charging infrastructure are driving the electric bus market’s growth in Asia Pacific Region.
Insights, By Propulsion Type

Insights, By Propulsion Type- Technological advancement drives the demand for battery-powered buses
In terms of propulsion type, BEV is expected to contribute the highest share of 63.7% in 2026, owing to the advancements in battery cell technologies. BEVs offer greater ease of operation compared to other propulsion types as they do not require refueling infrastructure like hydrogen stations. Battery cell energy densities have improved considerably in recent years allowing BEVs to achieve longer driving ranges on a single charge. This increased range reduces range anxiety among transportation operators and makes BEVs more viable for inter-city routes. Continuous research by automakers has also brought down battery costs significantly, improving the total cost of ownership of BEVs. Governments around the world are providing strong subsidies for electric buses and setting targets for phasing out fossil fuel buses. Since BEVs do not emit any tailpipe emissions, they align well with the sustainability priorities of many cities and countries. The ZERO emissions of BEVs make them especially suitable for reducing pollution in densely populated urban centers.
Insights, By Length
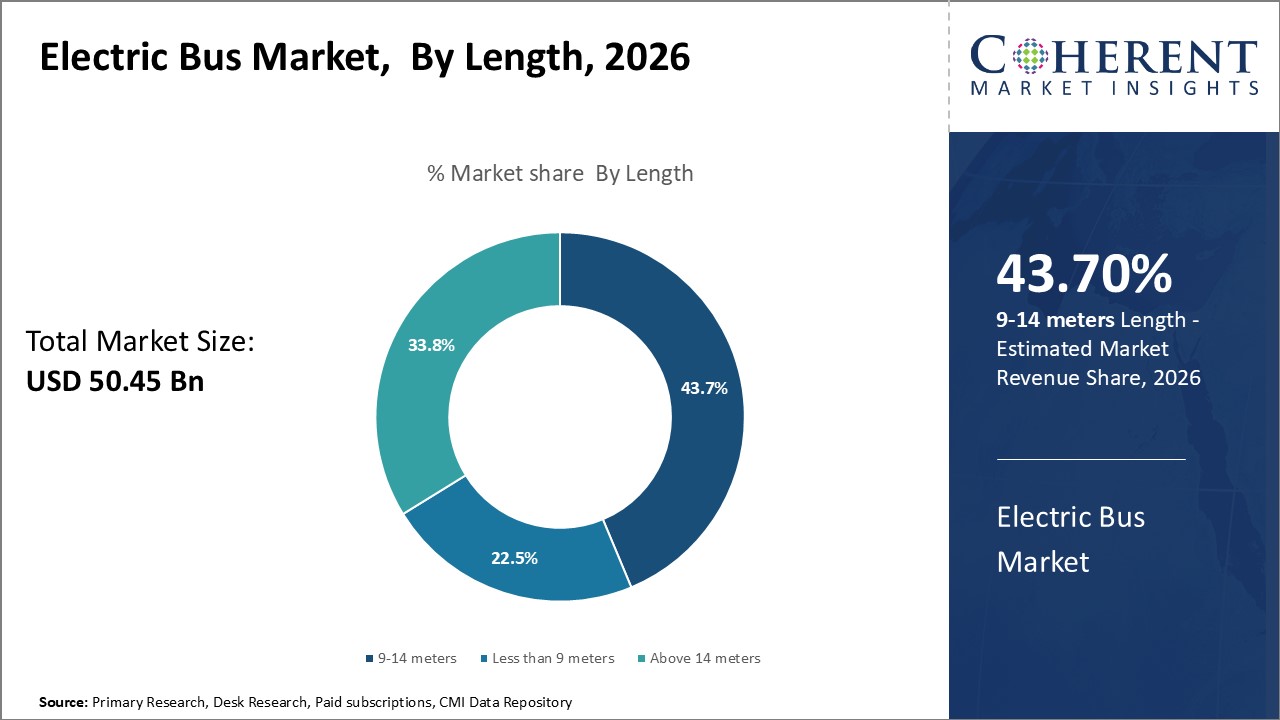
Insights, By Length - Growing demand for medium-sized buses (9-14 meters)
In terms of length, the 9-14 meters segment is expected to contribute the highest share of 43.7% in 2026. Electric buses in this size range can accommodate sufficient passenger capacity while being more manoeuvrable than larger buses, well-suited for busy inner-city routes. The 9-14 meters size is optimal for high frequency intra-city and shuttle services. Many global cities are focused on electrifying public transit at scale to reduce urban air pollution. As bus fleets need large-scale replacements, the 9-14 meters segment serves as a sweet spot for achieving high electrification rates. Operators prefer medium-sized electric buses as they offer the right balance between capacity, size, and total cost of ownership compared to smaller or larger buses.
Insights, By Range
Insights, By Range- Short-range electric buses dominate early adoption
In terms of range, the less than 200 miles segment is expected to contribute the highest share of 83.76% in 2026. In the early phases of electric bus adoption, most fleet operators prioritize initial use cases focusing on shuttle and circulator routes within cities and between nearby towns. These intra-city routes typically involve daily ranges well under 200 miles, making shorter range buses sufficient. Shorter ranges also help ease operators' concerns over battery degradation and residual value. Many municipalities also face budget limitations in the initial procurement stages. Short-range electric buses with smaller battery packs offer a lower upfront cost compared to long-range options. As fleet operators gain more experience over time and battery technology progresses, the demand shift towards higher range buses will accelerate. But in the early growth phase, short-range buses are catalyzing the initial large-scale electrification of bus fleets.
Regional Insights
 The global electric bus market is poised for substantial growth, with the Asia Pacific (APAC) region emerging as the primary driver. Projections for 2026 indicate that APAC is set to dominate the market, capturing an impressive 78.8% of the share and exhibiting the fastest growth rate at a CAGR of 18.82%. This dominance is underpinned by various factors, including robust government support in the form of financial incentives, regulatory initiatives, and infrastructure development projects aimed at promoting the widespread adoption of electric buses. Furthermore, the rapid economic growth and urbanization witnessed in the region contribute to an escalating demand for public transportation, creating a conducive environment for the proliferation of electric buses. The presence of major electric bus manufacturers, such as BYD in China, further positions APAC as a key player, offering a substantial advantage in terms of production capacity and technological advancements.
While Acia Pacific region commands the largest market share, other regions are also experiencing growth in the electric bus sector. In Europe, established public transportation systems, stringent emission regulations, and the presence of European electric bus manufacturers contribute to a steady growth rate ranging from 14-16.5% CAGR. North America is increasingly adopting electric buses in major cities, driven by a focus on reducing carbon footprints and improving air quality, leading to an anticipated CAGR of 15-18.5%. Latin America and the Middle East & Africa, although at an early stage of adoption with lower initial market shares, are projected to exhibit the highest CAGR, ranging from 19-25.5%. This growth is attributed to a growing awareness of environmental issues, potential government support, and significant room for expansion.
In summary, the electric bus market is on a promising trajectory, fuelled by a combination of supportive government policies, evolving consumer preferences, and continuous technological advancements. As the market evolves, regional dynamics may shift, with other regions potentially catching up to Asia Pacific as infrastructure development, government support, and technological progress continue to unfold.
Market Players, Key Development, and Competitive Intelligence
 Government Incentives and Policy Support
Governments around the world are also incentivizing this shift through various subsidy and tax break programs for electric buses and related infrastructure. For example, the growing bus fleet electrification programs in Chinese cities were mainly driven by strong policy push and financial support from the national and local governments. The California marketplace for electric buses has also expanded rapidly over the past few years backed by massive grants and funding from the state. As emissions regulations get tougher worldwide, electric buses are emerging as a cost-effective means for transit agencies to transition to cleaner fleets and meet compliance standards. Their lower operating costs compared to diesel buses over the lifespan also make electric buses an attractive proposition for agencies aiming to maximize available budgets. With more automakers developing electric bus models, the options available to agencies are increasing as well. As battery technologies advance further, range limitations which were a challenge earlier are becoming less of a concern. All these factors combined are significant drivers that are fuelling the rising global demand for electric buses from a public transportation perspective.
For instance, in January 2023, the India-based electric mobility company, GreenCell Mobility Ltd, signed a contract with the transport department of the government of NCT Delhi. The agreement involves the deployment of 570 electric buses over the next two years. This move is driven by increasing population, environmental concerns, and a shift in consumer preference toward public transport.
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Market Report Scope
Electric Bus Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 50.45 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 16.9% | 2033 Value Projection: | USD 150.52 Bn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | AB Volvo, Alexander Dennis Limited, Anhui Ankai Automobile Co. Ltd., Ashok Leyland Limited, Blue Bird Corporation, Bolloré SE, BYD Company Limited, Daimler AG, Dongfeng Motor Company, Geely Automobiles Holdings Ltd., Hyundai Motor Company, Iveco S.p.A., New Flyer Industries Inc., Nissan Motor Corporation, Paccar Inc., Proterra Inc., Scania AB, Solaris Bus & Coach S.A., Tata Motors Limited, Toyota Motor Corporation, VDL Bus & Coach BV, Wrightbus Limited, Yutong Group, and Zhengzhou Yutong Bus Co., Ltd. | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Analyst Opinion (Expert Opinion)
 Market Challenges: High Upfront Costs and Battery Expense
The electric bus market faces several challenges. The upfront capital costs of electric buses are significantly higher than diesel buses, as battery and motor technologies remain expensive. Refueling and charging electric buses requires heavy infrastructure investments in grid upgrades and charging stations. Buses need to travel long distances daily, testing the limited range of current battery technologies. There are also concerns from operators regarding battery life and maintenance costs long-term. Standards and regulations for electronic components and charging are still evolving globally.
Market Opportunities: Supportive Government Policies and Regulations
Government policies around the world are increasingly supporting adoption through funding and regulations. Rider preferences are shifting towards more environmentally-friendly options. With larger scale manufacturing and technology improvements, battery and motor costs are expected to decline steadily. The total cost of ownership of electric buses is becoming comparable to diesel in many regions. City governments aim to reduce local emissions and fossil fuel dependency.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- Propulsion Type Insights (Revenue, USD Bn, 2021 - 2033)
- BEV
- FCEV
- PHEV
- Length Insights (Revenue, USD Bn, 2021 - 2033)
- Less than 9 meters
- 9-14 meters
- Above 14 meters
- Range Insights (Revenue, USD Bn, 2021 - 2033)
- Less than 200 miles
- More than 200 miles
- Regional Insights (Revenue, USD Bn, 2021 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East & Africa
- GCC Countries
- South Africa
- Israel
- Rest of Middle East & Africa
- North America
- Key Players Insights
- AB Volvo
- Alexander Dennis Limited
- Anhui Ankai Automobile Co. Ltd.
- Ashok Leyland Limited
- Blue Bird Corporation
- Bolloré SE
- BYD Company Limited
- Daimler AG
- Dongfeng Motor Company
- Geely Automobiles Holdings Ltd.
- Hyundai Motor Company
- Iveco S.p.A.
- New Flyer Industries Inc.
- Nissan Motor Corporation
- Paccar Inc.
- Proterra Inc.
- Scania AB
- Solaris Bus & Coach S.A.
- Tata Motors Limited
- Toyota Motor Corporation
- VDL Bus & Coach BV
- Wrightbus Limited
- Yutong Group
- Zhengzhou Yutong Bus Co., Ltd.
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Electric Bus Market is estimated to be valued at USD 50.45 Bn in 2026, and is expected to reach USD 150.52 Bn by 2033.
The CAGR of the Electric Bus Market is projected to be 16.9% from 2026 to 2033.
Climate change concerns and demand for sustainable public transit and government incentives and policy support are the major factors driving the growth of the electric bus market.
High upfront costs and battery expense and infrastructure investment needs and limited range are the major factors hampering the growth of the electric bus market.
In terms of propulsion type, BEV is estimated to dominate the market revenue share in 2026.
AB Volvo, Alexander Dennis Limited, Anhui Ankai Automobile Co. Ltd., Ashok Leyland Limited, Blue Bird Corporation, Bolloré SE, BYD Company Limited, Daimler AG, Dongfeng Motor Company, Geely Automobiles Holdings Ltd., Hyundai Motor Company, Iveco S.p.A., New Flyer Industries Inc., Nissan Motor Corporation, Paccar Inc., Proterra Inc., Scania AB, Solaris Bus & Coach S.A., Tata Motors Limited, Toyota Motor Corporation, VDL Bus & Coach BV, Wrightbus Limited, Yutong Group, and Zhengzhou Yutong Bus Co., Ltd. are the major players.
Asia Pacific is expected to lead the electric bus market in 2026.