

Motor Vehicle Sensor Market Size and Forecast — 2026-2033
Global motor vehicle sensor market is estimated to be valued at US$ 33.46 Bn in 2026 and is expected to reach US$ 47.09 Bn by 2033, exhibiting a compound annual growth rate (CAGR) of 5.0% from 2026 to 2033.

The rapid adoption of advanced driver-assistance systems and autonomous driving technologies can boost demand for various motion and position sensors, temperature sensors, pressure sensors and other types of motor vehicle sensors during the forecast period.
The market is expected to witness lucrative growth opportunities, owing to stringency in emission and safety regulations mandating the integration of various sensors in vehicles. Increasing consumer demand for advanced features such as collision avoidance, adaptive cruise control, blind spot detection, and others boosts the incorporation of numerous sensors per vehicle. Major automobile manufacturers are aggressively focusing on autonomous, connected, electric and shared mobility solutions, which can drive the motor vehicle sensor market growth.
Rising concerns over vehicle and passenger safety
With rising incidences of road accidents across the world, safety has become a major concern for both passengers as well as regulatory authorities. Various factors such as increasing traffic, reckless driving, poor road conditions, and others have contributed in making roads more unsafe over time. This has resulted in high fatality rates in many countries.
To address this issue and improve safety, modern vehicles are being outfitted with an increasing number of sensors. While basic sensors like anti-lock braking systems were common in the past, today's vehicles come equipped with a wide array of advanced sensors that serve as an additional set of eyes for drivers. These sensors power key systems such as proximity sensors, blind spot monitors, automatic emergency braking, and lane departure warning. Automakers are also actively developing self-driving technologies that will rely heavily on sensor inputs. This transition towards autonomous and connected vehicles is expected to dramatically boost the quantity of sensors installed per vehicle.
Insights By product type

Insights By product type - Physical property sensors segment dominate in the motor vehicle sensor market
By product type, physical property sensors segment is expected to contribute the highest market share of 37.7% in 2026, due to their critical role in vehicle safety. These sensors monitor vital signs like pressure, temperature, fluid levels, and power use to prevent damage and failures. Their round-the-clock sensing allows for real-time issue detection before problems escalate.
A car's complex systems rely on clean oil, coolant, fuel, and air to function properly. Physical property sensors sound the alert if fluids run low or overheat. This guards engines and other components from potential breakdowns. Detected issues can also help technicians pinpoint maintenance needs during servicing. Detecting faults early through constant physical property monitoring decreases repair bills.
Physical property sensors, which measure attributes like temperature, pressure, and speed, are the largest product segment in the motor vehicle sensor market. This segment is expected to exceed a value of USD 8 billion by 2018, reflecting the critical role these sensors play in vehicle safety, performance, and regulatory compliance.
Safety is a key driver of demand for physical property sensors. Accurate fuel level readings prevent drivers from getting stranded, while temperature sensors issue warnings to avoid engine damage from overheating. Emission control depends on physical sensor oversight of fuel mixtures, satisfying regulations while shielding owners from fines.
Consumer acceptance of advanced driver assistance systems (ADAS) is also boosting demand for physical property sensors. Blind spot alert relies on pressure sensors beneath mirrors, while adaptive cruise control depends on physical measurements of following distances for automatic braking. These convenience and assistance functions are popular with buyers, further driving demand for these sensors.
As vehicles integrate more autonomous functions, physical property monitoring becomes mission critical for performance and liability. Engineers continue refining physical sensors for miniaturization, multi-functioning, and cost savings, enabling adoption across luxury and economy models.
Today, few vehicles lack key physical property monitors. Their critical roles across vehicle operation help explain physical sensors' lead in the product type market segment. Demand for these sensors remains high as automakers install more as standard or safety equipment.
Insights By Application
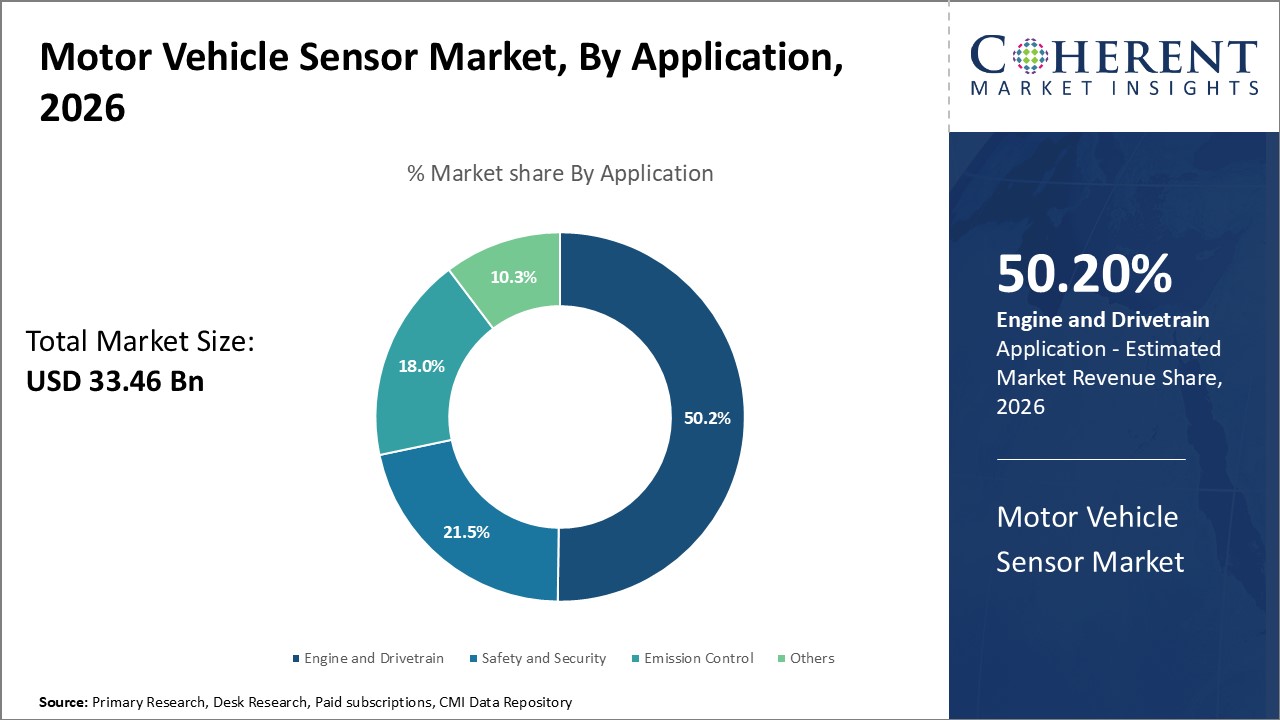
Insights By Application : Engine and Drivetrain Segment Dominates Application Type
By application, engine and drivetrain segment is expected to contribute the highest market share of 50.2% in 2026. Sensors play an integral role in engine and transmission management for optimal performance, fuel efficiency, and emissions standards compliance. Their precise monitoring protects vital components from damage while rewarding drivers with smooth, responsive driving characteristics.
Ignition, fuel injection, and emission control sensors provide real-time combustion feedback that engineers refine ignition timing and air-fuel mixtures for clean operation. Knock, camshaft, and crankshaft sensors maintain correct firing orders and ignition phasing. Their accuracy sustains high compression ratios for turbocharged downsizing without detonation risks.
Transmission position, torque, and pressure sensors enable smooth gear changes in automatic and dual-clutch models. These help powertrains optimize for conditions, preserving transmission life. Engine temperature, oil pressure, and differential sensors avoid overheating while maintaining optimal viscosity. Failure prevention reduces repair bills and maintains brand reputation.
Sensor innovations help unlock further efficiency gains to satisfy regulations. Their application sustains engine downsizing trends for mileage. As technologies evolve, engine and drivetrain monitoring sensors stay integral to performance, sustainability, and automated driving progress.
Regional Insights

North America dominates the motor vehicle sensors with an estimated market share of 43.9% in 2026. With the presence of major automobile manufacturers like General Motors, Ford and Tesla, the extensive vehicle manufacturing operations in the U.S. and Canada have boosted demand. Sensor technology is increasingly being incorporated into vehicles for safety, driver-assistance and emissions monitoring applications. Regional manufacturers focus on developing advanced capabilities to integrate more sophisticated sensors and stay ahead of tightening emission regulations.
The fast-growing Asia Pacific region has witnessed immense growth opportunities for motor vehicle sensors. China, in particular, has emerged as a major hub of automobile production with manufacturing capacities expanding massively. Lower input and labor costs have attracted significant investments from global OEMs to set up local factories. This has created a rapidly growing aftermarket as well. Meanwhile, other countries like India and Indonesia are boosting their manufacturing competitiveness with investing in sensor technologies. Their markets offer untapped potential given rising income levels and motorization rates. Export activity within Southeast Asia and developing trade with the Middle East and Africa also indicates strong ongoing demand momentum. While intellectual property protection needs strengthening, the Asia Pacific region's low-cost manufacturing environment and huge domestic auto markets make it an attractive high-growth area for motor vehicle sensors.
Market Players, Key Development, and Competitive Intelligence

Monitoring driver drowsiness and fatigue
Regulatory pressure also leads to sensorization of vehicles. Various countries have made certain active and passive safety features mandatory, in order to receive a vehicle type approval. For example, the European Union had mandated that all new vehicle models sold in EU should have Automatic Emergency Braking (AEB) system by 2022. Such regulatory pushes are designed to directly address safety issues and reduce accidents. With more safety features becoming mandated, it will boost the sales volume of various sensors. Even used car buyers are increasingly demanding essential safety features, that boosts demand for sensors
While developing autonomous driving capabilities involves additional costs, manufacturers are recognising that investing in safety technologies can help boost brand image and trust among customers. This encourages continuous innovation and adoption of new kinds of vehicle sensors. Rising prioritization of vehicle and passenger safety on roads can drive the motor vehicle sensor market globally. Strict regulations and changing customer mindset prompts sensorization of automobiles to create a safer driving experience.
Key Developments
- In January 2023, NXP Semiconductors N.V., a world leader in secure connectivity solutions for embedded applications, announced its participation in the early development phases of new VinFast automotive projects at CES 2023. VinFast, a member company of Vietnam's largest conglomerate Vingroup, will strive to leverage NXP's processors, semiconductors, and sensors, while NXP will provide its top-tier solutions to speed time-to-market. The joint expert collaboration between the two companies will focus on developing solutions for designing and producing cutting-edge electric vehicles based on NXP's recognized reference assessment platforms and software layers.
- In December 2022, Continental AG, a technology company known for its safe, efficient, intelligent, and affordable solutions for vehicles, machines, traffic, and transportation, announced that it will showcase modules and sensors specifically designed for electromobility. Continental AG will debut its Advanced Driver Assistance Systems (ADAS), which have been integrated into the "CV3" SoC (System on Chip) family with artificial intelligence (AI) from semiconductor startup Ambarella.
- In November 2022, Infineon Technologies AG, a leading global semiconductor solutions provider focused on electrification, automation, and digitalization, announced the addition of the latest XENSIV TLE4971 family to its current sensor portfolio for automotive applications. Infineon's XENSIV TLE4971 devices offer precise magnetic current sensing based on proprietary temperature and stress compensation, without the negative effects of magnetic cores caused by hysteresis or saturation effects.
- In March 2022, CTS Corporation, a global manufacturer of sensors and actuators, announced the acquisition of TEWA Temperature Sensors SP. Zo.o. and its subsidiaries. TEWA Temperature Sensors is an industry leader in temperature sensors, and this acquisition is a strong complement to CTS's existing temperature sensing platform. The deal will expand CTS's presence and capabilities in the European market.
*Definition: Global motor vehicle sensor market consists of various automotive sensors used across passenger cars, commercial vehicles, and other motorized vehicles for safe and efficient operation. These sensors monitor and detect critical parameters like temperature, pressure, fluid levels, speeds, driver inputs and more to efficiently control engine performance, emissions, braking, transmission, driver-assistance and safety systems. Major automobile sensors used include temperature sensors, pressure sensors, position sensors, oxygen sensors, speed sensors, and various MEMS sensors.
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Market Report Scope
Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 33.46 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 5.0% | 2033 Value Projection: | USD 47.09 Bn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | Allegro MicroSystems, Inc., Analog Devices, Inc., Amphenol Advanced Sensors, Aptiv PLC, Autoliv, Inc., BorgWarner, Inc., Continental AG, CTS Corporation, DENSO Corporation, and ELMOS Semiconductor SE, Infineon Technologies AG, Innoviz Technologies Ltd, LeddarTech, Magna International Inc., and Melexis N.V. | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Analyst Opinion (Expert Opinion)
Key Takeaways from Analyst:
[Global motor vehicle sensor market growth is driven by rising vehicle production and stringent emissions regulations worldwide. Sensors play a crucial role in emission control and vehicle safety features. The demand for emission control sensors increases with the implementation of real driving emissions (RDE) testing in Europe and more stringent emission norms globally. Gasoline particulate filters and selective catalytic reduction systems also require extensive sensing for effective operation. This boosts demand for exhaust gas sensors in the near future. However, high costs associated with developing autonomous driving technologies can hamper the market growth. As autonomous vehicles will gain popularity, there will be demand for advanced driver assistance systems (ADAS).
North America currently dominates the market due to the presence of leading automakers and strict emission norms. However, Asia Pacific region is expected to witness the fastest growth led by China and India. Both these countries are the largest automobile producers and are swiftly adopting advanced automotive technologies. Sensors play a critical role in advanced driver-assistance systems, connectivity, and automated driving. Rising vehicle electrification and automation can boost demand for innovative sensors. In summary, while costs remain a challenge for widespread adoption of new technologies, strict emission regulations and advancements in vehicle automation and connectivity will drive long-term growth in the global motor vehicle sensor market.]
Market Challenges: High installation and maintenance cost
The high installation and maintenance cost of sensors can hamper the global motor vehicle sensor market growth. Sensors play a vital role in modern vehicles by enabling various vehicle functions and active safety features. However, manufacturing high-precision sensors and then installing them on vehicles requires substantial capital investments. Sensor installation is a complex process that needs to be done carefully by experienced technicians to ensure optimal performance. Any mistake during installation can damage the sensors or lead to malfunctions. This increases the installation cost.
Once installed, sensors also require regular maintenance and calibration to account for normal wear and tear. Environmental factors like heat, dust, moisture, and others can degrade sensor performance over time. This necessitates periodic maintenance checks and sensor replacements. Replacing failed or faulty sensors is an expensive process as vehicles need to be taken off roads. The maintenance team has to disassemble vehicle components to access various sensor locations. This maintenance work involves labor costs. Many critical sensors like radars and cameras that enable advanced driver assistance systems are quite expensive devices. Frequent replacements significantly increase the overall maintenance expenditure for vehicle owners.
Market Opportunities: Developing autonomous vehicles
Developing autonomous vehicles present a great opportunity in the global motor vehicle sensor market. Autonomous vehicles require a significant number of advanced sensors to drive and maneuver safely. These need sensors like LiDAR, radar, ultrasonic and camera sensors to collect data from the surrounding environment and detect objects. As autonomous technology progresses, there will huge need and demand for more reliable and accurate sensors.
Vehicle sensor technology is also expected to evolve significantly to meet the rising safety, performance and functionality standards of autonomous vehicles. Sensors will need to offer higher resolution, wider coverage areas, better ability to operate under varied weather and lighting conditions. Thesemay need to be smaller in size as well to be housed unobtrusively in the vehicle body. This will require heavy research and development investments from both sensor manufacturers as well as automotive companies.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- Product Type Insights (Revenue, US$ Bn, 2021 - 2033)
- Physical property sensors
- Process variable sensors
- Chemical property sensors
- Others
- Application Insights (Revenue, US$ Bn, 2021 - 2033)
- Engine and drivetrain
- Safety and Security
- Emission control
- Others
- Regional Insights (Revenue, US$ Bn, 2021 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East & Africa
- GCC Countries
- Israel
- South Africa
- Rest of Middle East & Africa
- North America
- Key Players Insights
- Allegro MicroSystems, Inc.
- Analog Devices, Inc.
- Amphenol Advanced Sensors
- Aptiv PLC
- Autoliv, Inc.
- BorgWarner, Inc.
- Continental AG
- CTS Corporation
- DENSO Corporation
- ELMOS Semiconductor SE
- Infineon Technologies AG
- Innoviz Technologies Ltd
- LeddarTech
- Magna International Inc.
- Melexis N.V.
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Motor Vehicle Sensor Market is estimated to be valued at USD 33.46 Bn in 2026, and is expected to reach USD 47.09 Bn by 2033.
The CAGR of the Motor Vehicle Sensor Market is projected to be 5.0% from 2026 to 2033.
Rising concerns over vehicle and passenger safety and monitoring driver drowsiness and fatigue are the major factors driving the growth of global motor vehicle sensor market.
High installation and maintenance cost and cyber security threats are the major factors hampering the growth of global motor vehicle sensor market.
In terms of product type, physical property sensors segment is estimated to dominate the market in 2026.
Allegro MicroSystems, Inc., Analog Devices, Inc., Amphenol Advanced Sensors, Aptiv PLC, Autoliv, Inc., BorgWarner, Inc., Continental AG, CTS Corporation, DENSO Corporation, ELMOS Semiconductor SE, Infineon Technologies AG, Innoviz Technologies Ltd, LeddarTech, Magna International Inc., and Melexis N.V. are the major players.
North America is expected to lead the global motor vehicle sensor market in 2026.