

Phosphorus Pentachloride Market Size and Forecast – 2026 to 2033
The Phosphorus Pentachloride Market is anticipated to grow at a CAGR of 4.8% with USD 1,207.6 Bn share in 2026 and is expected to reach USD 1,873.7 Bn in 2033. Rising pharmaceutical and agrochemical production is driving demand for phosphorus pentachloride, which manufacturers use as a key chlorinating agent in chemical synthesis.
Key Takeaways
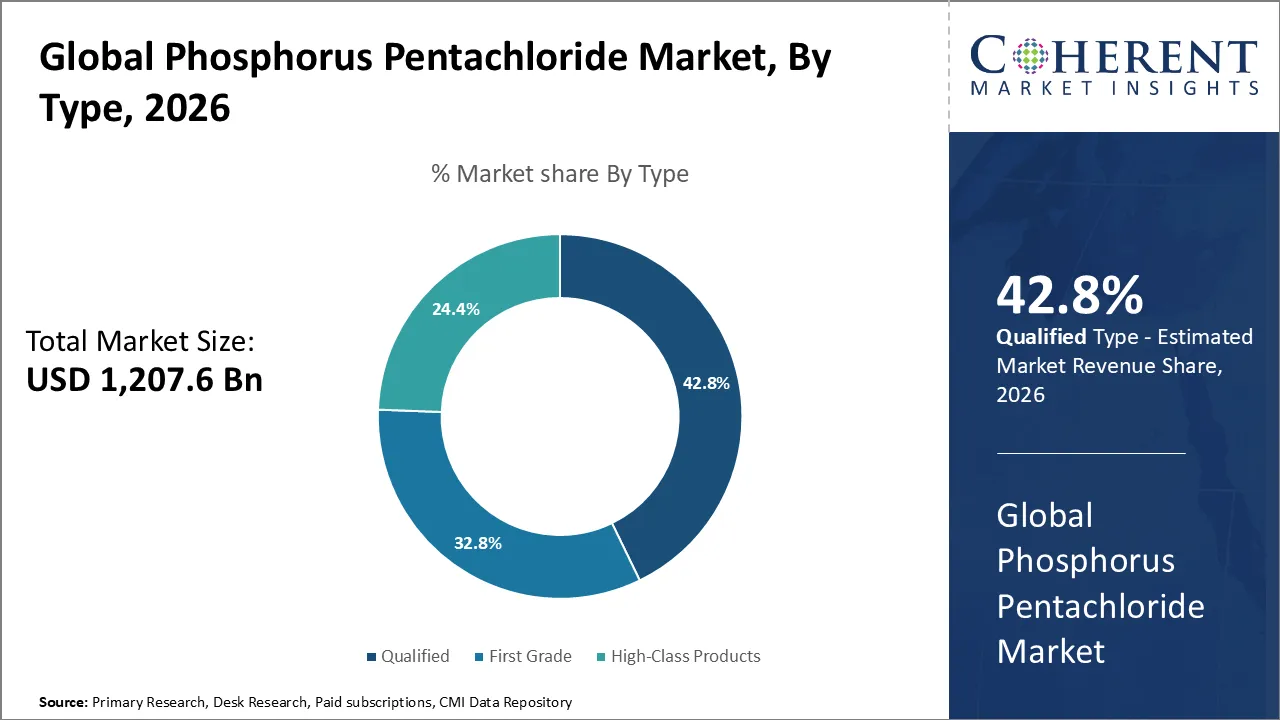
- Qualified hold the largest market share of 42.8% in 2026 owing to the rising agrochemical production. India ranks 8th globally among agricultural exporters, with agricultural exports valued at approximately USD 35 Bn.
- Pharmaceutical expected to hold largest market share of 38.9% in 2026 owing to its rising API production. India has the largest number of USFDA-approved manufacturing facilities outside the United States, underscoring the global credibility of its pharmaceutical manufacturing standards. The country also has around 500 API manufacturers, representing nearly 8% of the global API market.
- North America is expected to acquire the dominant share of 41.8% in 2026 owing to the strong pharmaceutical manufacturing base. Approximately 1.3 million people are employed in the U.S. pharmaceutical industry, according to the U.S. Bureau of Labor Statistics (BLS).
Current Events and Their Impact on the Phosphorus Pentachloride Market
Current Event | Description and its Impact |
EU Adds Phosphorus Pentachloride to the Dual-Use Export Control List |
|
EU Strengthens Controls on Trade in Chemical Dual-Use Items |
|
Segmental Insights
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Why is Qualified Acquiring the Largest Market Share?
Qualified hold the largest market share of 42.8% in 2026. The Qualified segment of the Phosphorus Pentachloride Market benefits from its affordability, versatile industrial applications, and suitable purity for various chemical synthesis processes. Manufacturers use Qualified phosphorus pentachloride, typically with at least 98% purity, to produce pharmaceutical and agrochemical intermediates and support chlorination and specialty chemical processes. Rising pharmaceutical API production, growing agrochemical demand, and expanding chemical manufacturing continue to increase consumption. India is the world’s third-largest producer of active pharmaceutical ingredients (APIs), manufacturing more than 2,000 APIs. Manufacturers also prefer this grade because it delivers reliable performance while offering a more economical alternative to higher-purity grades.
Which End-Use Industry segment dominates the market?
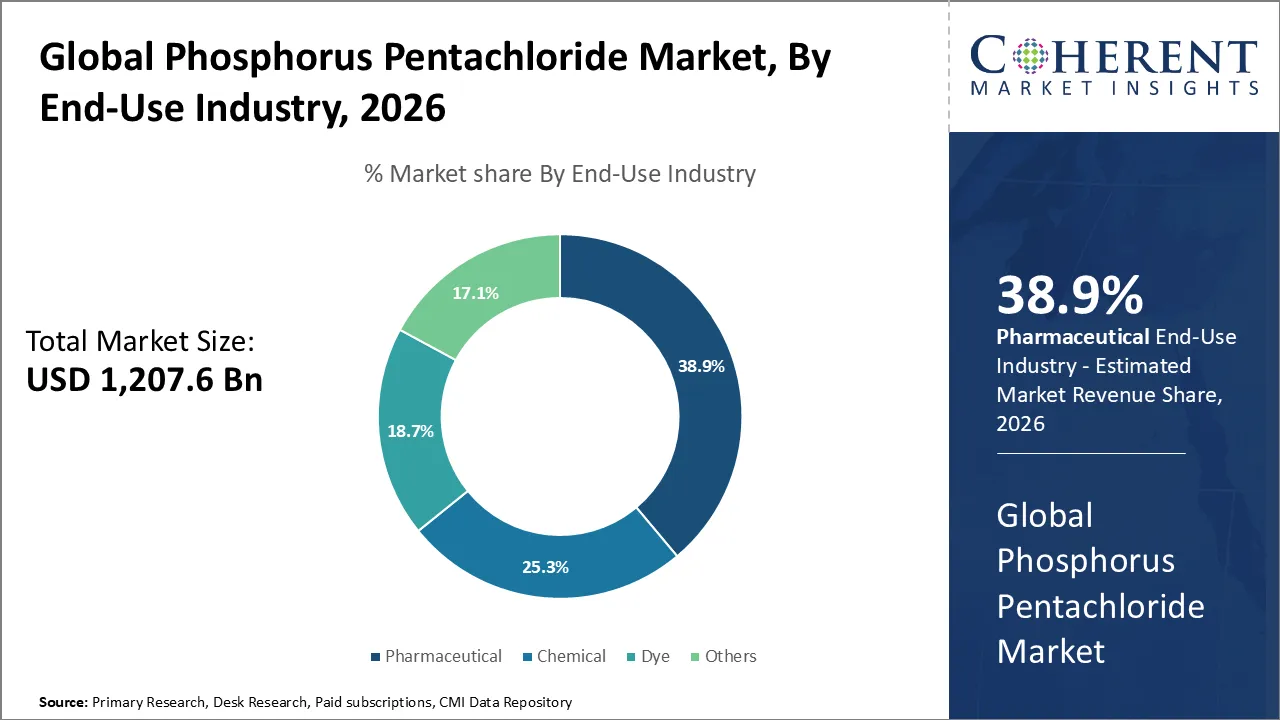
Pharmaceutical expected to hold largest market share of 38.9% in 2026. The pharmaceutical segment of the Phosphorus Pentachloride Market is expanding as pharmaceutical companies increase API and intermediate production. Manufacturers rely on phosphorus pentachloride as an effective chlorinating and dehydrating agent for drug synthesis and the production of complex organic intermediates. Rising demand for generic medicines, expanding pharmaceutical manufacturing in emerging markets, and ongoing development of small-molecule drugs further stimulate demand. The global generic drugs market is expected to reach USD 720 Billion by 2033. Pharmaceutical companies also seek reliable reagents that improve synthesis efficiency, supporting wider use of phosphorus pentachloride in drug manufacturing and research.
Phosphorus Pentachloride Market Trends
- Growing pharmaceutical and agrochemical production increases demand for phosphorus pentachloride: PCl₅ is used as a chlorinating/dehydrating reagent in chemical synthesis, including the manufacture of pharmaceutical and agrochemical intermediates. The underlying pharmaceutical manufacturing base is substantial: India's Department of Pharmaceuticals reports about 500 API manufacturers, accounting for approximately 8% of the global API industry. India's pharmaceutical-sector turnover also reached INR 4.17 lakh crore in FY2023–24, up about 10% year over year. This expanding API manufacturing base supports demand for chemical intermediates and reagents used in pharmaceutical synthesis.
- Expansion of pharmaceutical manufacturing in India strengthens the Asia-Pacific demand base: India's Department of Pharmaceuticals reports that the country ranks third globally by pharmaceutical production volume and supplies approximately 20% of the world's generic medicines. In addition, the government's pharmaceutical PLI schemes had created manufacturing capacity for 218 APIs/KSMs/drug intermediates according to a 2026 Government of India factsheet. These developments indicate continued expansion of the pharmaceutical manufacturing ecosystem in a major Asia-Pacific market for specialty chemical inputs.
- Increasing agrochemical consumption supports the broader demand environment for chemical intermediates: FAO's latest FAOSTAT release reports that global agricultural pesticide use reached 3.73 million tonnes of active ingredients in 2023, up 14% over the previous decade and approximately double the 1990 level. While FAO does not identify phosphorus pentachloride as the cause of this demand, the continued scale of global pesticide production provides a relevant downstream market context for chemical intermediates used in crop-protection manufacturing.
Regional Insights
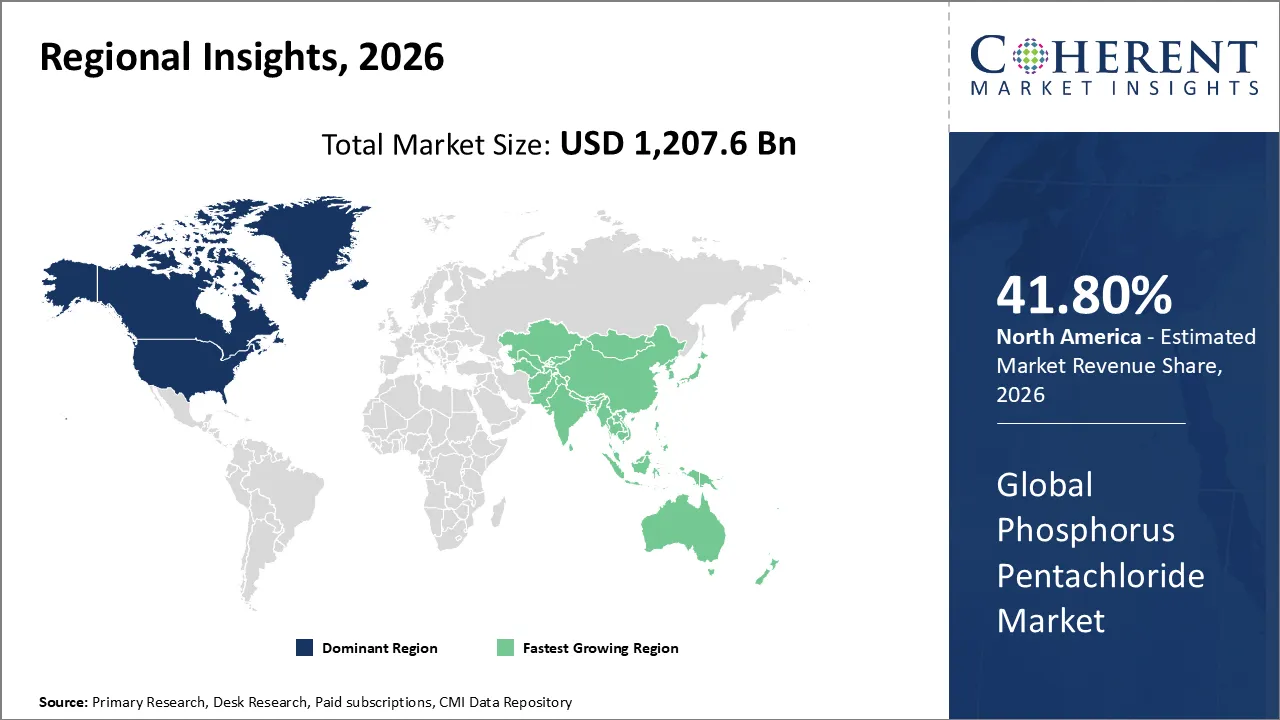
North America dominates owing to supply-chain resilience and domestic production focus
North America is expected to acquire the dominant share of 41.80% in 2026. North America’s phosphorus pentachloride market gains momentum from rising demand across pharmaceutical, agrochemical, and specialty chemical industries. Manufacturers use phosphorus pentachloride extensively as a chlorinating and dehydrating agent to produce pharmaceutical intermediates and pesticides. Growing drug production, increasing crop protection needs, and expanding specialty chemical manufacturing continue to boost consumption. The region’s strong chemical infrastructure, advanced research capabilities, and demand for high-purity materials further support growth. Moreover, companies are investing in domestic production and resilient supply chains to ensure reliable procurement.
Asia Pacific Phosphorus Pentachloride Market Trends
Asia Pacific’s phosphorus pentachloride market benefits from expanding pharmaceutical and agrochemical production, especially in China and India. Manufacturers increasingly use phosphorus pentachloride as a chlorinating agent to produce active pharmaceutical ingredients, pesticides, and specialty chemical intermediates. Rapid industrialization, established chemical manufacturing capabilities, competitive raw material costs, and growing export-oriented production continue to strengthen regional demand. In addition, expanding electronics and advanced materials industries, along with investments in chemical infrastructure and research, create further growth opportunities. Vital Chemtech, a leading manufacturer of phosphorus derivatives and specialty chemicals, has received MCA approval to become a public limited company. Located in the PCPIR region of Dahej, the company produces phosphorus specialties including PCl₃, POCl₃, PCl₅, P₂O₅, PPA, OPA, and P₂S₅.
United States Phosphorus Pentachloride Market Trends
The Asia Pacific phosphorus pentachloride market gains momentum from expanding pharmaceutical and agrochemical production in China and India. Manufacturers increasingly use phosphorus pentachloride as a chlorinating agent to support the production of active pharmaceutical ingredients and pesticides. Global agricultural pesticide use totaled approximately 3.92 million tonnes of active ingredients in 2024. Rapid industrialization, expanding specialty chemical manufacturing, and investments in new chemical production facilities further stimulate demand. Established supply chains, cost-effective manufacturing, and better access to raw materials strengthen the regional market. In addition, manufacturers increasingly apply phosphorus pentachloride in advanced materials and electronics, creating further growth opportunities.
China Phosphorus Pentachloride Market Trends
China’s Phosphorus Pentachloride market benefits from strong demand across agrochemical, pharmaceutical, chemical, and battery-material industries. Manufacturers use Phosphorus Pentachloride extensively as a chlorinating agent and chemical intermediate to produce pesticides, pharmaceuticals, and specialty chemicals. China leverages its integrated phosphorus chemical supply chain, ready access to yellow phosphorus and chlorine, and large-scale manufacturing capabilities to strengthen its market position. Rising lithium-ion battery electrolyte production also boosts demand, while Chinese manufacturers support further market growth through expanding exports.
Who are the Major Companies in Phosphorus Pentachloride Industry
Some of the major key players in Phosphorus Pentachloride are Xuzhou JianPing Chemical Co., Ltd., Tongshan Hongda Fine Chemical, Jiangxi Jixiang Pharmchemical Co., Ltd., Suzhou Hantech Chemical Co., Ltd, Shijiazhuang Zhonghao Chemical Co., Ltd., and United Phosphorus Limited.
Phosphorus Pentachloride Market Report Coverage
Report Coverage | Details | ||
Base Year: | 2025 | Market Size in 2026: | USD 1,207.6 Bn |
Historical Data for: | 2020 to 2024 | Forecast Period: | 2026 to 2033 |
Forecast Period 2026 to 2033 CAGR: | 4.8% | 2033 Value Projection: | USD 1,873.7 Bn |
Geographies covered: |
| ||
Segments covered: |
| ||
Companies covered: | Xuzhou JianPing Chemical Co., Ltd., Tongshan Hongda Fine Chemical, Jiangxi Jixiang Pharmchemical Co., Ltd., Suzhou Hantech Chemical Co., Ltd, Shijiazhuang Zhonghao Chemical Co., Ltd., and United Phosphorus Limited. | ||
Analyst Opinion
- China’s Phosphorus Pentachloride market is increasingly being shaped by battery chemicals rather than traditional chemical applications. In our view, the strongest structural opportunity comes from its role in the production chain for lithium hexafluorophosphate (LiPF₆), a key electrolyte salt. China accounted for about 371,000 tonnes of effective LiPF₆ production capacity at the end of 2024, representing roughly 95% of global effective capacity. This concentration gives Chinese phosphorus-chlorine suppliers a major strategic advantage.
- China’s rapidly expanding lithium-ion battery ecosystem provides a powerful downstream demand signal. The country produced 1,170 GWh of lithium-ion batteries in 2024, while electrolyte output reached approximately 1.3 million tonnes, with both categories recording growth exceeding 20%. We believe this makes battery-grade chemical supply chains a more important demand driver for phosphorus pentachloride than conventional end-use sectors.
- The shift toward lithium iron phosphate (LFP) batteries further strengthens this outlook. China installed 625.3 GWh of LFP batteries in 2025, accounting for 81.2% of its total power-battery installations. The dominance of LFP reinforces China’s consumption of phosphorus-based battery chemicals and creates a durable demand channel for upstream phosphorus pentachloride producers.
- We expect supply-chain integration to remain China’s decisive competitive advantage. More than 98% of global LFP cathode material and LFP battery cells were produced in China in 2024, according to the IEA. This level of concentration allows Chinese chemical manufacturers to coordinate phosphorus feedstocks, chlorination chemistry, electrolyte production, and battery-material manufacturing more efficiently than most overseas competitors.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- By Type (Revenue, USD Bn, 2021-2033)
- Qualified
- First Grade
- High-Class Products
- By End-Use Industry (Revenue, USD Bn, 2021-2033)
- Pharmaceutical
- Chemical
- Dye
- Others
- By Region (Revenue, USD Bn, 2021-2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Rest of Latin America
- Europe
- Germany
- U.K.
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- South Africa
- Central Africa
- North Africa
- North America
Sources
Primary Research interviews
- Interviews with phosphorus pentachloride manufacturers and producers
- Interviews with distributors, importers, exporters, and chemical traders
- Discussions with procurement managers and sourcing professionals in chemical-consuming industries
- Interviews with downstream users in pharmaceuticals, agrochemicals, specialty chemicals, and chemical synthesis
- Conversations with technical experts, plant managers, and industry professionals
- Feedback from logistics providers and chemical supply-chain participants
Databases
- PubChem
- CAS Common Chemistry
- EPA CompTox Chemicals Dashboard
- European Chemicals Agency (ECHA) databases
- ChemIDplus
- ChEBI
- ChEMBL
- HSDB / Hazardous Substances Data Bank
- UN Comtrade Database
- World Integrated Trade Solution (WITS)
- U.S. International Trade Commission (USITC) DataWeb
- Eurostat
- UN Statistics Division databases
- National statistical databases
- Customs and import-export databases
- Chemical substance and regulatory databases
Magazines
- Chemical & Engineering News
- ICIS Chemical Business
- Chemical Week
- European Chemical News
- Chemistry World
- Chemical Processing
- Chemical Engineering
- Pharma Manufacturing
- Agro & Chemical Industry publications
- Specialty Chemicals Magazine
- Industrial Chemistry and Chemical Engineering publications
Journals
- Journal of Chemical & Engineering Data
- Industrial & Engineering Chemistry Research
- Journal of Organometallic Chemistry
- Inorganic Chemistry
- Dalton Transactions
- Chemical Communications
- Journal of Fluorine Chemistry
- Phosphorus, Sulfur, and Silicon and the Related Elements
- Tetrahedron
- Tetrahedron Letters
- Organic Process Research & Development
- ACS journals and related chemical-science publications
- ScienceDirect-indexed chemistry and chemical engineering journals
- Springer chemistry journals
- Wiley chemistry journals
Newspapers
- Reuters
- Financial Times
- The Wall Street Journal
- The Economic Times
- Business Standard
- The Hindu BusinessLine
- Mint
- The Hindu
- Nikkei Asia
- China Daily
- South China Morning Post
- Regional and national business newspapers covering chemical manufacturing, trade, pharmaceuticals, and industrial production
Associations
- American Chemistry Council (ACC)
- Society of Chemical Industry (SCI)
- Royal Society of Chemistry (RSC)
- American Chemical Society (ACS)
- European Chemical Industry Council (Cefic)
- International Council of Chemical Associations (ICCA)
- National Association of Chemical Distributors (NACD)
- Pharmaceutical and agrochemical industry associations
- National chemical manufacturers' associations
- Regional specialty-chemical associations
Public Domain sources
- U.S. Environmental Protection Agency (EPA)
- European Chemicals Agency (ECHA)
- National Institutes of Health (NIH)
- National Library of Medicine (NLM)
- PubChem
- National Oceanic and Atmospheric Administration (NOAA) CAMEO Chemicals
- International Labour Organization (ILO) / International Chemical Safety Cards
- World Health Organization (WHO)
- U.S. International Trade Commission (USITC)
- UN Comtrade
- World Bank / World Integrated Trade Solution (WITS)
- Eurostat
- U.S. Census Bureau
- U.S. Geological Survey (USGS)
- U.S. Department of Energy
- U.S. Department of Commerce
- Government customs and trade statistics
- National statistical offices
- Patent databases including WIPO PATENTSCOPE, Google Patents, and national patent offices
- Government legislation, regulatory filings, environmental databases, and chemical inventories
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of information for last 10 years
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The market is primarily driven by rising pharmaceutical API production, expanding agrochemical manufacturing, and growing demand for efficient chlorination and dehydration processes.
Qualified Phosphorus Pentachloride is expected to maintain the leading position because of its relatively economical cost, suitable purity, and broad applicability in pharmaceutical, and chemical synthesis.
Pharmaceutical manufacturers use Phosphorus Pentachloride as a chlorinating and dehydrating reagent during API and intermediate synthesis.
Agrochemical manufacturers use Phosphorus Pentachloride to produce pesticide, herbicide, and other crop-protection intermediates.
China plays a strategically important role because of its integrated phosphorus chemical supply chain, and extensive downstream battery and specialty chemical industries.