
Special Transformer Market Size and Share Analysis- Growth Trends and Forecasts (2026-2033)
The Special Transformer Market size is anticipated to grow at a CAGR of 7.3%, with a market value of USD 3.65 Bn in 2026, and is expected to reach USD 5.97 Bn by 2033. The primary growth drivers are largely defined by rising investments in power transmission and distribution infrastructure, increasing demand for energy-efficient transformers, expansion of railway electrification projects, growing integration of renewable energy sources, and increasing adoption of specialized transformers across steel manufacturing, oil and gas, and industrial applications. According to Eurostat reports that the share of electrified railway lines in the European Union rose from 39.9% in 1990 to 57.6% in 2024.
Key Takeaways
- The Electric Furnace Transformer segment is estimated to hold a 38.0% share of the market in 2026. The growth of the segment is driven by the increasing adoption of electric arc furnace technology, growing steel recycling operations, and the demand for high-current power supply systems in the metal processing industries. According to World Steel Association’s World Steel in Figures 2026, in 2025 electric steelmaking represented 90.1% of Italy’s crude steel production and 71.7% of Spain’s, indicating the significance of electric furnace technology in industrial steel production.
- The Electric Furnace Power Supply segment is estimated to account for the largest market share of 40.0% in application category by 2026. Growth is driven by rising industrial electrification, modernisation of steel production facilities and demand for reliable voltage regulation in energy-intensive manufacturing processes. According to the International Energy Agency (IEA), global electricity demand is projected to grow by an average of 3.6% per year during 2026-2030 in part due to growing industrial electricity consumption.
- Asia Pacific is expected to be the largest market for Special Transformers in terms of value by 2026. China and India are witnessing regional growth driven by rapid industrialization, expanding power infrastructure, growing manufacturing activity and increasing investment in energy intensive industries. China’s electricity demand is forecast to increase by 5.5% in 2026 and India’s electricity demand by 7.0% according to the IEA’s July 2026 Electricity Mid-Year Update, creating opportunities for specialised electrical equipment throughout the region.
Market Drivers
Expansion of Power Transmission Infrastructure is Accelerating Growth in the Special Transformer Market
The Special Transformer Market is experiencing a substantial growth driven by increased investments in electricity transmission infrastructure, modernisation of power networks, and growing demand for reliable power delivery across industrial facilities. Special transformers, such as phase-shifting transformers, converter transformers, and rectifier transformers, are gaining importance as electricity networks become more complex and the demand for better voltage regulation, power flow control and operational efficiency increases.
According to India’s Ministry of Power said its transmission transformation capacity was around 1,478 GVA in July 2026 and it plans to raise it to 2,345 GVA by 2032. Over FY 2023-24 to FY 2025-26, India added around 270,174 MVA of transformation capacity at 220 kV and above. These developments indicate potential for considerable investment in electrical infrastructure.
In September 2026, the Government of India approved the Green Energy Corridor Phase-III scheme with an investment of about INR 1,86,405 crore. It aims at integration of 135 GW of renewable energy capacity and deployment of 50 GWh battery energy storage by FY 2032-33.
Increasing Renewable Energy Integration is Driving Demand for Specialized Transformers
Growing use of renewable energy technologies is becoming a key driver for Special Transformer Market. Solar and wind power installations require specialised electrical infrastructure to manage variable power generation, maintain voltage stability, and efficiently transmit electricity. Special interest is given to inverters, converters and phase-shifting transformers for the integration of renewable energy, industrial power conversion and control of electricity flows between interconnected networks.
In March 2026, India’s Ministry of Power said it was planning transmission infrastructure to integrate over 500GW of non-fossil fuel capacity by 2030 and more than 600GW by 2032. This includes dedicated transmission systems and green energy corridors to facilitate evacuation of renewable electricity.
Current Events and Their Impact on the Special Transformer Market
Current Event | Description and its Impact |
U.S. Government Introduces New Security Regulations for Power Transformers and Electrical Grid Equipment (August 2026) |
|
Indian Government Approves Green Energy Corridor Phase-III to Strengthen Renewable Power Transmission (September 2026) |
|
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Segmental Insights
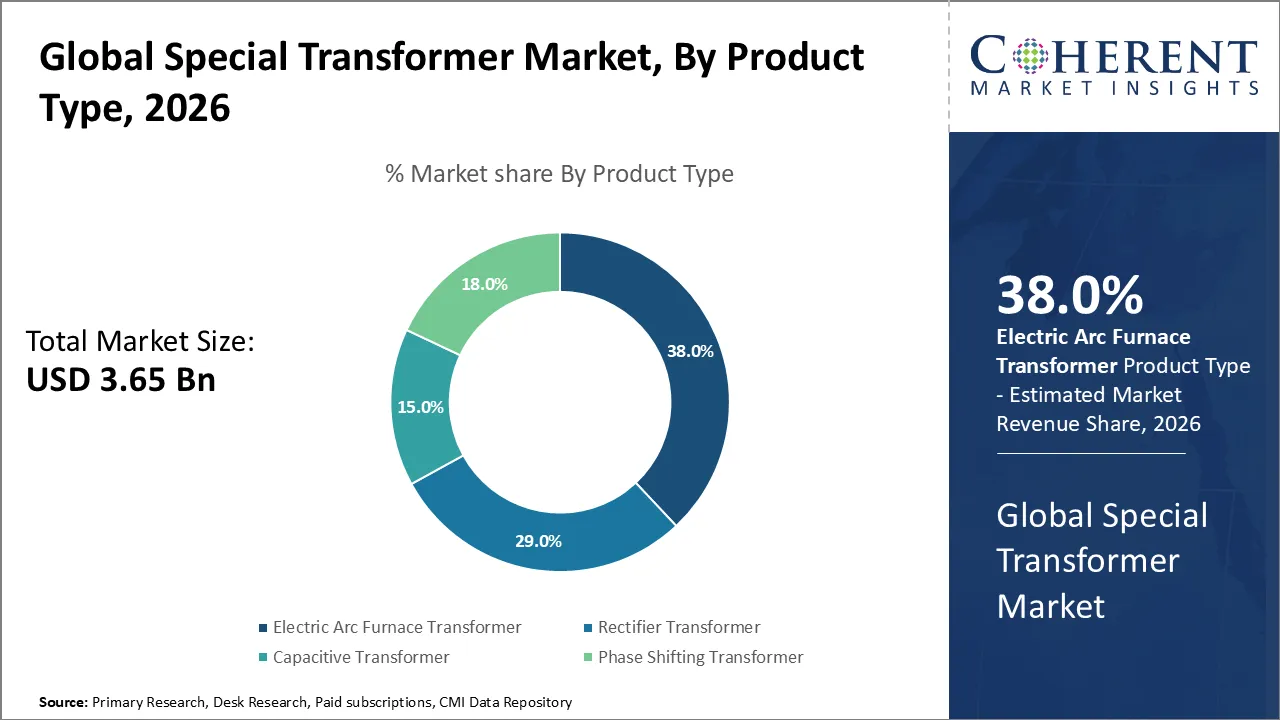
Why is the Electric Furnace Transformer Segment Acquiring the Largest Market Share?
On the basis of product type, the Electric Furnace Transformer segment is estimated to account for the largest Special Transformer Market share of 38.0% in 2026. The segment growth is attributed to increasing adoption of electric arc furnaces for steel production, increasing investments in low carbon metal production and increasing demand for high current electrical systems. Electric furnace transformers are vital for a stable power supply and are applied to handle diverse electrical loads and improve energy efficiency in steel production and other high-temperature industrial processes.
According to the World Steel Association’s World Steel in Figures 2026, electric steelmaking represented about 30.3% of the world’s crude steel output in 2025. The electric process contributed 71.3% in the US and 57.7% in India. This indicates the widespread industrial use of the electrically powered steelmaking technologies.
In June 2026, POSCO finished construction of a large-scale electric arc furnace at its Gwangyang steelworks in South Korea with an investment of some KRW 600 billion and an annual output capacity of 2.5 million tons. The plant is expected to reduce carbon emissions by about 75% compared to conventional blast furnace operations.
Why is Electric Furnace Power Supply Holding the Largest Market Share?
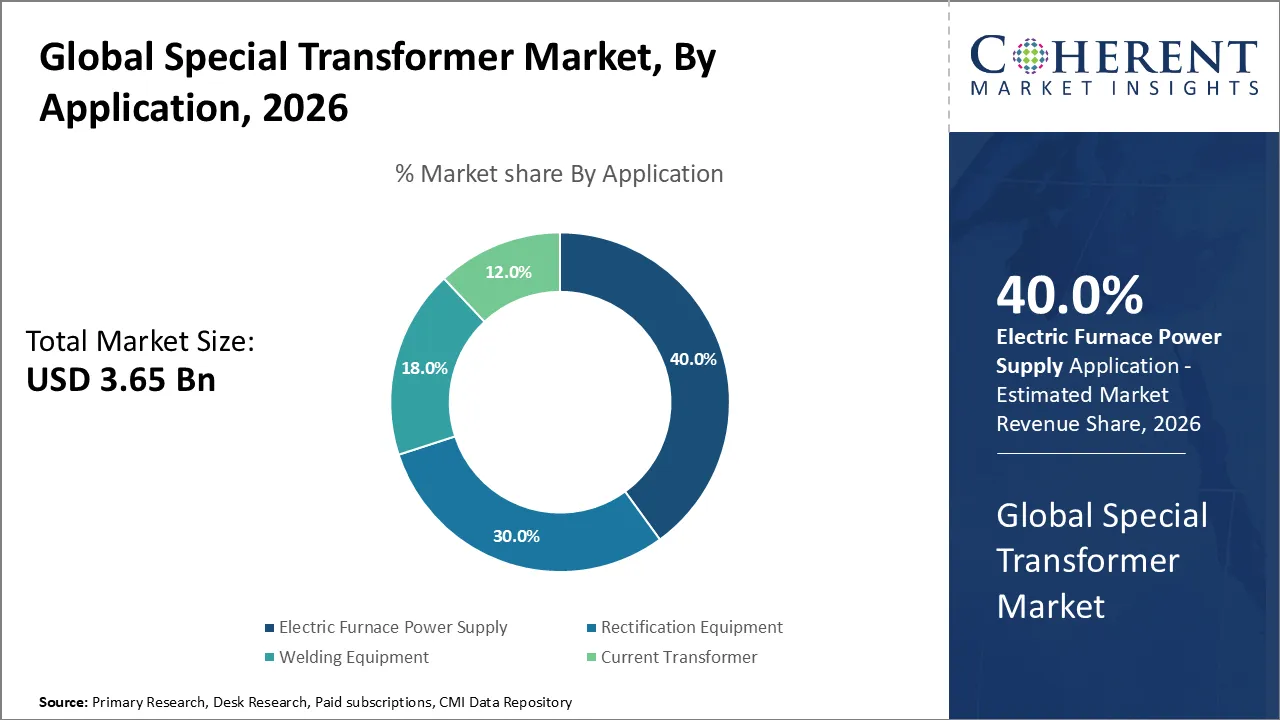
Based on application, the Electric Furnace Power Supply segment is expected to hold the largest market share of 40.0% in 2026, followed by the Special Transformer Market. This is attributed to the growing electrification of steel production, growth in scrap-based steel production, and increasing demand for efficient power management for high-temperature industrial processes. Special transformers for electric furnace application offer controlled voltage, high current output and reliable power delivery under rapidly varying load conditions.
In March 2026, Tata Steel also established its first electric arc furnace-based facility on scrap in Ludhiana, India at an investment of about INR 3,200 crore with an annual capacity of 0.75 million tons. It has advanced Q-One power technology to optimize electricity consumption and operating efficiency. This shows that more and more sophistical electrical power supply systems are used in steel making.
In July 2025, Algoma steel in Canada reported first steel production at its new electric arc furnace, Unit One. The commissioning process involved successful electrical testing and tuning of nine Q-One transformer modules.
Special Transformer Market Trends
- The growing trend towards domestic transformer production is strengthening regional supply chains and reducing dependence on imported electrical equipment. In September 2026, Hitachi Energy announced an investment of USD 528 million to build a transformer manufacturing facility in Mississippi, U.S. The new facility will more than double the production capacity in the company’s existing operations in the region, meeting the wider demand for specialised electrical infrastructure.
- The increasing development of solid-state transformers and advanced power electronics is opening the door to more compact and efficient power conversion systems. Enphase Energy demonstrated its solid-state transformer technology in October 2026, converting 13.8 kV AC to 800 V DC with 132 power modules. The move underscores the potential for next-generation transformer technologies to carve out a market in AI data centres and high-density electrical applications.
- The growing emphasis on regional manufacturing and the expanding production capabilities are driving transformer manufacturers to grow their businesses. Siemens Energy India had in February 2026 said it will invest around INR 2,060 crore to increase its large power transformer manufacturing capacity by around 30,000 MVA. The additional capacity is expected to be available between 2030 and 2032.
Regional Insights
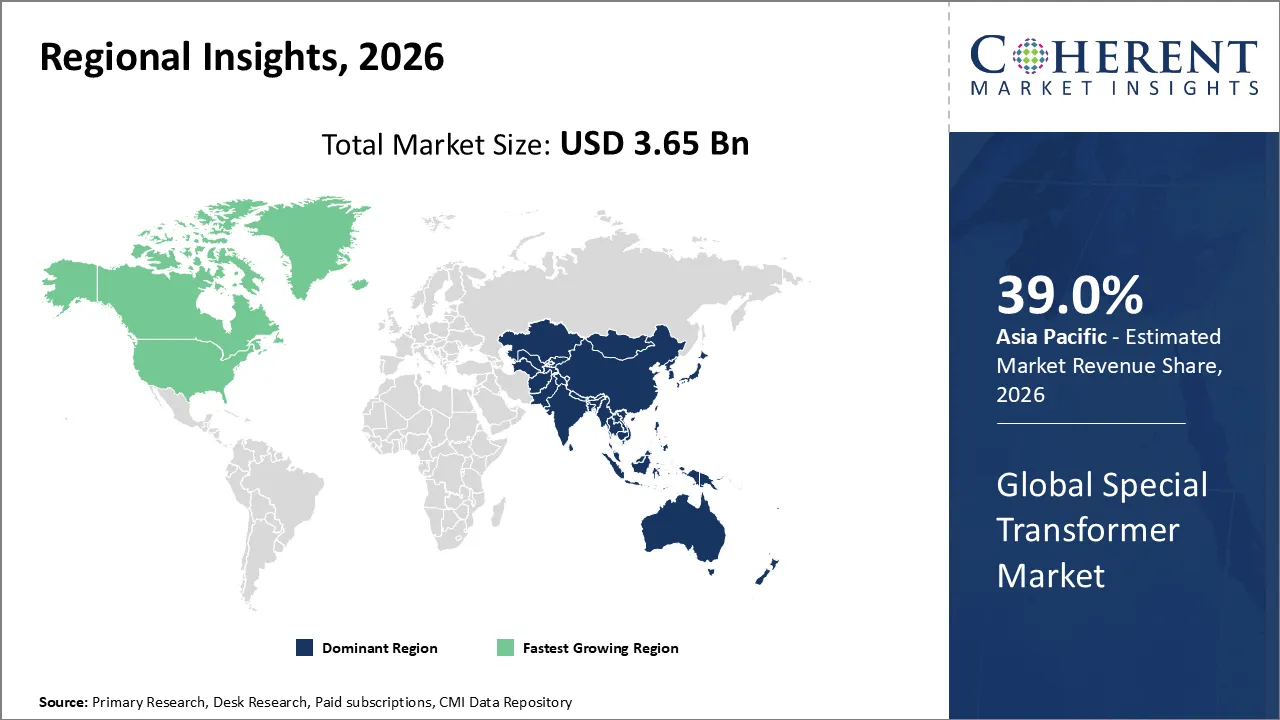
Asia Pacific Dominates Owing to Rapid Industrialization and Expansion of Transformer Manufacturing Infrastructure
The Asia Pacific region is estimated to account for the largest share of the Special Transformer Market, at 39.0%, in 2026. Increasing electricity consumption, increasing investments in high voltage electrical infrastructure, increasing industrial manufacturing activities and increasing adoption of specialised transformers across steel, chemical, renewable energy and transportation industries are supporting the growth of the region. China, India, Japan and South Korea are important markets because they already have electrical equipment manufacturing capabilities and are undergoing industrial modernisation.
In August 2026, Hitachi Energy announced an investment of USD 300 million to expand its manufacturing facilities for power transformers and components in Hefei, China. The investment will increase production capacity, relieve supply chain bottlenecks and improve availability of critical electrical grid equipment. The move highlights the region’s growing importance as a global hub for transformer manufacturing.
In June 2026, Hitachi Energy India announced an investment of approximately INR 2,000 crore to establish a new large power transformer manufacturing facility in Vadodara, Gujarat. The facility is scheduled for completion in FY 2028 and is expected to support high-voltage transmission, HVDC systems, power generation, and large-scale industrial applications.
North America Special Transformer Market Trends
North America is expected to witness significant growth in the Special Transformer Market during the forecast period. The region’s expansion is attributed to growing replacement of ageing electrical infrastructure, increasing electricity requirements from AI data centres, growing industrial electrification and increasing investments in domestic transformer manufacturing.
According to the U.S. Department of Energy’s analysis in October 2026 found that roughly 80 percent of U.S. power transformers and 50 percent of distribution transformers are made from imported equipment. The agency also notes long procurement lead times and limited domestic production capacity as major supply chain challenges.
In February 2026, Siemens Energy announced a USD 1 billion investment to expand its U.S. manufacturing operations for electricity grid and power generation equipment. The initiative involves expanding the production capacity of the transformers and generating more than 1,500 skilled jobs in the country.
Federal Grid Modernization Investments and Advanced Power Conversion Technologies are Accelerating the Special Transformer Market in the United States
The U.S. Special Transformer Market is experiencing a significant boom due to increased federal funding for upgrading the electricity grid, growing demand for high-voltage power conversion equipment, and expanding application of specialty transformers in utilities, industrial manufacturing, and critical infrastructure. Increasingly sophisticated power electronics, converter transformers and high voltage direct current (HVDC) technologies are offering opportunities to manufacturers of efficient and reliable electrical equipment.
The U.S. Department of Energy's Advanced Research Projects Agency-Energy (ARPA-E) announced in March 2026 funding of up to USD 35 million for 12 projects under its DC-GRIDS programme. The initiative aims to develop advanced HVDC converter technologies to enhance electricity transmission capacity and improve grid reliability.
In September 2026, the U.S. Department of Energy announced plans to support 31 projects to improve electricity grids in 26 states. The projects represent an investment of about USD 5.25 billion, including USD 1.9 billion in federal funds.
China's Special Transformer Market Growth is Driven by Ultra-High-Voltage Transmission Projects and Industrial Electrification
China Special Transformer Market is anticipated to grow significantly over the forecast period. Increasing investments in ultra-high-voltage transmission infrastructure, modernisation of industrial electricity networks, and the development of advanced power conversion technologies are driving the country’s growth. The need to transmit electricity over long distances and to integrate renewable energy sources effectively is increasing the opportunities for converters, phase-shifting and other special transformers.
In April 2026, China began construction of the Xizang–Guangdong ultra-high-voltage electricity transmission project, investing some CNY 53.2 billion (USD 7.76 billion). The project will cover a distance of about 2,681 kilometres and will have a transmission capacity of 10 GW. It has two converter stations of 8 GW and 5 GW respectively.
In December 2025, China’s National Development and Reform Commission announced an initial allocation of around CNY 295 billion (USD 42 billion) for major projects under its 2026 investment plan. The approved energy infrastructure projects included the Zhejiang ultra-high-voltage alternating-current ring grid.
Who are the Major Companies in Special Transformer Industry
Some of the major key players in Special Transformer Market are Mitsubishi Electric Corporation, Sunten Electric Equipment Co., Ltd., Siemens Ltd., Alstom, Schneider Electric, ABB, Wolong Electric Group Co., Ltd., Toshiba India Pvt. Ltd., TBEA India, Baoding Tianwei Group, Wuzhou Transformer Co., Ltd., and Jinan XD Special Transformer Co., Ltd.
Key News
- In July 2026, ABB completed the acquisition of Specialtrasfo S.p.A., an Italian manufacturer specializing in medium-voltage converter and rectifier transformers.
- In March 2026, Toshiba Energy Systems & Solutions Corporation received an order to refurbish Pole 1 of the Hokkaido-Honshu HVDC interconnection in Japan with a voltage-sourced converter HVDC system. The project is a sign of Toshiba’s growing engagement in the high-end electricity transmission and power conversion infrastructure sector, which is closely tied to demand for dedicated converter equipment.
Market Report Scope
Special Transformer Market Report Coverage
Report Coverage | Details | ||
Base Year: | 2025 | Market Size in 2026: | USD 3.65 Bn |
Historical Data for: | 2020 to 2024 | Forecast Period: | 2026 to 2033 |
CAGR: | 7.3% | 2033 Value Projection: | USD 5.97 Bn |
Geographies covered: |
| ||
Segments covered: |
| ||
Companies covered: | Mitsubishi Electric Corporation, Sunten Electric Equipment Co., Ltd., Siemens Ltd., Alstom, Schneider Electric, ABB, Wolong Electric Group Co., Ltd., Toshiba India Pvt. Ltd., TBEA India, Baoding Tianwei Group, Wuzhou Transformer Co., Ltd., and Jinan XD Special Transformer Co., Ltd. | ||
Growth Drivers: |
| ||
Restraints & Challenges: |
| ||
Analyst Opinion
- The Special Transformer Market is expected to be fueled by increasing investments in customized electrical infrastructure, especially in high voltage transmission, industrial power conversion and renewable energy integration. Reliable power management is required for the complex electricity networks. This in turn creates demand for the converter, rectifier and phase shifting transformers. The Grid Technologies business has an order backlog of some EUR 42 billion in the presentation of Siemens Energy on its Capital Markets Day on November 2025, nearly doubling between FY 2023 and FY 2025.
- Technological innovation and the optimization of transformer design are becoming important competitive factors in the market. Manufacturers are concentrating on efficient electrical materials, standard components, digital monitoring and improved production processes to reduce manufacturing complexity and procurement delays. The U.S. Department of Energy’s 2026 supply chain assessment identified more than 80,000 unique distribution transformer configurations in the U.S., illustrating the challenge of equipment customization and manufacturing standardization.
- The long-term competitive outlook for the Special Transformer Market is likely to be shaped by supply chain resilience and domestic manufacturing capabilities. Increased demand for custom electrical equipment, shortages of key materials and longer lead times are driving manufacturers to ramp up output capacity and source components. In August 2026, the U.S. Department of Energy announced plans for a supply chain programme to provide up to USD 375 million to support domestic manufacturing of transformers and other critical electrical grid components. The initiative emphasizes manufacturing efficiency, alternative materials, equipment refurbishment, and next-generation power electronics, supporting technological development across the wider transformer industry.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- By Product Type (Revenue, USD Bn, 2021-2033)
- Electric Arc Furnace Transformer
- Rectifier Transformer
- Capacitive Transformer
- Phase Shifting Transformer
- By Application (Revenue, USD Bn, 2021-2033)
- Rectification Equipment
- Welding Equipment
- Electric Furnace Power Supply
- Current Transformer
- By Region (Revenue, USD Bn, 2021-2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Rest of Latin America
- Europe
- Germany
- U.K.
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- South Africa
- Central Africa
- North Africa
- North America
Sources
Primary Research Interviews
- Special transformer manufacturers and suppliers
- Power transmission and distribution equipment manufacturers
- Electrical engineers and transformer design specialists
- R&D heads from transformer manufacturing companies
- Power utilities and electricity grid infrastructure experts
- Steel, oil and gas, renewable energy, and railway industry procurement managers
- Key opinion leaders (KOLs) in power electronics, industrial electrification, and transformer technologies
Databases
- World Bank
- Organisation for Economic Co-operation and Development (OECD)
- U.S. Department of Energy (DOE)
- U.S. Energy Information Administration (EIA)
- International Renewable Energy Agency (IRENA)
- International Trade Centre (ITC) – Trade Map
- UN Comtrade Database
- Eurostat
Magazines
- Transformer Technology
- T&D World
- Power Engineering
- Electrical Review
- Electrical India
- Power Line Magazine
- Electrical Engineering Magazine
Journals
- IEEE Transactions on Power Delivery
- IEEE Transactions on Power Systems
- IEEE Transactions on Industry Applications
- IEEE Transactions on Industrial Electronics
- Electric Power Systems Research
- International Journal of Electrical Power & Energy Systems
- IET Generation, Transmission & Distribution
- Energies
Newspapers
- The Wall Street Journal
- Financial Times
- Reuters
- The Economic Times
- Business Standard
- The Hindu BusinessLine
- Nikkei Asia
Associations
- Institute of Electrical and Electronics Engineers (IEEE)
- International Council on Large Electric Systems (CIGRE)
- National Electrical Manufacturers Association (NEMA)
- International Electrotechnical Commission (IEC)
- World Steel Association (worldsteel)
- European Power Transmission and Distribution Association (EPTDA)
- Electrical Equipment Manufacturers Association of India (IEEMA)
- International Renewable Energy Agency (IRENA)
Public Domain Sources
- Company Annual Reports and Investor Presentations
- Government Electricity Transmission and Distribution Infrastructure Reports
- National Electricity Plans and Grid Modernization Publications
- U.S. Department of Energy Research and Technical Reports
- International Renewable Energy Agency Publications
- Publicly Available Transformer Manufacturing and Technology Development Reports
- Patent Databases such as WIPO, USPTO, and Google Patents
- Regulatory and Standards Publications Related to Transformer Efficiency and Electrical Safety
- Company Press Releases and Product Launch Announcements
- Publicly Available Electricity Generation, Industrial Production, and Infrastructure Investment Statistics
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of Information for the Last 10 Years
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Special Transformer Market is expected to reach USD 5.97 Bn by 2033, increasing from USD 3.65 Bn in 2026.
Major players operating in the global Special Transformer Market include Mitsubishi Electric Corporation, Sunten Electric Equipment Co., Ltd., Siemens Ltd., Alstom, Schneider Electric, ABB, Wolong Electric Group Co., Ltd., Toshiba India Pvt. Ltd., TBEA India, Baoding Tianwei Group, Wuzhou Transformer Co., Ltd., and Jinan XD Special Transformer Co., Ltd.
High initial investment costs, fluctuating raw material prices, complex customization requirements, extended manufacturing lead times, and supply chain disruptions are the key factors hampering market growth.
Increasing investments in power transmission and distribution infrastructure, rising industrial electrification, growing renewable energy integration, and expansion of railway electrification projects are boosting demand for special transformers.
The Special Transformer Market is anticipated to grow at a CAGR of approximately 7.3% between 2026 and 2033.
Among regions, Asia Pacific is estimated to account for the largest share of the global Special Transformer Market, with approximately 39.0% in 2026, supported by expanding industrial infrastructure and electricity transmission investments.
A special transformer is a customized electrical transformer designed for specific industrial or power system applications requiring specialized voltage regulation, high-current capacity, power conversion, or unique operating conditions.