
Specialty Injectable Generics Market Size and Forecast – 2026 to 2033
The Specialty Injectable Generics Market is estimated to be valued at USD 21.78 Bn in 2026 and is expected to reach USD 36.62 Bn by 2033, exhibiting a compound annual growth rate (CAGR) of 7.8% from 2026 to 2033.
Key Takeaways
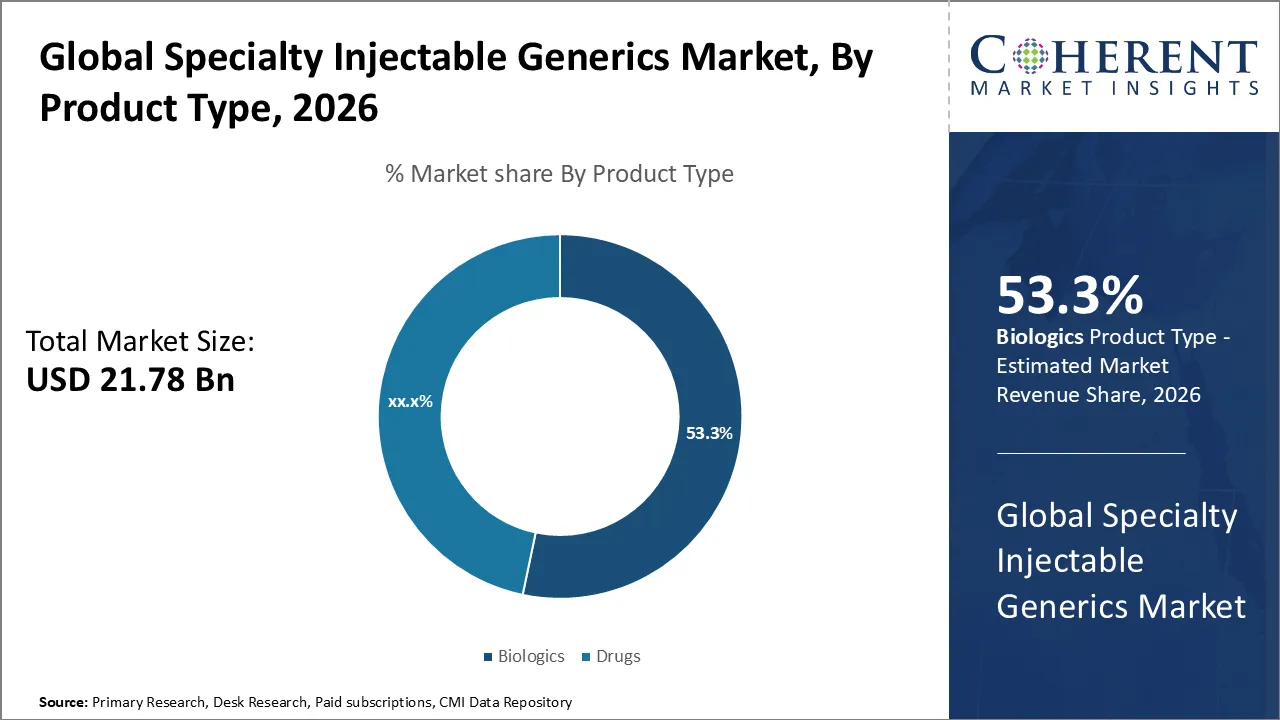
- By Product Type, Biologics hold the largest market share of 53.3% in 2026 owing to the patent expirations of biologic drugs.
- By Application, Oncology expected to hold largest market share of 37.7% in 2026 owing to its rising global incidence of cancer.
- By Distribution Channel, Hospital Pharmacies acquired the prominent market share of 46.6% in 2026 owing to the high utilization of injectables in clinical care.
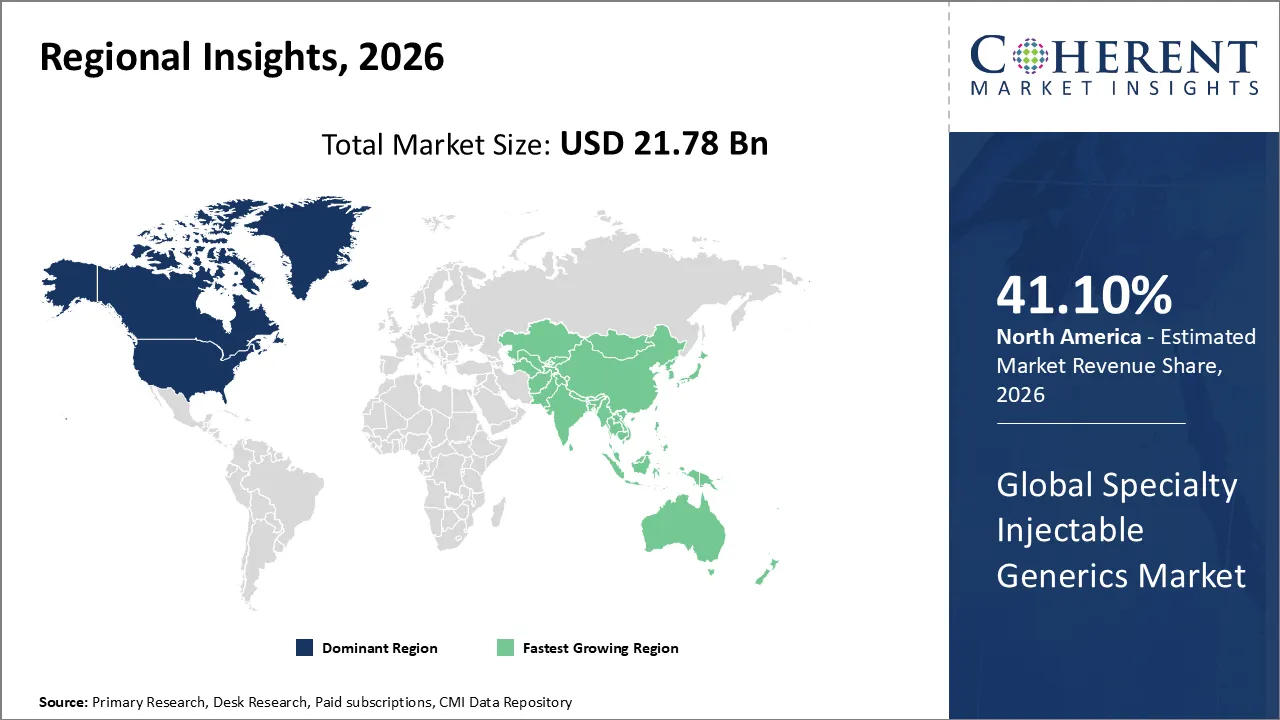
- By Region, North America dominates the overall market with an estimated share of 41.1% in 2026 owing to the well‑established healthcare infrastructure.
Market Overview
The specialty injectable generics market delivers complex injectable therapies across hospital, oncology, and chronic care settings. Increasing demand for cost-effective alternatives to branded biologics, along with the rising prevalence of chronic and life-threatening diseases, drives market growth. Advances in sterile manufacturing and delivery technologies accelerate adoption, while supportive regulatory frameworks and expanding hospital and outpatient infrastructure enable wider use. The market offers biosimilars, oncology injectables, and other specialty generics, promoting affordable, accessible, and clinically effective injectable treatments worldwide.
Current Events and Its Impacts on the Specialty Injectable Generics Market
Current Events | Description and its impact |
Regulatory and Policy Changes in Key Markets |
|
Supply Chain Disruptions and Raw Material Constraints |
|
Macroeconomic and Geopolitical Influences |
|
Segmental Insights
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Specialty Injectable Generics Market Insights, By Product Type: Biologics contribute the highest share of the market owing to its growing adoption & acceptance of biosimilars.
Biologics hold the largest market share of 53.3% in 2026. The Specialty Injectable Generics Market expands as companies capitalize on the expiration of patents for high-value biologic drugs, offering cost-effective alternatives. Rising cases of chronic and complex diseases boost demand for advanced injectable therapies, while healthcare systems actively pursue affordable treatment options. Manufacturers improve production efficiency and patient convenience through innovations in formulation, delivery, and sterile manufacturing technologies. Supportive regulatory pathways and increasing clinical acceptance further drive adoption, enabling biologic generics to reach a wider patient population worldwide. In December 2025, Sun Pharmaceutical Industries, a global specialty pharmaceutical leader, unveiled Ilumya (tildrakizumab) in India for treating moderate to severe plaque psoriasis. This novel biologic targets IL-23 and has achieved blockbuster status globally, with availability in 35 countries, including the United States.
Specialty Injectable Generics Market Insights, By Application: Oncology contributes the highest share of the market owing to its cost‑containment pressures in healthcare.
Oncology expected to hold largest market share of 37.7% in 2026. The Oncology segment of the Specialty Injectable Generics Market expands as hospitals and clinics adopt affordable alternatives to costly branded cancer therapies. Rising cancer rates and increasing demand for targeted injectable treatments drive this growth. Manufacturers enhance efficiency by applying advances in sterile production and biosimilar development, while regulatory frameworks accelerate approval of complex generics. Healthcare providers actively prioritize cost-effective oncology solutions, improving accessibility and promoting broader integration of injectable generics into cancer treatment protocols worldwide.
In November 2025, Zydus Lifesciences Ltd announced that it received final approval from the US Food and Drug Administration for its generic Leuprolide Acetate injection, indicated for the palliative treatment of advanced prostate cancer.
Specialty Injectable Generics Market Insights, By Distribution Channel: Hospital Pharmacies contribute the highest share of the market owing to its centralized procurement & bulk purchasing benefits.
Hospital Pharmacies acquired the prominent market share of 46.6% in 2026. Hospital pharmacies actively boost the Specialty Injectable Generics Market by supplying cost-effective, high-demand injectable therapies for both inpatient and outpatient care. They secure affordable generics and biosimilars through centralized procurement and large-scale purchasing, ensuring critical treatments remain continuously available. Rising rates of chronic and complex diseases increase their reliance on injectable therapies, while advances in sterile manufacturing and convenient delivery systems enhance operational efficiency. By integrating these products into formularies and clinical protocols, hospital pharmacies actively expand the adoption of specialty injectable generics. For instance, in December 2025, Danish drugmaker Novo Nordisk unveiled diabetes drug Ozempic in India.
Regional Insights
North America Specialty Injectable Generics Market Trends
North America dominates the overall market with an estimated share of 41.10% in 2026. The North America Specialty Injectable Generics Market expands as hospitals, oncology centers, and chronic care facilities increasingly adopt affordable alternatives to expensive branded injectables. Rising cases of complex and chronic diseases drive higher usage, while regulatory frameworks actively facilitate faster approval of biosimilars and complex generics. Strong healthcare infrastructure and centralized procurement systems allow efficient distribution and adoption. Manufacturers apply advances in sterile production and innovative delivery technologies, and growing clinical acceptance further strengthens the market, establishing North America as a leading region for specialty injectable generics. For instance, in November 2025, Lupin Limited has introduced Risperidone Long-Acting Injectable in the U.S. market with 180-day Competitive Generic Therapy exclusivity. The antipsychotic treatment is available in 25 mg, 37.5 mg, and 50 mg strengths.
Asia Pacific Specialty Injectable Generics Market Trends
The Asia Pacific Specialty Injectable Generics Market grows as hospitals and specialty clinics increasingly adopt advanced injectable therapies while healthcare systems modernize. Greater awareness of cost-effective alternatives drives use, especially in oncology, chronic, and infectious disease treatments. Governments and regulatory authorities actively support biosimilar and generic approvals, and local manufacturers strengthen supply chains. Rising demand for outpatient and home-care injectable solutions, along with advancements in sterile manufacturing and delivery technologies, actively fuels the region’s rapid development in specialty injectable generics.
United States Specialty Injectable Generics Market Trends
The United States Specialty Injectable Generics Market grows as hospitals, clinics, and specialty care centers actively adopt cost-effective alternatives to branded injectables. Increasing cases of chronic and complex diseases drive higher demand for injectable therapies in oncology, autoimmune, and critical care treatments. Regulatory authorities support the market through streamlined approval pathways, promoting the launch of biosimilars and complex generics, while manufacturers enhance efficiency and patient convenience with advanced production and delivery technologies. Centralized procurement and formulary integration further boost adoption, positioning the U.S. as a key market for specialty injectable generics. For instance, Avenacy has launched Dexmedetomidine Injection, USP in the United States as an FDA-approved therapeutic generic equivalent to Precedex®.
China Specialty Injectable Generics Market Trends
China’s Specialty Injectable Generics Market grows rapidly as hospitals and specialty clinics actively adopt affordable injectable therapies to address increasing patient demand. Rising cases of chronic, oncologic, and infectious diseases drive extensive use of generics and biosimilars. The government and regulatory authorities actively support approvals through evolving policies, while local manufacturers strengthen supply chains. Advances in sterile production, innovative delivery systems, and hospital procurement practices improve accessibility, positioning China as a dynamic and fast-developing market for specialty injectable generics.
End-User Feedback and Unmet Needs in the Specialty Injectable Generics Market
- Cost and Affordability Concerns: End-users, including hospitals and patients, emphasize the need for more affordable injectable therapies to reduce treatment expenses. Despite generics being lower-priced alternatives, high costs of complex biologics and specialty injectables still challenge budgets, particularly in chronic care and oncology, prompting demand for broader price accessibility and reimbursement support.
- Availability and Supply Consistency: Healthcare providers report challenges in maintaining a continuous supply of specialty injectables. Stock-outs or delayed deliveries disrupt patient care, especially in hospitals and infusion centers. Users seek reliable supply chains, improved manufacturing scalability, and better distribution strategies to ensure uninterrupted access to critical injectable treatments.
- Ease of Administration: Clinicians and patients highlight the need for user-friendly delivery systems. Complicated preparation, handling, or injection procedures increase errors and reduce adherence. End-users prefer prefilled syringes, auto-injectors, or ready-to-use formulations that simplify administration while maintaining safety and sterility, particularly for home-based or outpatient care.
Specialty Injectable Generics Market Trend
Shift Towards Biosimilars and Biologics
The market increasingly emphasizes biosimilars and complex biologic injectables as patents on high-cost branded drugs expire. Manufacturers focus on replicating efficacy and safety profiles while offering cost-effective alternatives. Healthcare providers actively adopt these therapies to manage rising treatment costs and expand patient access. The trend also reflects growing confidence among clinicians and regulators in biosimilar safety, fueling broader acceptance and integration into hospital formularies and outpatient care protocols worldwide.
Expansion of Hospital and Specialty Care Adoption
Hospitals, oncology centers, and specialty clinics drive demand for injectable generics due to high patient throughput and critical treatment needs. Centralized procurement and formulary management support large-scale adoption, while end-users prioritize reliable supply and affordability. Increased integration into clinical workflows ensures that injectable generics are used efficiently for chronic, acute, and specialty care treatments, reinforcing hospitals and specialty centers as key channels shaping the market’s growth and long-term sustainability.
Specialty Injectable Generics Market Opportunity
Rising Demand for Cost-Effective Therapies
The escalating costs of branded biologics and specialty injectables present a significant opportunity for generics and biosimilars. Hospitals, clinics, and outpatient centers actively seek affordable alternatives to maintain patient access while managing budgets. Manufacturers can leverage this demand by introducing clinically equivalent, lower-cost injectable therapies that address chronic, oncology, and critical care needs, creating value for healthcare providers, payers, and patients while capturing a growing share in a cost-conscious market.
Market Report Scope
Specialty Injectable Generics Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 21.78 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 7.8% | 2033 Value Projection: | USD 36.62 Bn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | Pfizer, Inc., Teva Pharmaceutical Industries Ltd., Novartis AG, Baxter International Inc., Mylan N.V., Fresenius SE & Co. KGaA, Endo International Plc., Hikma Pharmaceuticals PLC, Lupin Ltd., Sagent Pharmaceuticals, Inc., Cipla Limited , Sun Pharmaceutical Industries Limited, and Dr. Reddy's Laboratories. | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Specialty Injectable Generics Market News
- In February 2025, Avenacy introduced doxycycline for injection, a generic version of Fresenius Kabi’s DOXY 100. The broad-spectrum antibiotic treats infections caused by susceptible gram-positive and gram-negative bacteria, rickettsiae, spirochetes, and other organisms.
- In March 2025, Avenacy launched zoledronic acid injection, a generic version of Novartis’ Zometa. The injectable treats hypercalcemia of malignancy and supports therapy for multiple myeloma and bone metastases from solid tumors.
Analyst Opinion (Expert Opinion)
- The Specialty Injectable Generics Market is transitioning from a cost‑containment niche to a central strategic priority for healthcare systems, driven by documented shifts in therapeutic utilization and procurement behaviour. Hospital adoption of specialty injectable generics now exceeds 67 percent, with real‑world analytics deployed to reduce formulary disruptions and mitigate supply shortages — an indicator of deepening clinical trust and operational dependence on these products.
- The FDA’s performance underscores the evolving regulatory environment: biosimilar injectable approvals grew by more than 24 percent, reflecting enhanced pathways and manufacturer expertise. This performance is significant because it evidences not just pipeline expansion but tangible shifts in regulatory confidence and industry capability to meet complex sterility and bioequivalence requirements.
- Nevertheless, the manufacturing landscape remains a structural constraint. Sterile production bottlenecks are reported by approximately 42 percent of facilities, and nearly one‑third of hospitals cite supply fluctuations as a barrier to stable inventory management — underscoring that operational execution now competes with product availability as a strategic risk.
- Emerging delivery technologies — such as ready‑to‑use formats and prefilled syringes, which have seen adoption increases approaching 31 percent — are not merely convenience innovations but are reshaping clinical preference hierarchies, reducing medication error rates and preparation time in high‑throughput settings. This transition signals an irreversible shift toward product differentiation in what was once a purely price‑driven segment.
- In summary, the Specialty Injectable Generics Market is maturing into a sophisticated ecosystem where regulatory alignment, manufacturing excellence, and clinical integration converge. The market’s evolution is less about generic substitution and more about embedding high‑quality, complex injectables into mainstream therapeutic architectures, reflecting a fundamental redefinition of value in specialty care delivery.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- By Product Type
- Drugs
- Biologics
- By Application
- Oncology
- Cardiovascular Diseases
- Central Nervous System Diseases
- Infectious Diseases
- Auto-immune Disorders
- Others
- By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- By Regional Insights
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC Countries
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
- North America
- Key Players Insights
- Pfizer, Inc.
- Teva Pharmaceutical Industries Ltd.
- Novartis AG
- Baxter International Inc.
- Mylan N.V.
- Fresenius SE & Co. KGaA
- Endo International Plc.
- Hikma Pharmaceuticals PLC
- Lupin Ltd.
- Sagent Pharmaceuticals, Inc.
- Cipla Limited
- Sun Pharmaceutical Industries Limited
- Reddy's Laboratories
Sources
Primary Research interviews
- Interviews with hospital pharmacists, oncology specialists, and clinicians involved in chronic care management
- Discussions with R&D heads and manufacturing personnel from pharmaceutical and biologics companies
- Insights from procurement managers and formulary decision-makers at tertiary and specialty care hospitals
Databases
- U.S. FDA Biologics and Drug Approval Databases
- ClinicalTrials.gov for ongoing and completed injectable therapy trials
- World Health Organization (WHO) Global Health Observatory
- PubChem and DrugBank for drug-specific information and bioequivalence data
Magazines
- Pharmaceutical Technology
- BioPharma-Reporter
- The Pharma Letter
- Hospital Pharmacy Europe
Journals
- Journal of Pharmaceutical Sciences
- The Lancet Oncology
- Clinical Therapeutics
- Journal of Managed Care & Specialty Pharmacy (JMCP)
- Biotechnology and Bioengineering
Newspapers
- The New York Times – Health Section
- The Guardian – Health and Medicine
- The Wall Street Journal – Health & Pharma Coverage
- The Times of India – Health News
Associations
- International Society for Pharmaceutical Engineering (ISPE)
- American Society of Health-System Pharmacists (ASHP)
- Biotechnology Innovation Organization (BIO)
- European Federation of Pharmaceutical Industries and Associations (EFPIA)
Public Domain sources
- WHO Reports on Pharmaceutical Access and Generics
- U.S. Centers for Medicare & Medicaid Services (CMS) Drug Data
- National Institutes of Health (NIH) Publications
- Government patent expiry and drug exclusivity databases
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of information for last 8 years
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Specialty Injectable Generics Market is estimated to be valued at USD 21.78 Bn in 2026 and is expected to reach USD 36.62 Bn by 2033.
The CAGR of the Specialty Injectable Generics Market is projected to be 7.5% from 2026 to 2033.
Key challenges include complex manufacturing requirements, stringent quality standards, regulatory variations across regions, and limited awareness or acceptance among some healthcare providers.
North America dominates the market due to strong healthcare infrastructure and supportive regulations.
Innovations include prefilled syringes, ready-to-use formulations, auto-injectors, and advanced sterile manufacturing technologies.