

Vehicle Electrification Market Size and Trends
The Vehicle Electrification Market is estimated to be valued at USD 136.75 Bn in 2026 and is expected to reach USD 287.52 Bn by 2033, exhibiting a compound annual growth rate (CAGR) of 11.2% from 2026 to 2033.
Key Takeaways
- Based on Product Type, the Start/Stop System segment leads the market holding an estimated share of 19% in 2026, due to powerful underlying factors driving consumer demand.
- Based on Degree of Hybridization, the Battery Electric Vehicle (BEV) segment is expected to account for largest share of the global vehicle electrification market in 2026, as it offers a truly zero-emissions option.
- Based on Region, Asia Pacific is estimated to lead the market with a share of 38. 7% in 2026. While, North America is projected to be the fastest growing region during the forecast period with 12.77% share in the vehicle electrification market.

Market overview
The global vehicle electrification market is experiencing significant expansion as automotive and transport sectors prioritize sustainability, energy efficiency, and electrified propulsion systems. Accelerating growth in all vehicle categories from passenger cars to heavy commercial trucks is being fueled by environmental regulations, technology innovation, and shifting consumer preferences. Together, these trends are driving strong vehicle electrification market demand worldwide.
Current Events and Its Impact on the Vehicle Electrification Market
Current Event | Description and its Impact |
Regulatory Shifts in Key Markets |
|
Economic and Environmental Policy Pressures |
|
Price Analysis of the Vehicle Electrification Market
Vehicle Segment | Typical Price Range (USD) | Notes / Examples |
Entry‑Level EVs (City cars) | $20,000 – $30,000 / €15,000–30,000 | Affordable models like Dacia Spring and Leapmotor T03; used in Europe and emerging markets |
Mid‑Range SUVs & Sedans | $40,000 – $70,000 / ₹20–30 lakh (~$24k–36k) | Includes Tesla Model 3, Peugeot e‑3008; in India, models like Tata Nexon EV and Hyundai Creta EV range from ₹12–28 lakh. |
Premium EVs (Luxury) | $80,000+ | Tesla Model EQS X, Mercedes, and Rivian R1T; premium electrified vehicles for longer range and upscale features |
Electric Pickup Trucks | $63,000 – $100,000+ | Ford F‑150 Lightning ($80k), Rivian R1T ($97k–100k) |
Electric Buses (City transit) | ₹1 crore – ₹2 crore (~US $120,000–250,000) | Tata Starbus EV (~₹2.2 crore), Olectra K9 (₹2.5–3 crore), Switch Mobility EiV12 (₹40–70 lakh) |
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Segmental Insights

Vehicle Electrification Market Insights, By Product Type - Start/Stop System Acquires the Largest Share owing to Growing Consumer Demand
In terms of product type, the start/stop system segment is expected to hold the highest share of 19% in 2026, due to powerful underlying factors driving consumer demand. As fuel economy and emission standards continue to tighten globally, automakers are under increasing pressure to reduce the fuel consumption and emissions of new vehicles. The start/stop system provides an affordable and effective solution to meet these goals. Unlike some other electrification technologies, start/stop systems can be easily integrated into existing internal combustion engine (ICE) vehicle architectures with minimal upgrades required. This has made them appealing for automakers looking to quickly electrify their model lines without a complete redesign.
On the consumer side, drivers have become more environmentally conscious and concerned about high fuel costs. The promise of improved fuel efficiency from start/stop technology without compromising driving dynamics or convenience is propelling the adoption of vehicle electrification. For instance, according to the Department of Energy the automatic stop/start yields real-world improvements in emissions reduction and fuel savings. Along with that, it reduces auto emissions and provide fuel savings of as much as 10% over traditional ICE platforms.
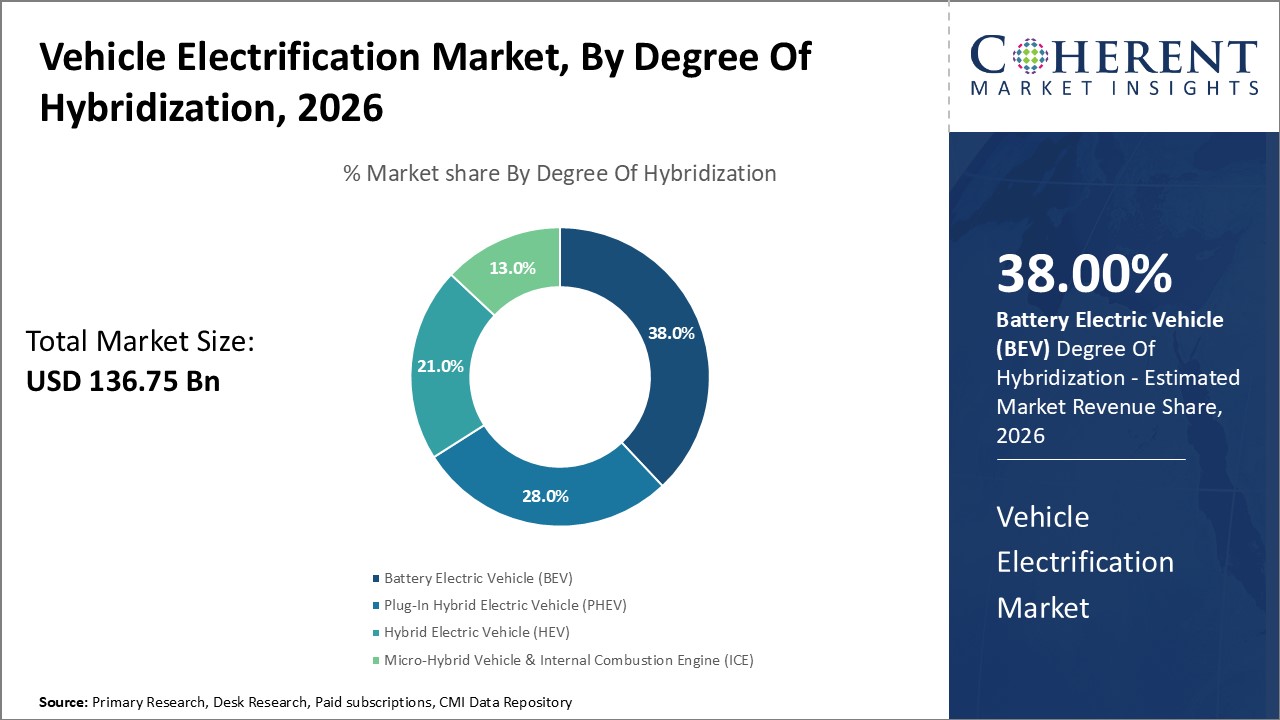
Vehicle Electrification Market Insights, By Degree of Hybridization - Battery Electric Vehicle Component Drives the Growth Due to Zero-Emission Ability
In terms of degree of hybridization, the battery electric vehicle segment has acquires the largest vehicle electronification market share in 2026, as BEVs offer a truly zero-emissions option that is appealing to both environmentalists and those concerned with urban air quality issues from vehicle pollutants. They are also incentivized through supportive government policies in major markets such as Europe and China considering to curb their CO2 emissions. For example, Norway has led the world with generous purchase subsidies and tax exemptions that have made BEVs very attractive to buyers.
Technological progress is expanding vehicle ranges and addressing range anxiety concerns that had previously held BEV adoption back. New high-capacity lithium-ion battery packs allow for EPA-rated distances over 250 miles on a single charge for some models. Widespread installation of public fast-charging stations is shortening recharge times from hours to minutes.
In November 2024, Suzuki Motor Corporation unveiled its first mass‑production battery electric vehicle (BEV), the e VITARA, in Milan. Inspired by the eVX concept, it blends advanced BEV tech with SUV robustness under the “High‑Tech & Adventure” theme.
Regional Insights

Asia Pacific Vehicle Electrification Market Analysis & Trends
Asia Pacific has been the dominant player in the vehicle electrification market for years and is expected to hold the largest share of 38.7% in 2026, due to China which has emerged as the fastest growing regional market in recent times. Aggressive targets set by the Chinese government to increase electric vehicle production and use have accelerated investments and innovations in the industry. Several new EV startups are coming up in China which are making affordable electric cars that appeal to local customers. At the same time, established automakers like BYD and SAIC are rapidly expanding their electric model lineups. China's large automobile market size and growing preference for new technologies among consumers have accelerated this shift towards electrification. In addition, lower costs of manufacturing EVs in China compared to other regions have made them more competitive in global markets as well. As a result, China has overtaken other regions to become the largest EV market and is surpassing production targets well ahead of schedule.
In January 2026, Vietnamese automaker VinFast announced its entry into India with two premium electric SUVs, VF 6 and VF 7, aimed at challenging rivals such as Mahindra & Mahindra and BYD. They are launched at the Bharat Mobility Global Expo 2026, both right-hand‑drive models are tailored for Indian consumers and supported by plans for a ₹4,150 crore EV manufacturing investment in Tamil Nadu.
North America Vehicle Electrification Market Analysis & Trends
North America, holding a share of 12.77% in 2026, is expected to maintain the fastest growth in the vehicle electrification market, driven by the large presence of major automotive OEMs like Tesla, GM, and Ford have driven significant investments in research and development of electric technologies. With their headquarters and major manufacturing facilities located in the U.S. and Canada, these companies have been at the forefront of developing electric vehicles. In addition, supportive government policies like tax incentives and emissions regulations have encouraged higher adoption of electric vehicles in the region. As a result, North America accounts for the largest share of electric vehicle sales globally. According to the International Energy Agency, In the United States, electric car sales increased to 1.6 million in 2024, with the sales share growing to more than 10%.
In May 2026, Toyota Motor Corp. announced to ramp up its U.S. electric-vehicle plans, announcing the domestic production of two all-electric models slated to begin in 2026. These new battery-powered vehicles will be built at its largest U.S. factories in Georgetown, Kentucky, and Princeton, Indiana. By mid‑2027, Toyota aims to expand its American EV lineup to seven models, including three imports such as the bZ Woodland and Lexus ES EV.
Vehicle Electrification Market Outlook Country-Wise
China Vehicle Electrification Market Trends
China leads the global vehicle electrification market due to strong government incentives, robust manufacturing, and high consumer adoption. In 2024, it accounted for over 60% of global EV sales, with cities like Shenzhen achieving full electrification of public bus fleets. Major players like BYD and CATL dominate EV production and battery supply, while expanding exports globally. With ongoing subsidies and aggressive policy targets, China remains a key driver of vehicle electrification market growth worldwide.
The U.S. Vehicle Electrification Market Trends
The U.S. is experiencing strong vehicle electrification market demand, driven by federal incentives under the Inflation Reduction Act (IRA) and growing EV infrastructure. Automakers like Ford and GM are investing billions in EV production, while Tesla continues to lead in both sales and charging networks. The government’s goal for 50% EV sales by 2030, along with initiatives like the NEVI Program, is accelerating adoption and making the U.S. a key market for vehicle electrification market growth.
Germany Vehicle Electrification Market Trends
Germany is a key driver of vehicle electrification market, supported by its strong auto industry and ambitious climate goals. Major automakers like Volkswagen and BMW are rapidly scaling up EV production, backed by government incentives such as purchase subsidies and tax breaks. In 2024, Volkswagen began converting its Wolfsburg plant for next-gen EVs, while BMW expanded its Leipzig facility. Germany is also investing heavily in charging infrastructure, aiming for 1 million public chargers by 2030, reinforcing its leadership in clean mobility.
Market Concentration and Competitive Landscape

Recent Developments
- In May 2025, Mitsubishi Motors Corporation introduced an all‑new battery-electric vehicle (BEV) in North America during the second half of 2026. The model, developed by Nissan and based on the next‑generation Leaf, will be sold under Mitsubishi’s brand through its U.S. and Canadian dealer networks.
- In February 2025, Kia Corporation has detailed its updated Plan S 2030 strategy, aiming to sell 4 lakh vehicles annually in India by 2030. The plan includes a local rollout of compact electric SUVs and hybrid models, with electrified vehicles to account for 43% of India sales by 2030.
- In January 2025, SEG Automotive launched a comprehensive portfolio of electrification solutions for the Indian market and beyond. The company revealed a high-voltage platform supporting up to 800 V and 300 kW for passenger cars and commercial vehicles, with customizable options from individual stators and rotors to full system units.
- In October 2024, Nissan announced it will introduce affordable on‑board bi‑directional charging (Vehicle‑to‑Grid or V2G) on select electric vehicles beginning in 2026.
Market Report Scope
Vehicle Electrification Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 136.75 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 11.2% | 2033 Value Projection: | USD 287.52 Bn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | AISIN CORPORATION, Aptiv, BorgWarner Inc., Continental AG, DENSO CORPORATION, Hitachi Astemo, Ltd., Johnson Controls, Johnson Electric Holdings Limited, JTEKT Corporation, Magna International Inc., Mitsubishi Electric Corporation, Robert Bosch GmbH, Valeo SA, Wabco Holdings Inc., and ZF Friedrichshafen AG | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Vehicle Electrification Market Driver
Climate Change Concerns
Government policies and regulations regarding vehicular emissions have become stricter over the years with growing climate change concerns. In March 2024, the EPA finalized stricter emissions standards for light- and medium-duty vehicles, starting with model year 2027 and phasing in through 2032. Building on the 2021 standards for model years 2023–2026, the new rule aims to cut smog-, soot-, and climate-related pollution, improve public health, and lower fuel and maintenance costs for drivers by promoting cleaner vehicle technologies. Transportation accounts for a major portion of global greenhouse gas emissions, and there is a pressing need to reduce the carbon footprint of passenger and commercial vehicles. Electric powertrains such as hybrids, plug-in hybrids, and battery electric vehicles generate fewer emissions over their lifecycle compared to conventional internal combustion engine vehicles. Major economies around the world have outlined ambitious targets to curb emissions and have introduced incentives and subsidies to promote the adoption of electric vehicles.
Customers are also gradually becoming more environmentally conscious and are willing to pay more for electric vehicles, considering the long-term benefits. The automotive industry is actively working to develop affordable electric vehicles with an improved driving range. Meanwhile, governments are investing heavily in public charging infrastructure to allay range anxiety issues. These combined efforts are poised to significantly increase the vehicle electrification market share as nations pursue their climate and emissions objectives.
Vehicle Electrification Market Opportunity
Expanding Consumer Market
Government policies pushing for electrification through regulations and incentives will drive automaker investments, supporting the vehicle electrification market forecast. As battery and motor technologies improve, EVs are projected to reach price parity with gas vehicles this decade. This will expand the potential customer base. The growing concern over air pollution and climate change boost social acceptance of EVs.
Analyst Opinion (Expert Opinion)
The vehicle electrification market value is no longer in a phase of experimentation; it has transitioned into a phase of strategic consolidation and technological prioritization.
In power electronics, for example, wide-bandgap semiconductors such as silicon carbide (SiC) are rewriting efficiency norms. Tesla’s decision to adopt SiC-based inverters in the Model 3 resulted in up to a 10% range increase, with similar strategies now being adopted by Mercedes-Benz and Hyundai. These are not incremental enhancements, they are architectural shifts enabling faster charging, higher power density, and reduced thermal stress. Companies still relying on legacy silicon MOSFETs in EV powertrains will find themselves outperformed on both range and durability.
Battery chemistries are also at a strategic inflection point. While lithium iron phosphate (LFP) cells dominate the mid-segment EV landscape due to cost advantages and thermal stability, the transition to high-nickel NMC chemistries (e.g., NMC 811) for premium applications illustrates a growing bifurcation in battery strategies. Automakers like BMW and General Motors are investing heavily in high-energy-density cells to support larger vehicles and performance models, but this requires a robust supply of cobalt and nickel, both subject to geopolitical and ESG volatility. This, in turn, is accelerating interest in solid-state technologies, which Toyota and QuantumScape claim could deliver energy densities above 400 Wh/kg by the decade’s end.
Furthermore, the role of 48V mild hybrid systems, often overlooked in favor of pure EV narratives, deserves greater recognition. In Europe, nearly 30% of new vehicles sold in 2024 were equipped with 48V systems, driven largely by stringent CO₂ regulations. These systems offer an efficient bridge for OEMs to meet regulatory compliance while deferring the cost and complexity of full BEV platforms. From an electrification strategy standpoint, they serve as a margin-preserving stopgap for automakers with limited battery supply or immature EV architectures.
Regulatory push remains a dominant tailwind, but its impact is asymmetric. For instance, the U.S. Inflation Reduction Act (IRA) offers material advantages to OEMs assembling batteries and vehicles domestically, which is already shifting battery production footprints. Ford’s decision to invest over $3.5 billion in a Michigan LFP plant, in partnership with CATL, reflects this policy-induced industrial realignment. However, Chinese firms such as BYD and NIO, which control both vertical battery supply and cost-efficient e-platforms, continue to demonstrate that technological depth often trumps regulatory tailwinds in achieving sustainable competitive advantage.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- Product Type (Revenue, USD Bn, 2021 - 2033)
- Start/Stop System
- Electric Power Steering (EPS)
- Electric Air-Conditioner Compressor
- Electric Vacuum Pump
- Electric Oil Pump
- Electric Water Pump
- Liquid Heater PTC
- Integrated Starter Generator (ISG)
- Starter Motor
- Alternator
- Actuator Start/Stop System
- Degree of Hybridization
- Battery Electric Vehicle (BEV)
- Plug-In Hybrid Electric Vehicle (PHEV)
- Hybrid Electric Vehicle (HEV)
- Micro-Hybrid Vehicle & Internal Combustion Engine (ICE)
- Regional
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC Countries
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
- North America
- Key Players Insights
- AISIN CORPORATION
- Aptiv
- BorgWarner Inc.
- Continental AG
- DENSO CORPORATION
- Hitachi Astemo, Ltd.
- Johnson Controls
- Johnson Electric Holdings Limited
- JTEKT Corporation
- Magna International Inc.
- Mitsubishi Electric Corporation
- Robert Bosch GmbH
- Valeo SA
- Wabco Holdings Inc.
- ZF Friedrichshafen AG
Sources
Primary Research Interviews from the following Stakeholders
Stakeholders
- Interviews with electric vehicle (EV) manufacturers, battery cell suppliers, charging infrastructure providers, fleet operators, and powertrain engineers across major automotive regions.
Specific stakeholders
- Vehicle electrification leads at global OEMs
- Operations managers at EV charging network operators
- Power electronics and drivetrain engineers at component suppliers (e.g., Infineon, Bosch, Aisin)
- Sustainability heads and ESG compliance officers in logistics firms and e-mobility startups
- City transport planners and EV policy advisors in government departments
- Procurement and fleet managers at public transport corporations and e-commerce delivery companies
Databases
- International Energy Agency (IEA) – EV Outlook Reports
- UN Comtrade Database – Automotive Component Trade
- Bureau of Economic Analysis (U.S.) – EV-related Investment Data
- Eurostat – Automotive Electrification Statistics
- Ministry of Heavy Industries (India) – FAME Scheme Data
- Japan Automobile Manufacturers Association (JAMA) – Electrification Trends
- Korea Automobile Manufacturers Association (KAMA)
- China Association of Automobile Manufacturers (CAAM)
- Directorate General of Commercial Intelligence and Statistics (DGCIS), India
Magazines
- Electric & Hybrid Vehicle Technology International
- EV Tech News
- Charged EVs Magazine
- Automotive Engineering International
- Autocar Professional
- EVreporter
- Energy Storage News
- Green Car Reports
- Mobility Outlook Magazine
Journals
- IEEE Transactions on Vehicular Technology
- Journal of Power Sources (Elsevier)
- Journal of Energy Storage
- IEEE Transactions on Transportation Electrification
- Applied Energy (Elsevier)
- Electric Power Systems Research
- Journal of Cleaner Production
Newspapers
- The Economic Times – EV & Auto Section
- Business Standard – Electric Mobility & Energy
- Financial Times – Auto & Green Energy Reports
- Nikkei Asia – Automotive Technology
- The Hindu Business Line – Mobility & Infrastructure
- The Times of India – Auto Industry Section
- South China Morning Post – Automotive Supply Chain
Associations
- Society of Automotive Engineers (SAE International)
- International Energy Agency (IEA) – Global EV Initiative
- Automotive Component Manufacturers Association of India (ACMA)
- Society of Indian Automobile Manufacturers (SIAM)
- European Association for Electromobility (AVERE)
- Alliance for Automotive Innovation (U.S.)
- Electric Vehicle Industry Association (EVIA)
- International Council on Clean Transportation (ICCT)
Public Domain Sources
- Ministry of Road Transport and Highways (MoRTH), India
- NITI Aayog – EV Policy Papers and Battery Roadmaps
- Department for Promotion of Industry and Internal Trade (DPIIT), India
- National Institute for Transforming India – Reports on Energy and Transport
- Reserve Bank of India (RBI) – EV Financing Trends
- Ministry of Economy, Trade and Industry (METI), Japan
- U.S. Department of Energy – Office of Energy Efficiency & Renewable Energy
- European Commission – Mobility and Transport
- India Energy Storage Alliance (IESA) Knowledge Portal
Proprietary Elements
- CMI Data Analytics Tool, and Proprietary CMI Existing Repository of information for last 8 years
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Vehicle Electrification Market is estimated to be valued at USD 136.75 Bn in 2026, and is expected to reach USD 287.52 Bn by 2033.
The CAGR of the Vehicle Electrification Market is projected to be 11.2% from 2026 to 2033.
Climate change concerns and improving technology and falling battery prices are the major factors driving the growth of vehicle electrification market.
Battery technology and cost challenges and inadequate charging infrastructure are the major factors hampering the growth of the vehicle electrification market.
In terms of Product Type, Start/Stop System is estimated to dominate the market revenue share 2026.
AISIN CORPORATION, Aptiv, BorgWarner Inc., Continental AG, DENSO CORPORATION, Hitachi Astemo, Ltd., Johnson Controls, Johnson Electric Holdings Limited, JTEKT Corporation, Magna International Inc., Mitsubishi Electric Corporation, Robert Bosch GmbH, Valeo SA, Wabco Holdings Inc., and ZF Friedrichshafen AG are the major players.
Asia Pacific is expected to lead the vehicle electrification market in 2026.