

Cybersecurity Insurance Market Size and Forecast – 2026 to 2033
The Cybersecurity Insurance Market is estimated to be valued at USD 23.36 Bn in 2026 and is expected to reach USD 87.16 Bn by 2033, exhibiting a compound annual growth rate (CAGR) of 20.7% from 2026 to 2033.
Key Takeaways
- By Insurance Type, Standalone hold the largest market share of 65.7% in 2026 owing to the rising incidence & severity of cyber threats.
- By Coverage Type, Liability Coverage expected to hold largest market share of 67.2% in 2026 owing to its rising frequency & severity of cyberattacks.
- By Enterprise Size, Large Enterprises acquired the prominent market share of 70.7% in 2026 owing to its complex & expansive digital infrastructure.
- By End User, Healthcare dominates the overall market share in 2026 owing to the high value of healthcare data.
- By Region, North America dominates the overall market with an estimated share of 52.6% in 2026 owing to the mature digital infrastructure & high technology adoption.
Market Overview
Organizations are increasingly recognizing the financial and operational risks posed by cyber threats, driving significant growth in the Cybersecurity Insurance Market. Expanding digitalization, widespread cloud adoption, and interconnected IT infrastructures expose businesses to data breaches, ransomware, and other cyberattacks. Regulatory compliance requirements, especially in data-sensitive sectors like healthcare and finance, further encourage adoption, while large enterprises actively pursue risk transfer solutions to safeguard their assets. Insurers now provide tailored policies with bundled incident response services, positioning cyber insurance as a vital part of enterprise risk management.
Current Events and Its Impact on the Cybersecurity Insurance Market
Current Events | Description and its impact |
Geopolitical Tensions and Cyber Warfare Escalation |
|
Technological Advancements in Cyber Threat Detection and Response |
|
Macro-Economic Conditions and Market Dynamics |
|
Segmental Insights

- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Cybersecurity Insurance Market Insights, By Insurance Type - Standalone contribute the highest share of the market owing to its growing awareness & risk perception
Standalone hold the largest market share of 65.7% in 2026. Rising cyberattack frequency and sophistication drive organizations to seek dedicated protection through standalone cyber insurance rather than relying on traditional policies. Expanding digitalization, cloud usage, and remote work broaden their exposure to cyber risks, increasing the need for specialized coverage. Regulatory demands and the high costs associated with data breaches further motivate firms to adopt standalone policies. Insurers also enhance demand by providing tailored coverage with incident response, forensic analysis, and legal support, positioning standalone cyber insurance as a key tool for comprehensive risk management. For instance, in May 2025, BOXX Insurance released Cyberboxx Assist, a new suite of cybersecurity tools and services for all Cyberboxx Business and Cyberboxx Home policyholders. The platform helps users actively identify, reduce, and respond to cyber threats with built-in risk assessments, compliance tools, and 24/7 cybersecurity support.
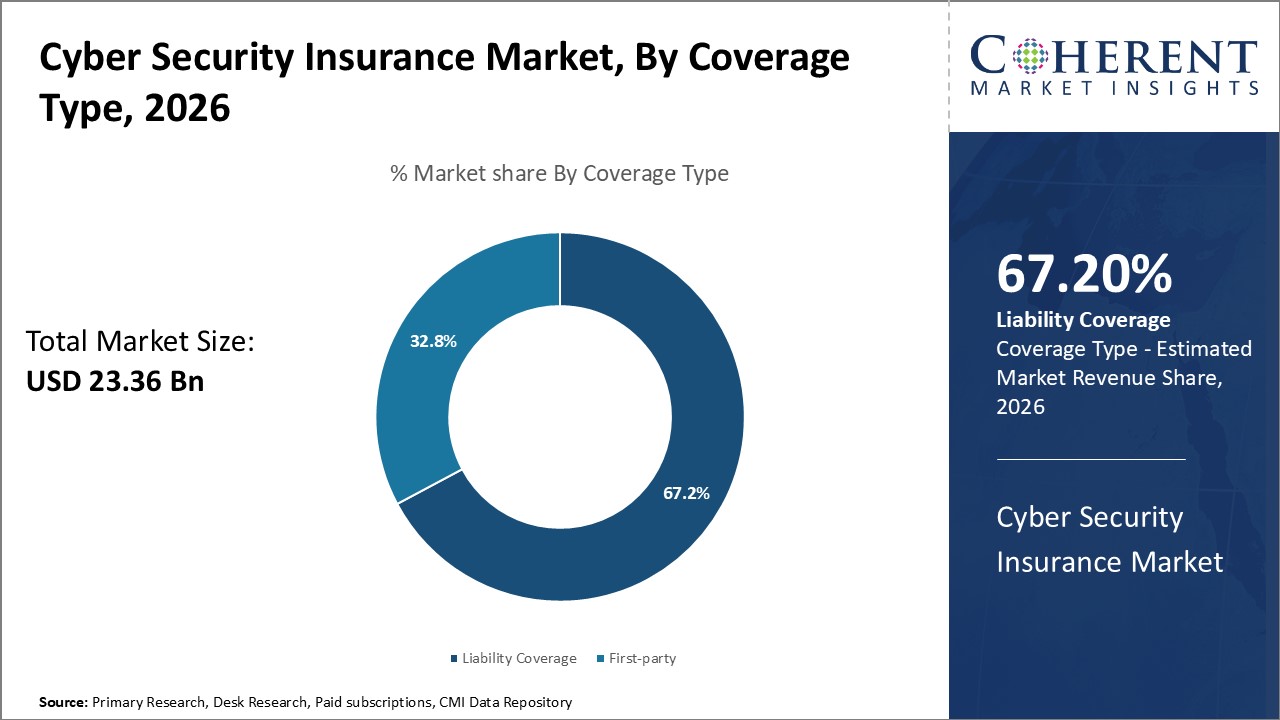
Cybersecurity Insurance Market Insights, By Coverage Type - Liability Coverage contribute the highest share of the market owing to its increasing awareness & board-level risk recognition
Liability Coverage expected to hold largest market share of 67.2% in 2026. Rising data breaches, ransomware incidents, and growing legal and regulatory risks drive demand for liability coverage in the Cybersecurity Insurance Market. Organizations increasingly seek financial protection as their exposure to third-party claims, such as lawsuits, privacy violations, and compliance penalties, intensifies. Expanding digital operations and greater reliance on cloud services heighten vulnerability, making liability protection vital. Insurers further boost adoption by offering policies with legal defense, breach notification, and crisis management services, motivating businesses to reinforce their cyber risk management practices. For instance, in April 2025, Cyber Threat Insure has launched a new cyber liability insurance distribution model for Managed Service Providers (MSPs), naming IT First Responder as its first partner. The model is designed to close a major gap in Australia’s cyber insurance market by letting MSPs offer cyber liability coverage to clients without taking on the usual advisory risks of selling insurance.
Cybersecurity Insurance Market Insights, By Enterprise Size - Large Enterprises contribute the highest share of the market owing to its risk transfer & financial management
Large Enterprises acquired the prominent market share of 70.7% in 2026. Large enterprises fuel the Cybersecurity Insurance Market demand as they manage complex digital infrastructures, large data volumes, and greater exposure to advanced cyberattacks. Operating across multiple regions and industries increases their regulatory and compliance responsibilities, intensifying cyber risk. These organizations actively pursue insurance to mitigate potential financial losses, legal liabilities, and business interruptions. Insurers strengthen this demand by providing high-limit, customized policies with incident response and risk-assessment services, positioning cyber insurance as an essential element of enterprise risk management for major corporations. For instance, in September 2025, Invision Cyber, a new cyber insurance MGA, has partnered with Trend Micro to offer a cyber insurance product for the firm’s U.S. customers. The partnership delivers a tailored policy based on real-time risk insights and data-driven underwriting.
Cybersecurity Insurance Market Insights, By End User - Healthcare contributes the highest share of the market owing to its rising awareness & investment
The healthcare sector drives demand in the Cybersecurity Insurance Market as organizations handle high-value medical data, face increasing ransomware attacks, and confront growing risks from digital health systems. Expanding adoption of electronic health records, telemedicine, and connected medical devices raises their exposure to breaches. Strict regulatory rules and costly compliance duties push healthcare providers to secure insurance. Insurers strengthen demand by offering incident response, forensic support, and legal services, helping organizations protect patient data and maintain operational continuity. For instance, in July 2025, Clearwater has launched its ECRM solution, combining OCR-Quality® Risk Analysis and a NIST CSF 2.0 maturity assessment in one engagement to help healthcare organizations manage cyber risk more effectively.
Regional Insights

North America Cybersecurity Insurance Market Trends
North America dominates the overall market with an estimated share of 52.6% in 2026. Expanding digital ecosystems, rising cyberattacks, and stringent regulatory oversight shape the North America Cybersecurity Insurance Market. Organizations actively integrate cyber insurance into broader risk management strategies as they address threats associated with cloud adoption, remote work, and complex IT infrastructures. Demand continues to grow for advanced, standalone policies that provide incident response and threat-mitigation support. Insurers, cybersecurity providers, and enterprises increasingly collaborate, driving innovation in underwriting practices, real-time threat monitoring, and customized policy solutions across the region. For instance, in July 2026, AXA XL has launched a new suite of proactive cybersecurity assessment services for its North American cyber policyholders, developed with Fenix24 to help organizations strengthen defenses and boost response readiness.
Asia Pacific Cybersecurity Insurance Market Trends
Businesses in the Asia Pacific region are rapidly adopting digital technologies and cloud-based solutions, driving growth in the Cybersecurity Insurance Market as their exposure to cyber threats increases. Rising cybercrime, data breaches, and evolving regulations push organizations to actively transfer risk through insurance. Companies are increasingly opting for tailored policies that cover both first-party and third-party losses, supported by incident response and risk assessment services. Insurers are strengthening coverage, improving pricing accuracy, and enhancing regional cyber resilience through local partnerships and advanced analytics. For instance, in October 2026, Group-IB has opened its first Cyber Fusion Center in the Asia-Pacific region, located in its Singapore Digital Crime Resistance Center. The new hub unifies the company’s key capabilities—DFIR, threat intelligence, attack surface management, managed XDR, and digital and fraud protection—into one intelligence-driven ecosystem to better defend organizations from evolving digital threats.
United States Cybersecurity Insurance Market Trends
Organizations in the United States are driving growth in the Cybersecurity Insurance Market as they face rising cyber threats across complex IT infrastructures and digital operations. Businesses actively adopt standalone and customizable policies to manage risks like ransomware, data breaches, and regulatory penalties. Insurers respond by providing enhanced services, including incident response, legal support, and threat monitoring. Collaboration among insurers, technology providers, and enterprises is promoting innovation in underwriting and risk assessment, positioning cyber insurance as a vital tool for safeguarding assets, ensuring compliance, and maintaining business continuity.
For instance, in November 2026, Cork Cyber has introduced Vantage, a cyber risk intelligence platform that helps MSPs and their clients assess, manage, and validate cyber risk. The platform expands Cork’s offerings beyond warranties to deliver broader insights into cyber resilience and business continuity.
India Cybersecurity Insurance Market Trends
Businesses in India are accelerating growth in the Cybersecurity Insurance Market as they digitize operations and adopt cloud and mobile technologies, increasing their exposure to cyber risks. Rising data breaches, ransomware attacks, and regulatory requirements drive organizations to obtain comprehensive cyber coverage. Companies are actively seeking policies that cover both first-party and third-party losses, complemented by incident response and forensic support. Insurers are strengthening offerings through local partnerships and advanced risk assessment tools, enhancing cyber resilience and enabling proactive risk management nationwide.
In July 2026, Intersys India has launched cyber insurance services to help insurers and brokers give policyholders better cyber risk visibility. The offering targets underserved SMEs with security assessments and continuous monitoring to improve risk profiling and insurance support.
End-user Feedback and Unmet Needs in the Cybersecurity Insurance Market
- Complexity in Policy Understanding: End-users often struggle to fully understand coverage terms, exclusions, and claim processes. Many policies use technical language and broad clauses, making it difficult for organizations to assess actual protection. Users request clearer, simpler policies with transparent terms, ensuring they can make informed decisions on coverage and risk management.
- Limited Customization Options: Businesses report that many policies do not fully align with their specific risk profiles, industries, or digital infrastructures. End-users seek more tailored solutions that address unique threats, such as cloud vulnerabilities or IoT exposure, rather than one-size-fits-all coverage. Greater flexibility in policy design remains a key unmet need.
- Slow Claim Processing: Users highlight delays and complex procedures in cyber insurance claims, especially during ransomware or data breach incidents. Slow response times can exacerbate operational and financial losses. End-users demand faster, more efficient claims handling with clear guidelines and proactive support during cyber incidents.
Cybersecurity Insurance Market Trend
Growing Adoption of Standalone Policies
Organizations are increasingly opting for standalone cyber insurance rather than relying on add-ons to traditional policies. This trend reflects a recognition of evolving cyber threats and the need for comprehensive protection that specifically addresses data breaches, ransomware, and regulatory penalties. Insurers are responding by offering tailored solutions with incident response, forensic support, and legal assistance, making standalone policies a cornerstone of proactive risk management strategies across industries.
Integration of Risk Management Services
The market is shifting toward bundled offerings that combine insurance coverage with risk mitigation services. Insurers are providing threat monitoring, employee training, vulnerability assessments, and incident response as part of policies. This integration helps organizations prevent breaches, reduce response times, and manage costs more effectively, positioning cyber insurance as not only a financial safety net but also a strategic tool for enhancing overall cybersecurity posture.
Cybersecurity Insurance Market Opportunity
Development of Industry-Specific Policies
Different sectors face unique cyber risks, from healthcare’s patient data to financial institutions’ transactional data. Creating industry-specific insurance policies allows insurers to provide targeted coverage, including regulatory compliance support, breach response, and sector-relevant threat mitigation. This specialization not only enhances value for clients but also reduces insurers’ risk exposure, opening opportunities for partnerships with industry associations, cybersecurity firms, and regulatory bodies to deliver comprehensive, tailored solutions.
Market Report Scope
Cybersecurity Insurance Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 23.36 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 20.7% | 2033 Value Projection: | USD 87.16 Bn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | BitSight, Prevalent, RedSeal, SecurityScorecard, Cyber Indemnity Solutions, Allianz, AIG, Aon, Arthur J. Gallagher & Co, Travelers Insurance, AXA XL, Axis, Chubb, Travelers Indemnity Company, American International Group, Inc., Beazley Group, CNA Financial Corporation, AXIS Capital Holdings Limited, BCS Financial Corporation, Zurich Insurance, and The Hanover Insurance, Inc. | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Cybersecurity Insurance Market News
- In July 2025, CAI has launched a cyber insurance assessment to evaluate organizations’ cybersecurity across 15 key categories, helping ensure compliance, fix vulnerabilities, and support insurance applications or updates.
- In September 2025, Prime Radiant has partnered with TransUnion to launch a personal cyber protection platform that combines identity monitoring, home network security, risk assessments, and insurance-backed remediation in one service.
- In May 2025, Sophos has partnered with UK insurance broker Capsule to make it easier for businesses using Sophos solutions through MSPs to access cyber insurance.
- In September 2025, Globe Business has teamed up with Blackpanda, Asia’s top cyber incident response specialist, to provide Philippine businesses with affordable, enterprise-grade, AI-ready cybersecurity solutions.
Analyst Opinion (Expert Opinion)
- Cyber insurers are now navigating a paradox: fewer but more catastrophic claims. In H1 2025, Resilience reported a 53% drop in claim volume, even as average ransomware payouts surged by 17% to $1.18 million. This suggests that cybercriminals are getting more efficient and ruthless—leveraging AI-powered phishing, double‑extortion, and even stolen policy details to extract max value.
- In parallel, NetDiligence’s 2025 Cyber Claims Study shows only 2% of total claims come from large enterprises—but those account for more than half of all losses, with average incidents costing over $10 million and downtime reaching $26 million-plus. This concentration of loss remains underappreciated: despite lower claim frequency, tail risk continues to threaten insurers’ profitability.
- Yet competition is intensifying. According to Munich Re, cyber premiums are softening, and underwriting discipline is under stress. With reinsurers pressuring, underwriters will need to sharpen risk selection and data-driven pricing. The lack of standardized data sharing remains a critical barrier: without robust claim transparency across insurers, models will struggle to anticipate systemic vulnerabilities.
- On the client side, businesses are increasingly using cyber insurance not just as financial protection but as a strategic risk‑management tool—demanding policies that include incident response, forensics, and legal remediation. As such, insurers who embed prevention into their coverage (threat monitoring, breach readiness) are likely to outperform peers. Given the escalation of ransomware sophistication, cyber insurance is now a front-line part of an enterprise’s defensive architecture, not just a post-incident fallback.
- The cyber insurance market is maturing fast. Insurers that cut through the noise—tighten underwriting, leverage data, and embed proactive security services—will dominate. Others risk being overwhelmed by increasingly severe claims, AI-empowered attackers, and a divided market where tail risk is too concentrated to ignore.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- Insurance Type Insights (Revenue, USD Bn, 2021 - 2033)
- Standalone
- Tailored
- Coverage Type Insights (Revenue, USD Bn, 2021 - 2033)
- First-party
- Liability Coverage
- Enterprise Size Insights (Revenue, USD Bn, 2021 - 2033)
- SMEs
- Large Enterprise
- End user Insights (Revenue, USD Bn, 2021 - 2033)
- Healthcare
- Retail
- BFSI
- IT & Telecom
- Manufacturing
- Others (Government, Travel & Tourism)
- Regional Insights (Revenue, USD Bn, 2021 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East & Africa
- Key Players Insights
- BitSight
- Prevalent
- RedSeal
- SecurityScorecard
- Cyber Indemnity Solutions
- Allianz
- AIG
- Aon
- Arthur J. Gallagher & Co
- Travelers Insurance
- AXA XL
- Axis
- Chubb
- Travelers Indemnity Company
- American International Group, Inc.
- Beazley Group
- CNA Financial Corporation
- AXIS Capital Holdings Limited
- BCS Financial Corporation
- Zurich Insurance
- The Hanover Insurance, Inc.
Sources
Primary Research interviews
- Cyber risk officers at large enterprises (e.g., Global 2000 firms)
- Claims / underwriting leads at active cyber insurers
- Incident response and forensic service providers
Databases
- Public filings from U.S. state Data Breach Notification portals
- FS‑ISAC (Financial Services Information Sharing and Analysis Center) threat‑sharing data
- Open-source academic databases (e.g., arXiv) — e.g., modeling of data breach risk and notification times
Magazines
- Insurance Business America — “Ransomware attacks fewer but costlier”
- Risk & Insurance — “Cyber Insurance Claims Drop … as Ransomware Attacks Grow More Expensive”
Newspapers
- Reuters — “New York sues Allstate over data breach …”
- Associated Press (AP) — “Allianz Life confirms data breach affecting 1.4M U.S. customers”
- Financial Times — “Allianz's US life arm hit by cyber attack”
Associations
- FS‑ISAC (Financial Services Information Sharing and Analysis Center)
- (You could also mention other ISACs or cyber‑risk sharing bodies, depending on your research)
Public Domain sources
- Allianz Commercial’s “Cyber Risk Trends” public insight page
- BeInsure’s report on systemic cyber events and cyber‑risk trends
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of information for last 8 years
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Cyber Security Insurance Market is estimated to be valued at USD 23.36 Bn in 2026, and is expected to reach USD 87.16 Bn by 2033.
The CAGR of the Cyber Security Insurance Market is projected to be 20.7% from 2026 to 2033.
Increasing rates of cyberattacks and rise of regulations and compliance burdens are the major factors driving the growth of the cybersecurity insurance market.
Challenges in cyber risk assessment and insurance underwriting and inadequate awareness about benefits of cyber insurance are the major factor hampering the growth of cybersecurity insurance market.
In terms of Insurance Type, Standalone in estimated to dominate the market revenue share in 2026.
BitSight, Prevalent, RedSeal, SecurityScorecard, Cyber Indemnity Solutions, Allianz, AIG, Aon, Arthur J. Gallagher & Co, Travelers Insurance, AXA XL, Axis, Chubb, Travelers Indemnity Company, American International Group, Inc., Beazley Group, CNA Financial Corporation, AXIS Capital Holdings Limited, BCS Financial Corporation, Zurich Insurance, and The Hanover Insurance, Inc. are the major players.
North America is expected to lead the cybersecurity insurance market in 2026.