

In Vitro Diagnostics Ivd Market Size and Forecast – 2026 to 2033
In-vitro diagnostics market is estimated to be valued at USD 135.22 Bn in 2026 and is expected to reach USD 212.91 Bn by 2033, exhibiting a compound annual growth rate (CAGR) of 6.7% from 2026 to 2033.
Key Takeaways
- Based on Product, Reagents & Kits segment is projected to account for 69.3 % of the global market in 2026, owing to advancements in medical care.
- Based on Test Type, Immunoassay segment is expected to capture 35.6% share of the market in 2026, due to its versatility.
- Based on Application, the Infectious Diseases segment is projected to command 49.7% share of the market in 2026, due to its ability to quickly and accurately diagnose infectious diseases.
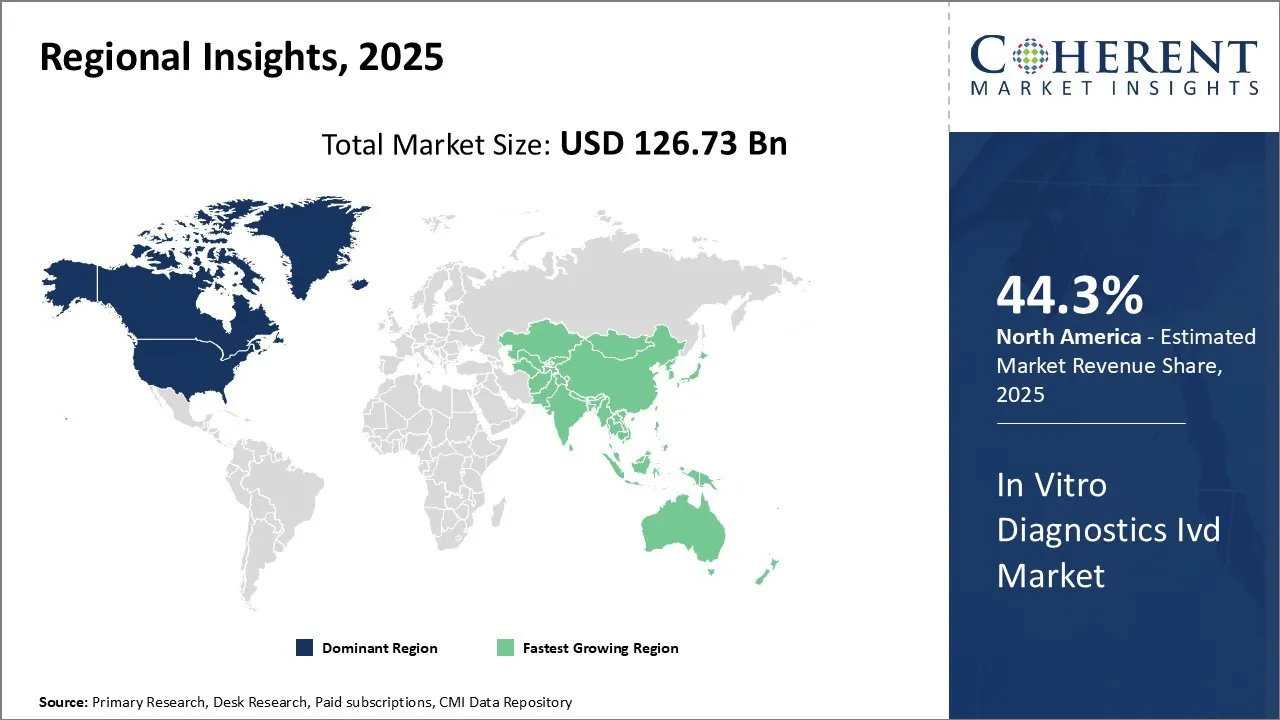
- Based on Region, North America is set to dominate the global market with a 44.3 % share in 2026.
Market Overview
The market is expected to witness positive growth over the forecast period owing to rising geriatric population globally and increasing adoption of point-of-care testing. Demand for in-vitro diagnostic tests is increasing due to rising prevalence of chronic and infectious diseases. Additional factors such as technological advancements in IVF technologies, growing awareness regarding early disease diagnosis, growing demand for personalized medicine will further drive the in vitro diagnostics market growth during this period.
Current Events and Its Impact
Current Event | Description and its Impact |
AI and Digital Health Revolution in Diagnostics |
|
Aging Global Population and Chronic Disease Burden |
|
Pricing Analysis
- PCR Systems and Reagents
- High-End Systems
- Roche cobas 8800: $450,000-$550,000
- Abbott m2000: $380,000-$420,000
- Hologic Panther: $400,000-$500,000
- Mid-Range Systems
- Bio-Rad CFX96: $35,000-$45,000
- Applied Biosystems 7500: $55,000-$75,000
- Qiagen Rotor-Gene Q: $25,000-$35,000
- Reagent Pricing (per test)
- COVID-19 PCR tests: $15-$45
- HPV testing: $25-$60
- Hepatitis panels: $30-$80
- STD panels: $40-$120
- High-End Systems
- Next-Generation Sequencing (NGS)
- Systems
- Illumina NovaSeq 6000: $985,000-$1,200,000
- Thermo Fisher Ion Torrent S5: $150,000-$200,000
- Oxford Nanopore MinION: $1,000-$5,000
- Per-Test Costs
- Whole genome sequencing: $600-$1,500
- Exome sequencing: $300-$800
- Targeted gene panels: $150-$500
- Systems
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Market Drivers
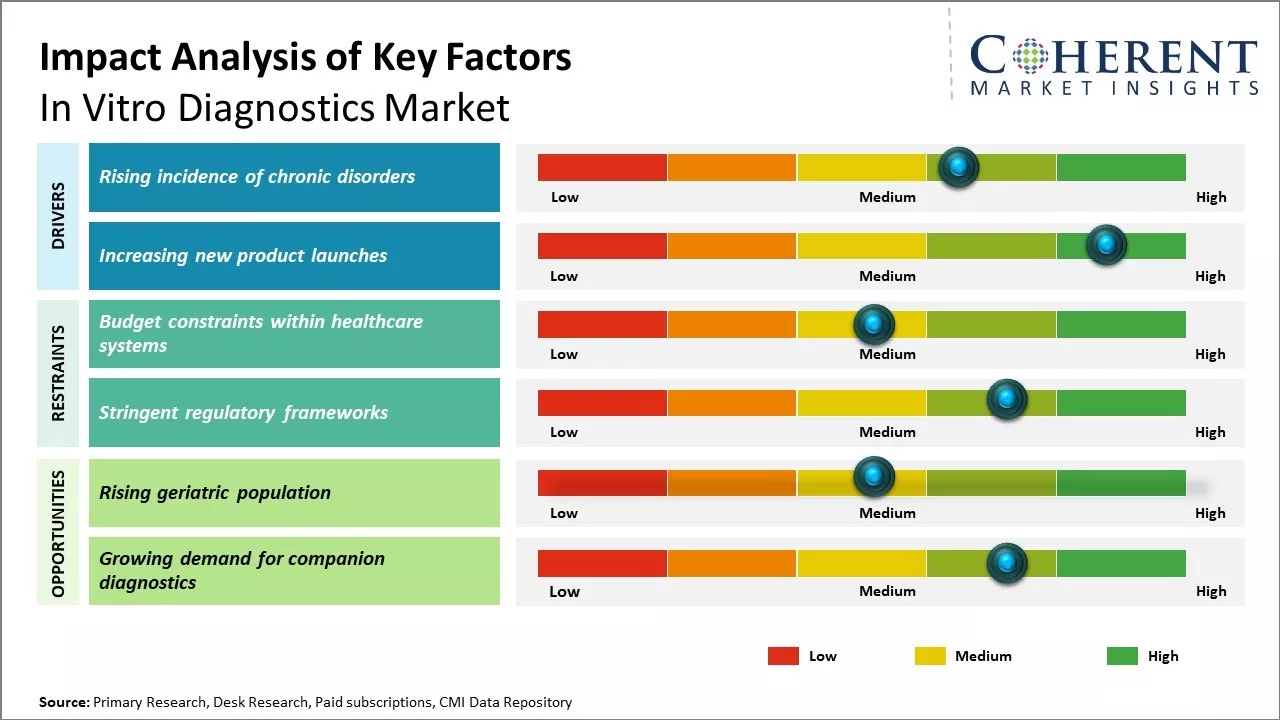
Rising incidence of chronic disorders
The changing lifestyle and dietary patterns prevalent worldwide have led to increase in chronic medical ailments. Conditions like cardiovascular disease, diabetes, cancer are no longer perceived as diseases of affluence but have affected people across socioeconomic classes. Long-term exposure to environmental contaminants and rising levels of stress have further contributed to non-communicable diseases gaining epidemic proportions in many developed and developing regions.
Unlike acute illnesses, these long-lasting health issues require constant clinical monitoring and therapy adjustments based on test results. Advanced diagnostic assays aid in prognostication and disease management by identifying biological markers, characterizing the extent or stage of the disease, detecting treatment effectiveness or resistance. These empower physicians to personalize treatment approaches.
Increasing new product launches
Increasing new product launches by key market players is expected to drive the global in-vitro diagnostics market growth. For instance, in June 2022, Streck, a manufacturer of laboratory products, announced the commercialization of the Streck Viral Extraction Kit with partner Ceres Nanosciences, a life sciences company. Streck has developed a virus extraction kit using Nanotrap technology to reduce manual effort and simplify the workflow for isolating SARS-CoV-2 and Influenza A from clinical samples.
Segmental Insights

In Vitro-Diagnostics Market Insights, By Product - Increased dependence on diagnostic testing drives the reagents & kits segment growth
Product segment is sub-segmented into reagents & kits and instruments. Reagents & kits segment is anticipated to hold 69.3% of the market share in 2026. Advancements in medical care have led physicians to rely heavily on laboratory testing to better understand diseases and determine appropriate treatment plans. As diagnostic capabilities expand, more reagents and kits are needed to perform the wide range of tests available.
Being consumable products that must be replenished regularly, reagents and kits witness high and recurring demand from hospitals, clinics, and other testing facilities. Their ability to work with various automated and non-automated analyzers also makes them a more universal option for laboratories compared to proprietary instruments. Manufacturers continue adding new reagents and assays to test menus to keep up with the evolving diagnostic needs.
The demand for reagents and kits is also boosted by the trend of decentralization where diagnostic testing is being brought closer to patients through small laboratories, POC testing, and home use. This decentralized model improves access and boosts adoption of simple, cartridge-based reagents and kits that can be used outside traditional diagnostic settings, further accelerating the in vitro diagnostics market demand.
For instance, in September 2023, NeoDx Biotech Labs, a Bengaluru-based startup launched Real-time PCR-Technology-based in vitro diagnostic (IVD) kit for Ankylosing Spondylitis & empowers healthcare services to improve their testing capabilities.

In Vitro-Diagnostics Market Insights, By Test Type - Rising prevalence of infectious diseases drives the immunoassay segment growth
Test type segment is sub-segmented into clinical chemistry, immunoassay, hematology, molecular diagnostics, microbiology, coagulation & hemostasis, urinalysis, and others. Immunoassay segment contributes the highest share of the in-vitro diagnostics market and is projected to hold 35.6% of the market share in 2026.
Immunoassays utilize the principle of antigen-antibody binding, and are highly sensitive and specific for detecting targets like proteins, antibodies, hormones, and others in patient samples. Their versatility has made immunoassays the primary technology used to diagnose HIV, hepatitis, influenza and other communicable illnesses. Rising prevalence of infectious diseases, especially in developing regions, is a key factor propelling the market growth.
Factors like lack of adequate sanitation, vector proliferation, and limited vaccination drive up infections rates. Diagnosing these diseases early and tracking epidemics have become public health priorities, contributing significantly to immunoassays demand. Other promoting factors are new assays for emerging diseases and the ability of immunoassays to provide rapid results. Automated analyzers have also boosted efficiency and throughput. Continuous technology refinements will help immunoassays maintain their leading role in infectious disease diagnostics.
For instance, in June 2025, H.U. Group Holdings Inc. and its wholly-owned subsidiary Fujirebio announced the availability of the Lumipulse G sTREM2 assay for the fully automated LUMIPULSE® G immunoassay analyzers.
In Vitro-Diagnostics Market Insights, By Application - Growing prevalence of infectious diseases
Application segment is sub-segmented into infectious diseases, diabetes, oncology, cardiology, nephrology, autoimmune disorders, and others. Infectious diseases segment contributes the highest share of the in-vitro diagnostics market and is projected to hold 49.7% of the market share in 2026.
The ability to quickly and accurately diagnose infectious diseases through various IVD tests is becoming increasingly important in clinical care and public health monitoring. As newer pathogens emerge and existing ones adapt and spread into new regions, the demand for advanced diagnostic capabilities is growing steadily.
Regional Insights
North America In-Vitro Diagnostics Market Analysis & Trends
North America has established itself as the dominant region in the global in-vitro diagnostics market and is expected to hold 44.3% of the market share in 2026. The large presence of leading IVD companies such as Thermo Fisher Scientific, Abbott Laboratories, and Becton Dickinson has enabled the region to evolve considerably over the years in terms of innovation and product offerings.
With some of the most stringent regulatory guidelines enforced by authorities such as the U.S. FDA, North American companies have set the benchmark for producing high-quality diagnostics products. Most new diagnostic technologies and platforms are commercialized first in this region, allowing companies to gain large market share before expanding globally. In addition, favorable reimbursement policies for diagnostic tests make the region highly lucrative.
According to the Centers for Disease Control and Prevention (CDC), approximately 129 million individuals in the U.S. live with at least one major chronic condition, including heart disease, cancer, diabetes, obesity, or hypertension.
Asia Pacific In-Vitro Diagnostics Market Analysis & Trends
The Asia Pacific region, on the other hand, is emerging as the fastest growing market. Several factors are contributing to this rapid growth like improving healthcare infrastructure, rising medical tourism, and growing investments by foreign players looking to tap the opportunities in developing economies.
Country-level analyses indicate China and India will spearhead growth due to their huge patient populations and increasing healthcare expenditures. Both nations are working to reduce their dependence on imports and promote local manufacturing of IVD devices and reagents.
Several global companies have established manufacturing facilities as well as research centers in these countries. Meanwhile, other Asian economies like South Korea, Japan, Singapore, Malaysia and Thailand offer attractive business environments and act as manufacturing and export hubs to cater to the demand across Asia and other regions.
For instance, in February 2023, Redcliffe Labs introduced a molecular diagnostic test in India to detect multidrug-resistant TB (MDR-TB). This test offers faster and more accurate detection, addressing the rising need for advanced TB diagnostics and improving disease control efforts in the region.
In-Vitro Diagnostics Market Outlook Country-Wise
The U.S. In-Vitro Diagnostics Market Trends
The U.S. leads the in vitro diagnostics industry, driven by major industry players such as Roche Diagnostics, Abbott, and Danaher. Their dominance is reinforced by strong R&D investments and favorable reimbursement policies that support innovation and the adoption of advanced diagnostic technologies.
According to the American Cancer Society, over 2 million new cancer cases are projected to be diagnosed in the U.S. in 2024, excluding basal and squamous cell skin cancers and noninvasive carcinoma in situ, except for urinary bladder cases. This rising disease burden is expected to sustain the country's leadership in the market.
The U.K. In-Vitro Diagnostics Market Trends
The U.K in vitro diagnostics market is experiencing significant growth, driven by a robust healthcare infrastructure, high disposable income, and increasing awareness of early disease detection. The rising demand for molecular diagnostics is further supported by government initiatives aimed at improving accessibility to diagnostic services and reducing NHS waiting times.
For instance, in July 2023, Virax Biolabs Group Limited, a company specializing in immune response detection and viral disease diagnostics, announced plans to launch two new research and laboratory facilities in the UK.
Market Concentration and Competitive Landscape
Analyst Opinion (Expert Opinion)
- The global in-vitro diagnostics market is experienced growth owing to rising incidence of chronic disease and growing demand of point-of-care testing and home diagnostics. The market sees significant opportunities in disease screening and detection as well as personalized medicine. However, stringent regulatory guidelines and lengthy approval times pose a challenge to innovation.
- North America is viewed as the dominant region in terms of market share. It has advanced healthcare infrastructure, high spending on diagnostics, strong R&D, favorable reimbursement, and many major IVD players headquartered there
- Asia‑Pacific is projected to be the fastest‑growing region. Analysts see strong potential in China, India, Japan etc., driven by increasing healthcare investment, improving infrastructure, greater awareness about diagnostics, government initiatives for better access, and rising disease burden.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
In Vitro Diagnostics Ivd Industry News
- In May 2025, Launch Diagnostics Limited, a leading distributor of in vitro diagnostics (IVD) in the United Kingdom, Ireland, France, and Germany has been acquired by the Palex Group.
- In April 2024, WHO expanded the prequalification (PQ) scope of in vitro diagnostics (IVDs). Applications for PQ can include in vitro diagnostic medical devices for monitoring of blood glucose in capillary blood and HbA1c point-of-care assays.
- In November 2023, Newland EMEA launched a new IVD (in vitro diagnostics) product line for the healthcare industry and will be showcasing the new devices at the biggest tradeshow for the medical industry
Market Report Scope
In Vitro Diagnostics Ivd Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 135.22 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 6.7% | 2033 Value Projection: | USD 212.91 Bn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | Siemens Healthineers, Sysmex Corporation, Bio-Rad Laboratories, bioMérieux S.A., Becton Dickinson and Company, Danaher Corporation, Abbott Laboratories, F. Hoffmann-la Roche Ltd, QIAGEN N.V., Arkray Inc., Nittobo Medical Co. Ltd., Medical & Biological Laboratories Co. Ltd., Miraca Holdings Inc., Mizuho Medy Co. Ltd., Thermo Fischer Scientific Inc, Diasorin, Agilent Technologies, Inc, Grifols SA | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Market Opportunities: Rising geriatric population
Growing geriatric population and increasing prevalence of chronic and infectious diseases boosts demand for diagnostic testing. Telehealth and home healthcare are opening new channels for diagnostic services. Further, point-of-care testing is gathering momentum due to its convenience and quick results. Partnerships along the healthcare continuum can help in vetting new technologies and expanding access.
Market Segmentation
- Product Insights (Revenue, USD Bn, 2021 - 2033)
- Reagents & Kits
- Instruments
- Test Type Insights (Revenue, USD Bn, 2021 - 2033)
- Clinical Chemistry
- Immunoassay
- Hematology
- Molecular Diagnostics
- Microbiology
- Coagulation & Hemostasis
- Urinalysis
- Others
- Application Insights (Revenue, USD Bn, 2021 - 2033)
- Infectious Diseases
- Diabetes
- Oncology
- Cardiology
- Nephrology
- Autoimmune Disorders
- Others
- End User Insights (Revenue, USD Bn, 2021 - 2033)
- Hospitals & Clinics
- Diagnostic Laboratories
- Academic & Research Institutes
- Others
- Regional Insights (Revenue, USD Bn, 2021 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
- North America
- Key Players Insights
- Siemens Healthineers
- Sysmex Corporation
- Bio-Rad Laboratories
- bioMérieux S.A.
- Becton Dickinson and Company
- Danaher Corporation
- Abbott Laboratories
- F. Hoffmann-la Roche Ltd
- QIAGEN N.V.
- Arkray Inc.
- Nittobo Medical Co. Ltd.
- Medical & Biological Laboratories Co. Ltd.
- Miraca Holdings Inc.
- Mizuho Medy Co. Ltd.
- Thermo Fischer Scientific Inc
- Diasorin
- Agilent Technologies, Inc
- Grifols SA
Sources
Primary Research Interviews
- Chief Executive Officers and Senior Management of IVD manufacturing companies
- Laboratory Directors and Clinical Pathologists from diagnostic laboratories
- Regulatory Affairs Specialists from medical device companies
- Healthcare IT Directors and Digital Health Technology Managers
- Others
Databases
- World Health Organization (WHO) Global Health Observatory
- U.S. Food and Drug Administration (FDA) Medical Device Database
- European Medicines Agency (EMA) Medical Device Database
- Centers for Disease Control and Prevention (CDC) Laboratory Systems
- Others
Magazines
- Laboratory Equipment Magazine
- Clinical Laboratory News
- Medical Laboratory Observer
- IVD Technology Magazine
- Others
Journals
- Clinical Chemistry and Laboratory Medicine
- Journal of Clinical Laboratory Analysis
- Analytical and Bioanalytical Chemistry
- Others
Newspapers
- Financial Times - Healthcare Section
- The Wall Street Journal - Health Technology
- Reuters Health News
- Bloomberg Healthcare
- Others
Associations
- Association for Diagnostics & Laboratory Medicine (ADLM)
- European Diagnostic Manufacturers Association (EDMA)
- Advanced Medical Technology Association (AdvaMed)
- International Federation of Clinical Chemistry and Laboratory Medicine (IFCC)
- Others
Public Domain Sources
- U.S. Securities and Exchange Commission (SEC) Filings
- National Institutes of Health (NIH) Research Database
- European Centre for Disease Prevention and Control (ECDC)
- World Bank Health Data
- Others
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of information for last 8 years
*Definition: In-Vitro Diagnostics Market involves products, instruments and reagents used to test specimens taken from the human body, such as blood, urine and tissue. These diagnostic tests are performed outside of a living body in controlled laboratory settings using instruments and reagents to examine various biomarkers that can help identify diseases and other medical conditions. Some common types of tests included in this market are immunoassays, clinical chemistry, molecular diagnostics, microbiology and hematology.
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The In Vitro Diagnostics Ivd Market is estimated to be valued at USD 135.22 Bn in 2026, and is expected to reach USD 212.91 Bn by 2033.
The CAGR of the In Vitro Diagnostics Ivd Market is projected to be 6.7% from 2026 to 2033.
Rising incidence of chronic disorders and increasing new product launches are the major factor driving the growth of global in-vitro diagnostics market.
Budget constraints within healthcare systems and stringent regulatory frameworks are the major factor hampering the growth of global in-vitro diagnostics market.
In terms of product, reagents & kits segment is estimated to dominate the market in 2026.
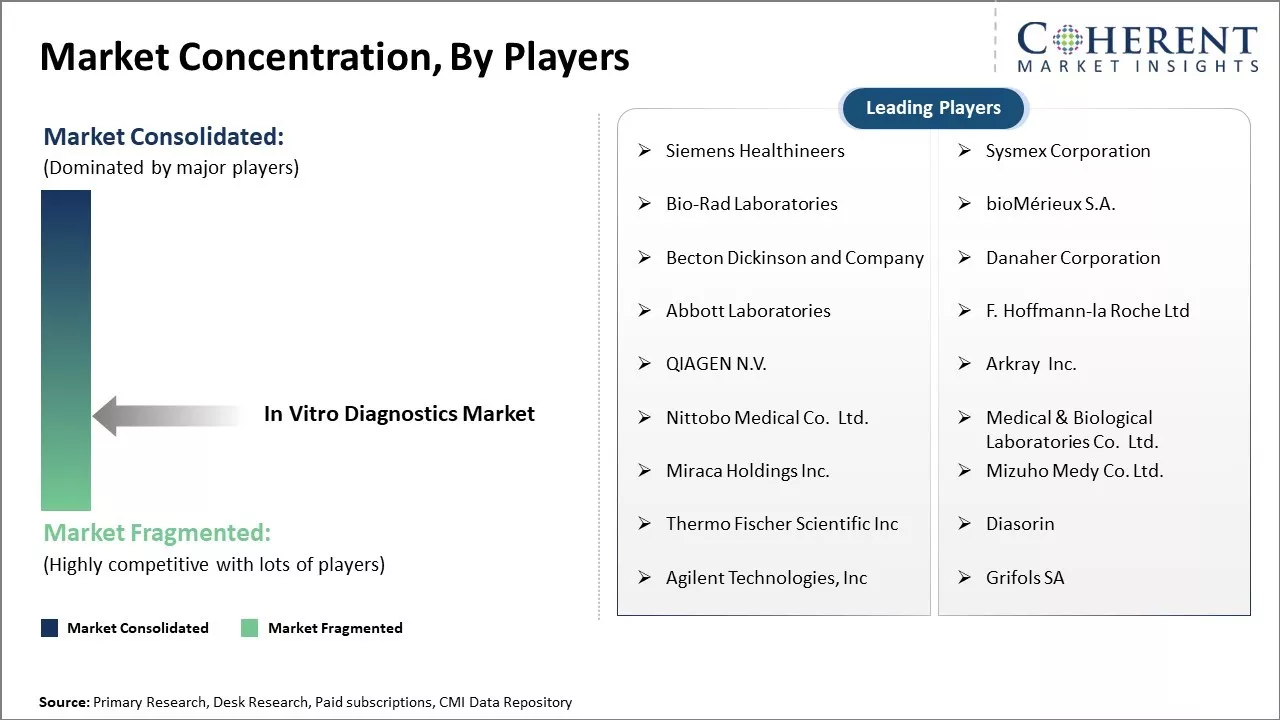
Siemens Healthineers, Sysmex Corporation, Bio-Rad Laboratories, bioMérieux S.A., Becton Dickinson and Company, Danaher Corporation, Abbott Laboratories, F. Hoffmann-la Roche Ltd, QIAGEN N.V., Arkray Inc., Nittobo Medical Co. Ltd., Medical & Biological Laboratories Co. Ltd., Miraca Holdings Inc., Mizuho Medy Co. Ltd., Thermo Fischer Scientific Inc, Diasorin, Agilent Technologies, Inc, Grifols SA are the major players.
North America is expected to lead the global in-vitro diagnostics market.