

Lyophilized Drugs Market Analysis & Forecast: 2026-2033
The Global Lyophilized Drugs Market is estimated to be valued at USD 405.60 Bn in 2026 and is expected to reach USD 755.86 Bn by 2033, exhibiting a compound annual growth rate (CAGR) of 9.3% from 2026 to 2033.
Key Takeaways
- By Drug Class, the Anti-Infective Segment is expected to dominate the global lyophilized drugs market by 2026, with a projected market share of 26.5%.
- By Indication, the Oncology Segment is anticipated to hold the highest share of the global market by 2026, accounting for 26.62% of total revenue.
- By Packaging Type, the Vial Segment will continue to lead the lyophilized drugs market by 2026, with a projected contribution of 41.5%.
- By Region, North America has established itself as the dominant region in the global lyophilized drugs market and is expected to account for 42.7% of the total market share in 2026.
Market Overview
The market for lyophilized drugs is expected to witness a positive growth trend over the forecast period. Factors such as rising prevalence of chronic diseases, growing geriatric population, and increasing demand for long-term stable drugs are expected to drive the demand for lyophilized drugs during this period. This technique is widely used for the manufacturing of parenteral pharmaceuticals and biopharmaceuticals as it removes moisture completely from the product which helps in long term stability.
For instance, in 2023, Pfizer expanded its lyophilization capabilities at its Puurs, Belgium facility to support the production of stable, injectable biologics, including vaccines and cancer therapies. This investment underscores the growing demand for long-term stable drug formulations, particularly for biologics that are sensitive to moisture and require extended shelf life.
Current Events and Its Impact on the Global Lyophilized Drugs Market
Event | Description and Impact |
China–US Trade Relations and Pharmaceutical Supply Chain Tensions |
|
Breakthrough mRNA and Biologics Technological Advances |
|
European Energy Crisis and Manufacturing Cost Pressures |
|
Pipeline Analysis
The lyophilized drugs pipeline is expanding rapidly, with a strong focus on oncology, autoimmune disorders, and rare diseases. In Phase III trials, key developments include lyophilized biosimilars for oncology such as Rituximab, and emerging cost-effective lyophilized drugs aimed at improving access in remote areas. Phase II candidates include freeze-dried adalimumab and anti-TNF alpha therapies for autoimmune diseases, alongside enzyme replacement therapies targeting rare conditions like Gaucher disease.
Early-phase innovations are emerging in gene therapy and neurology, including lyophilized AAV vectors and Alzheimer’s monoclonal antibodies. Preclinical activity is notable in ophthalmology, with anti-VEGF lyophilized antibodies advancing for age-related macular degeneration.
A growing segment of the pipeline supports rehydration techniques with lyophilized drugs, improving usability and compliance in underserved regions. The lyophilized drugs market for hormonal treatments is also gaining traction, as biosimilars and biologics scale. Filling systems innovation is supporting more efficient and sterile packaging, enhancing product stability.
Overall, the market is driven by cost-efficiency, accessibility in remote healthcare settings, and innovation across biologics, with 70% of pipeline candidates being biologic-based therapies.
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Patent Landscape
The market for lyophilized drugs continues to transform with new advancements in formulation stability, reconstitution methods, and lyophilization techniques. The patents that are still relevant to this market are primarily concerned with biologics, in particular, monoclonal antibodies, gene therapies, and vaccines, which are known for having a longer shelf-life and better solubility.
Biopharma companies are now focusing on novel filling systems, dual chamber vials, and automated lyophilization to improve productivity and decrease the risk of contamination and other manufacturing hazards.
There is a marked increase in focusing on low-cost lyophilized drugs which is essiential for developing and remote regions with cold-chain logistic challenges. Patents are also being filed for rehydration speed and formulation stability for ophthalmology and hormonal treatments, which are considered specialized.
Market Leaders such as Merck, Roche, and Takeda are global patent filing leaders and are strengthening their patent portfolios while focusing on continuous lyophilization and other niche technologies like lyophilized biosimilars. The market also displays an increase in collaborative patents where ownership is shared between the pharmaceutical innovator and CMOs. There is now increased competition and market prospects which would improve innovation and set up difficulty for generics on the market.
Reimbursement Scenario
The reimbursement landscape concerning lyophilized drugs globally is impacted by varying regulations, reimbursement coding, and payer systems. The complexity of storage and high production costs strongly impacts reimbursement strategies, which due to high production costs and storage complexity, strongly impacts reimbursement strategies, which account for almost $4.2 billion as of 2023. In the US, lyophilized drugs are reimbursed under Medicare Part B and covered under HCPCS Level II (J-codes) with reimbursement using the ASP + 6% model.
Coinsurance is set at 20% with commercial insurance covering 75 – 85% of costs based on formulary placement. Specialty-tier copays sit between $400 and $600 a month. Straddling both Europe and the UK, centralized and decentralized reimbursement are guided by EMA authorization through national HTA bodies like NICE and G-BA. HAS evaluates France.
Cost-effectiveness and early benefit assessments determine pricing. Australia adheres to the PBS system, while Japan employs the NHI price listing and China ranks drugs under NRDL. Globally, the adoption of ICD-11 and ATC codes enables streamlined reimbursement pathways for anti-infectives, oncology, and vaccines. To boost demand for lyophilized formulations, providing streamlined reimbursement and coverage will be crucial.
Prescribers’ Preference
With regard to specific therapeutic areas such as oncology, immunology, and critical care, prescribers have shown a notable and increasing preference to use lyophilized forms of drugs because of their superior stability, longer shelf-life, and consistent potency. In oncology, rituximab, trastuzumab, and bevacizumab lyophilized forms are preferred as first line treatments for aggressive cancers owing to accurate dosing and durable effectiveness.
In treatment resistant cases, pembrolizumab, cetuximab, and nivolumab are used in second- and third-line treatment as they preserve their immunotherapeutic activity in freeze-dried form.
In autoimmune and rheumatologic disorders, lyophilized infliximab, adalimumab, and tocilizumab are used for early and progressive disease adjustment because of ease of reconstitution and assured therapeutic effect. In critical care and emergency medicine, lyophilized drugs are valued for their rapid rehydration and reliability in stressful situations, longer shelf-life in remote and resource-limited areas, and preserved potency and strength over time.
Overall, lyophilized forms of medication fulfill prescribers concerns about effectiveness in treatment and ease of use in prescribing while meeting safety concerns especially in environments where there is no cold-chain storage, precision dosing is needed, and treatment shelf-life resilience is critical. Their increasing adoption is anticipated given the ease of rehydration and delivery systems.
Market Concentration and Competitive Landscape
Increasing adoption of lyophilization in pharmaceuticals companies
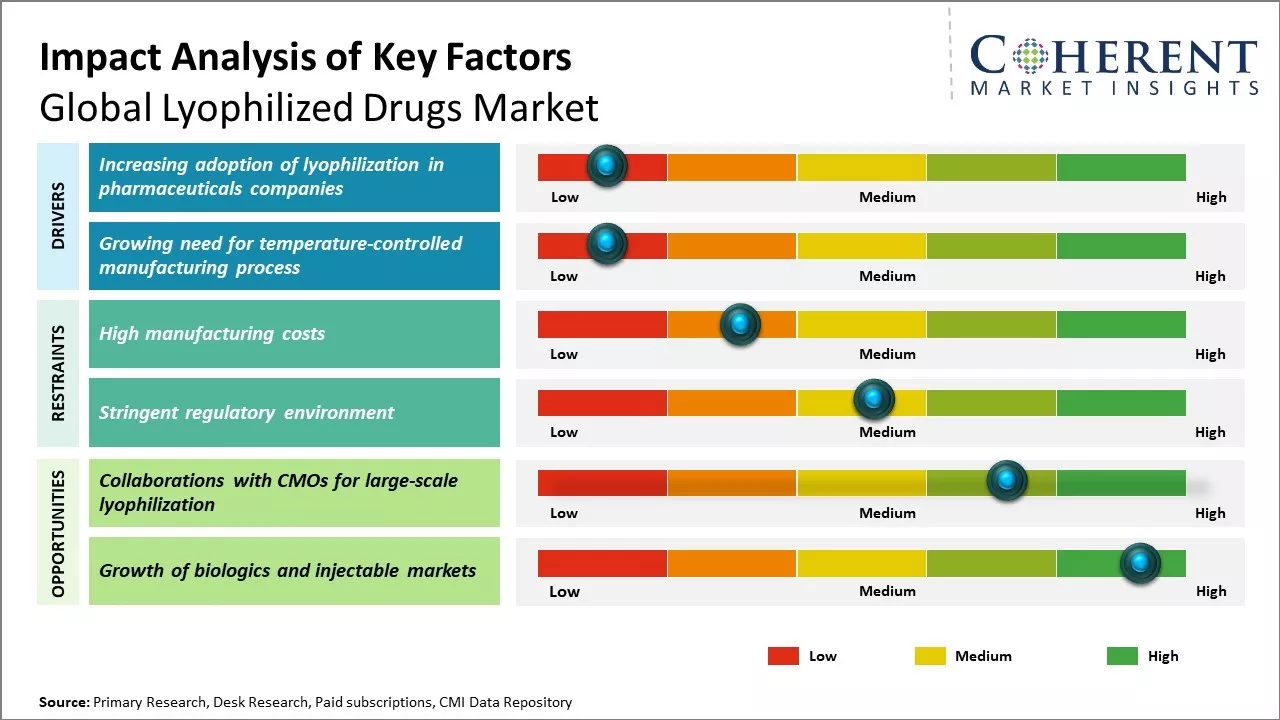
The adoption of lyophilization as a technique for drug formulation is growing rapidly among pharmaceutical companies globally. Lyophilization, also known as freeze-drying, allows for longer shelf life and more stable storage of drugs without refrigeration. This has immense benefit for drugs that need to be transported or stored in difficult geographic and climatic conditions where maintaining cold chains is a challenge. The process removes water from the frozen form of the drug product, resulting in a highly porous cake that can be reconstituted on addition of water.
More pharmaceutical firms are opting for lyophilization as it helps extend the life of drugs from 2-3 years to 5 or more years. This reduces loss due to drugs expiring before use. It also ensures drugs maintain their potency even when stored at room temperature for longer durations. For example, lyophilization is extensively used for formulation of life-saving vaccines that need to be administered in remote regions with limited cold storage facilities.
According to UNICEF supply data, lyophilized vaccines like those for hepatitis, rabies, and yellow fever comprised over 60% of global public health vaccine stockpile in 2021. This shows the preference for longer shelf life vaccines that lyophilization offers. The anticipated growth in biologics and monoclonal antibody drugs in the coming years will further drive the lyophilization usage.
As biologics require sensitive cold chain management for stability, lyophilization alleviates such needs and eases global distribution of these drugs. It is projected that over 500 new biologic drugs will be commercialized between 2020 and 2025.
Market Challenges: High manufacturing costs associated with lyophilization equipment and process
The high manufacturing costs associated with lyophilization equipment and process pose a significant challenge for the growth of the global lyophilized drugs market. Lyophilization or freeze drying is a complex and expensive process that requires sophisticated machinery and a controlled manufacturing environment. The equipment used for lyophilization such as freeze dryers, drying chambers, temperature, and vacuum controllers are extremely capital intensive with freeze dryers itself costing anywhere between US$0.5 million and US$3 million depending on their size and capacity.
Additionally, the process of freeze drying is an energy intensive and slow process requiring several days to weeks to complete. It involves freezing the material, reducing pressure to allow the frozen water in the material to sublimate, and maintaining low temperatures and pressures for optimal results. This makes lyophilization a costly manufacturing route for pharmaceutical products compared to alternative techniques like baking or solvent evaporation.
The high initial capital investment required for lyophilization plant and equipment as well as ongoing operational expenses associated with freeze drying processes poses financial challenges, especially for smaller pharmaceutical manufacturers and generics companies in developing regions. This acts as a barrier for widespread adoption of lyophilization technology.
For instance, according to the International Trade Center, access to financing remains a key constraint for small and medium enterprises in Africa's pharmaceutical sector. The high costs and investment requirements for lyophilization often make it unfeasible for such companies with limited budgets to manufacture and commercialize lyophilized drugs. This has restricted the growth of availability of affordable lyophilized drug products particularly in developing markets.
Market Opportunities: Collaborations with CMOs for large-scale lyophilization
Collaborations with Contract Manufacturing Organizations (CMOs) for large-scale lyophilization presents a noteworthy opportunity in the global lyophilized drugs market. Lyophilization, commonly known as freeze-drying, is a process that is integral to increasing the shelf life of various pharmaceutical drugs.
However, lyophilization also requires high capital investment and specialized infrastructure. Partnering with CMOs allows pharmaceutical companies, especially smaller ones, to benefit from lyophilization without having to bear the associated high setup costs. CMOs specializing in lyophilization offer drug makers access to their sterile lyophilization facilities, equipment, expertise and validation capabilities.
This helps pharmaceutical firms outsource their large-scale commercial lyophilization needs and focus on their core drug development activities. Such outsourcing arrangements provide pharmaceutical companies better flexibility and capacity utilization. They also help CMOs expand their service portfolio and better utilize their existing facilities. Important drugs including vaccines often require lyophilization to achieve greater stability at ambient temperatures.
As development of novel biologic drugs and vaccines gain prominence, need for robust lyophilization infrastructure is also growing steadily. As per the World Health Organization, nearly 50% of global vaccine production is outsourced to CMOs.
This outsourcing is expected to rise further with growing demand for affordable vaccines worldwide and complexities in vaccine manufacturing. Similarly, the biopharmaceutical market is expected to grow substantially in the coming years owing to biologic drug approvals and their increasing usage.
As biologics generally have short shelf lives and require lyophilization for storage and distribution, their rising demand will further augment the requirement for large-scale lyophilization capacity. Collaborations between drug firms and CMOs can help match this growing need for lyophilization and enhance availability of important biologic drugs and vaccines across global markets.
Segmental Insights

Global Lyophilized Drugs Market Insights, By Drug Class
In terms of drug class, the anti-infective segment is expected to contribute the highest share of the market with 26.5% in 2026 owing to the rising global prevalence of both communicable and non-communicable infectious diseases. The advent of drug-resistant forms of various pathogens has necessitated the development of novel anti-infective drugs with improved efficacy.
Furthermore, the growing geriatric population worldwide is also amplifying the demand for anti-infective drugs since aged individuals are more susceptible to different infections.
The ability of lyophilized anti-infective drugs to withstand harsh storage conditions without losing potency also contributes to their widespread use in tropical and resource-constrained settings. Advances in lyophilization technologies have further enhanced the stability and shelf-life of various anti-infective drugs.
Global Lyophilized Drugs Market Insights, By Indication
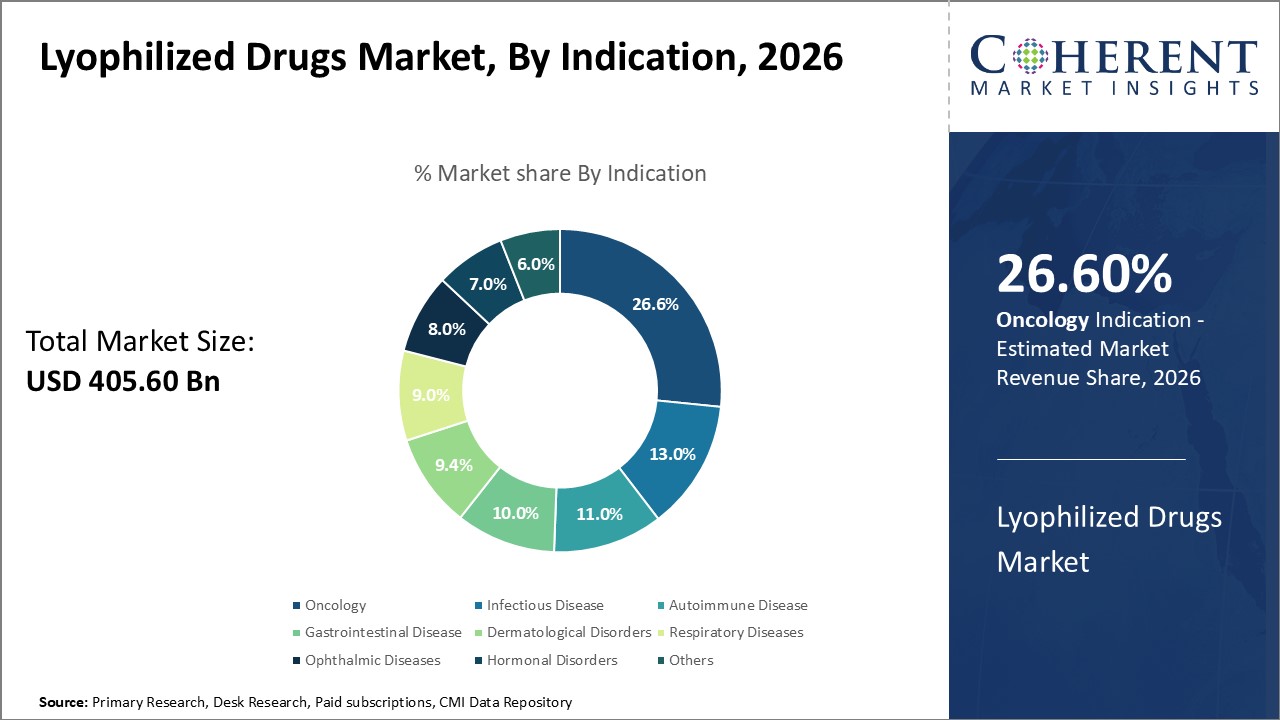
In terms of indication, the oncology segment is expected to contribute the highest share of the market with 26.62% in 2026 due to the increasing cancer burden worldwide and growing focus on targeted therapies. Lyophilization allows for improved stability and extended shelf life of potent anti-cancer drugs during storage and transportation to remote areas. It also facilitates flexible dosing and reconstitution of drugs as per patient needs.
The advent of personalized medicine and preference for oral formulations of cancer drugs are supporting the demand for lyophilized oncology drugs. Moreover, lyophilization preserves the biological activity of peptides and proteins used in biologic therapies for cancer.
Global Lyophilized Drugs Market Insights, By Packaging Type
In terms of packaging type, the vial segment is expected to contribute the highest share of the market with 41.5% in 2026 because of various inherent advantages. Vials facilitate precise dosing of drugs along with ease of handling during reconstitution. Their break-resistant and leak-proof properties make vials suitable for shipping and transporting fragile lyophilized drugs.
Furthermore, vials allow visual identification of powder content and maintain sterility until puncturing for injection or infusion. Vials are also recyclable and environment-friendly, contributing to their widespread popularity among pharmaceutical manufacturers and healthcare providers for packaging lyophilized drugs.
Global Lyophilized Drugs Market - Regional Insights
North America Lyophilized Drugs Market Analysis and Trends
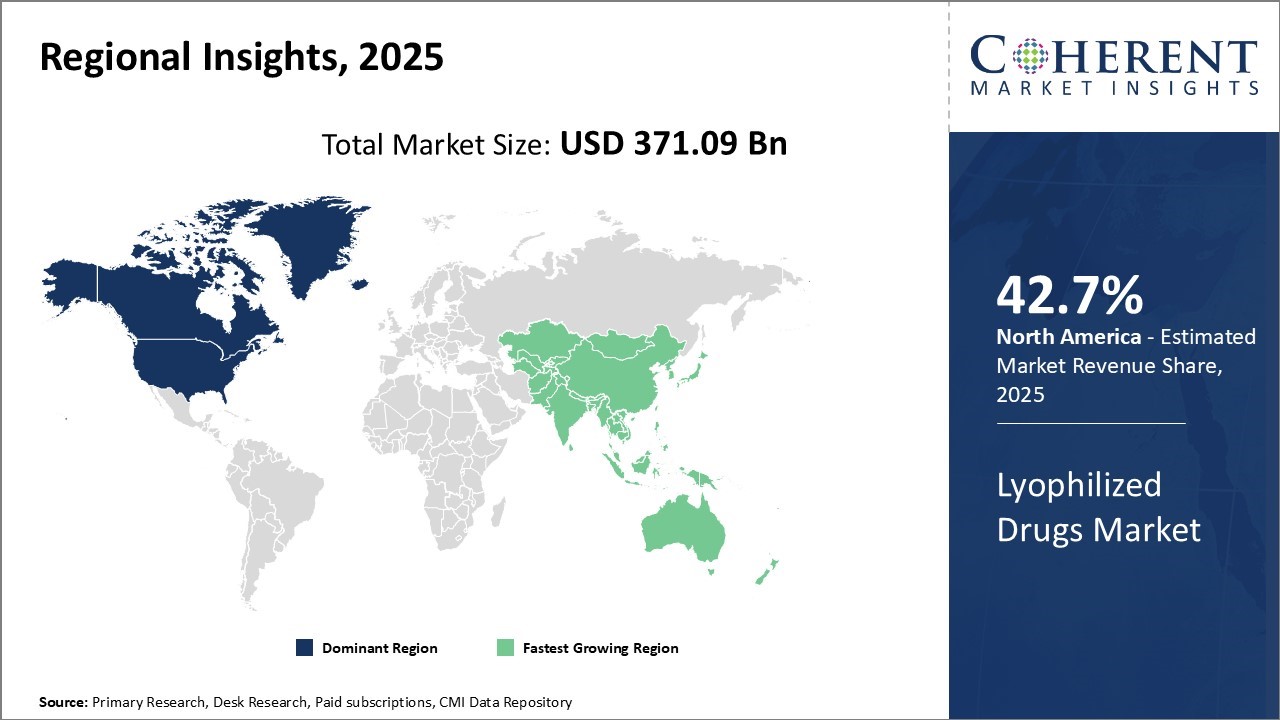
North America has solidified its position as the dominant region in the global lyophilized drugs market, projected to account for 42.7% of the total market in 2026. The U.S. and Canada lead the region’s growth, driven by the presence of major pharmaceutical companies actively engaged in R&D and new drug development. This has fostered early adoption of lyophilization technology across various therapeutic segments.
Additionally, North America's advanced cold chain and logistics infrastructure supports Just-In-Time delivery of these temperature-sensitive products throughout vast healthcare networks.
Stringent regulatory standards enforced by authorities like the U.S. FDA have played a crucial role in encouraging companies to maintain high product quality, facilitating strong export performance to global markets.
However, the region is beginning to face pricing pressures, particularly in the U.S., where reimbursement constraints are starting to impact average selling prices of certain lyophilized drugs. Despite this challenge, North America remains the key center for innovation and global supply of lyophilized pharmaceuticals.
Asia Pacific Lyophilized Drugs Market Analysis and Trends
Asia Pacific has emerged as the fastest growing region in the global lyophilized drugs market, fueled by rapid economic development, expanding healthcare infrastructure, and rising disposable incomes across countries such as China, India, Japan, and South Korea. The region is witnessing increasing domestic demand for high-quality injectable drugs, prompting both multinational and local pharmaceutical firms to invest in local manufacturing through technology transfers and licensing agreements.
China’s “Made in China 2026” initiative exemplifies the region’s strategic focus on self-reliance in key medical technologies, including lyophilization. This has helped reduce dependence on imports and enabled the country to offer competitively priced products globally.
Other nations in the region are also encouraging the production of biosimilars and generic lyophilized drugs, aiming to meet the healthcare needs of their large and diverse populations at more affordable costs. These supportive policies and growing capabilities position Asia Pacific as a major growth engine in the global lyophilized drugs market.
Market Report Scope
Lyophilized Drugs Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 405.60 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 9.3% | 2033 Value Projection: | USD 755.86 Bn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
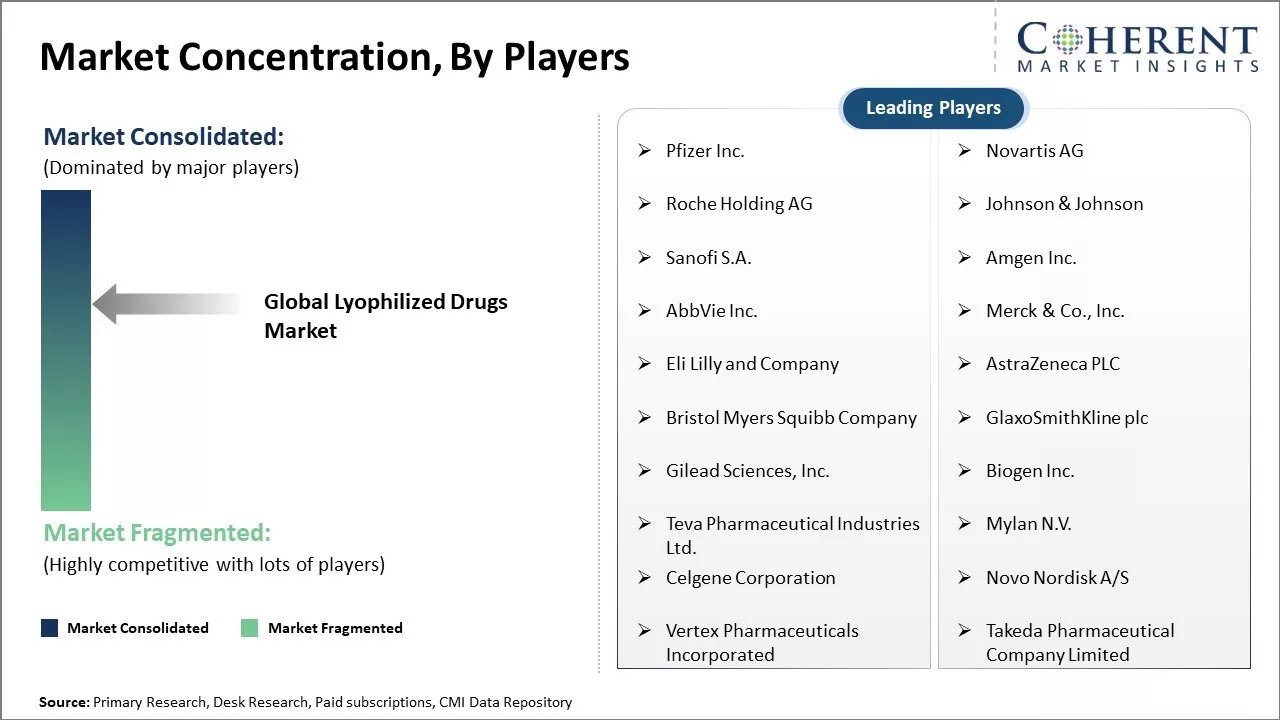
| Companies covered: | Pfizer Inc., Novartis AG, Roche Holding AG, Johnson & Johnson, Sanofi S.A., Amgen Inc., AbbVie Inc., Merck & Co., Inc., Eli Lilly and Company, AstraZeneca PLC, Bristol Myers Squibb Company, GlaxoSmithKline plc, Gilead Sciences, Inc., Biogen Inc., Teva Pharmaceutical Industries Ltd., Mylan N.V., Celgene Corporation, Novo Nordisk A/S, Vertex Pharmaceuticals Incorporated, and Takeda Pharmaceutical Company Limited | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Lyophilized Drugs Market Key Developments
- In July 2023, Berkshire Sterile Manufacturing (BSM), a biotechnology company based in Massachusetts, plans to double its lyophilization capacity by adding a second lyophilizer to its fully automated, isolator-based filling line. This expansion aims to meet increasing demand, allowing them to process up to 70,000 10R vials per run to better serve client needs and patient populations.
- In July 2020, Mylan N.V. received regulatory approval from the Drug Controller Marketed under the brand name DESREM, it will be available starting July at INR 4,800 per vial, significantly cheaper than in developed countries.
- In September 2021, Lonza invested in additional drug product manufacturing capabilities in Switzerland with a new aseptic flexible filling line at its Stein facility.
Analyst Viewpoint
- The global lyophilized drugs market holds promising growth opportunities over the forecast period. Rising chronic diseases and increasing preference for biologics which require freeze drying technology for stabilization are major drivers. Further, lyophilized formulations offer the benefits of increased shelf life and stability which aids long-term transportation and storage.
- This will increase demand from pharmaceutical companies. However, high costs associated with lyophilization equipment and lengthy production processes pose challenges.
- North America will continue dominating due to the presence of many lyophilized drug manufacturers and favorable regulatory environment supporting new product approvals.
- The Asia Pacific region is expected to witness the highest growth. Rapid economic development, growing healthcare expenditure, and rising patient pool make it an attractive market. China, India, and Japan are likely to account for majority share.
- In terms of drug class, vaccines are projected to be the fastest growing segment attributed to increasing immunization programs worldwide and rising focus on stockpiling communicable disease vaccines. Monoclonal antibodies hold significant market share owing to extensive R&D and their increasing role in cancer and autoimmune disease treatment.
- Overall, the lyophilized drugs market shows strong prospects against the backdrop of innovations to simplify lyophilization, reduce costs, and expedite processes.
Market Segmentation
- Drug Class Insights (Revenue, USD Bn, 2021 - 2033)
- Anti-infective
- Antineoplastic
- Diuretics
- Proton Pump Inhibitor
- Anesthetic
- Anticoagulant
- NSAID’s
- Others
- Indication Insights (Revenue, USD Bn, 2021 - 2033)
- Oncology
- Infectious Disease
- Autoimmune Disease
- Gastrointestinal Disease
- Dermatological Disorders
- Respiratory Diseases
- Ophthalmic Diseases
- Hormonal Disorders
- Others
- Packaging Type Insights (Revenue, USD Bn, 2021 - 2033)
- Vial
- Injection
- Cartridge
- Distribution Channel Insights (Revenue, USD Bn, 2021 - 2033)
- Hospital Pharmacy
- Retail Pharmacy
- Online Pharmacy
- Regional Insights (Revenue, USD Bn, 2021 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC Countries
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
- Key Players Insights
- Pfizer Inc.
- Novartis AG
- Roche Holding AG
- Johnson & Johnson
- Sanofi S.A.
- Amgen Inc.
- AbbVie Inc.
- Merck & Co., Inc.
- Eli Lilly and Company
- AstraZeneca PLC
- Bristol Myers Squibb Company
- GlaxoSmithKline plc
- Gilead Sciences, Inc.
- Biogen Inc.
- Teva Pharmaceutical Industries Ltd.
- Mylan N.V.
- Celgene Corporation
- Novo Nordisk A/S
- Vertex Pharmaceuticals Incorporated
- Takeda Pharmaceutical Company Limited
Sources
Primary Research Interviews
- Pharmaceutical Manufacturing Executives
- Lyophilization Equipment Manufacturers
- Contract Development and Manufacturing Organizations (CDMOs)
- Regulatory Affairs Specialists
- Others
Databases
- FDA Orange Book Database
- EMA European Medicines Database
- PharmaCompass
- GlobalData Pharmaceutical Intelligence
- Others
Magazines
- Pharmaceutical Manufacturing Magazine
- BioPharm International
- Pharmaceutical Technology
- BioProcess International
- Others
Journals
- Journal of Pharmaceutical Sciences
- International Journal of Pharmaceutics
- Pharmaceutical Research
- Others
Newspapers
- Financial Times
- The Wall Street Journal
- Reuters Health News
- BioPharma Dive
- Pharmaceutical Executive
- Others
Associations
- International Society for Pharmaceutical Engineering (ISPE)
- Parenteral Drug Association (PDA)
- American Association of Pharmaceutical Scientists (AAPS)
- European Federation of Pharmaceutical Industries and Associations (EFPIA)
- Others
Public Domain Sources
- U.S. Food and Drug Administration (FDA)
- European Medicines Agency (EMA)
- World Health Organization (WHO)
- ClinicalTrials.gov
- Others
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of information for last 8 years
*Definition: The global lyophilized drugs market provides customers with lyophilized or freeze-dried pharmaceutical drugs that can be stored at room temperature for longer periods without refrigeration. These drugs are dehydrated versions of injectable medications, vaccines, biologics and other sterile products that are reconstituted with sterile water or saline prior to administration. Lyophilization helps extend the shelf life of drugs and makes transportation and storage easier at a global scale. The lyophilized drugs marketed worldwide are designed to improve access and affordability of medications.
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Lyophilized Drugs Market size is estimated to be valued at USD 405.60 Bn in 2026, and is expected to reach USD 755.86 Bn by 2033.
The CAGR of the global Market is projected to be 9.3% from 2026 to 2033.
Increasing adoption of lyophilization in pharmaceuticals companies and growing need for temperature-controlled manufacturing process are the major factors driving the growth of global lyophilized drugs market.
High manufacturing costs and stringent regulatory environment are the major factors hampering the growth of the global lyophilized drugs industry.
In terms of drug class, the anti-infective segment is estimated to dominate the market revenue share in 2026.
Pfizer Inc., Novartis AG, Roche Holding AG, Johnson & Johnson, Sanofi S.A., Amgen Inc., AbbVie Inc., Merck & Co., Inc., Eli Lilly and Company, AstraZeneca PLC, Bristol Myers Squibb Company, GlaxoSmithKline plc, Gilead Sciences, Inc., Biogen Inc., Teva Pharmaceutical Industries Ltd., Mylan N.V., Celgene Corporation, Novo Nordisk A/S, Vertex Pharmaceuticals Incorporated, and Takeda Pharmaceutical Company Limited are the major players.
North America is expected to lead the global market.