

Neurology Devices Market Size and Share Analysis - (2026-2033)
Neurology Devices Market is estimated to be valued at USD 37.4 Mn in 2026 and is expected to reach USD 106.3 Mn in 2033, exhibiting a compound annual growth rate (CAGR) of 16.1% from 2026 to 2033.
Key Takeaways
- Based on Device Type, the CSF Management Devices segment is expected to lead the market with 43% share in 2026, due to increasing cases of hydrocephalus and brain injuries.
- Based on End User, the Hospital segment is expected to hold the largest share of the market in 2026, due to advanced infrastructure and high patient volume.
- Based on Region, North America is set to lead the neurology devices market with 34.8% share in 2026. While, Asia Pacific is anticipated to be the fastest growing region.
Market Overview
The neurology devices market is witnessing robust growth driven by rising neurological disorders, technological advancements, and increased healthcare spending. Innovations in imaging, neurostimulation, and monitoring tools are enhancing diagnostic precision and treatment efficacy. Aging populations and growing awareness of neurological health further fuel neurology devices market demand. Emerging economies are expanding access to advanced neurology care, creating new opportunities for device manufacturers. Regulatory support and strategic collaborations are also accelerating product development and adoption across global healthcare systems.
Current Events and their Impact on the Neurology Devices Market
Current Event | Description and its Impact |
Artificial Intelligence and Digital Health Revolution |
|
Regulatory Landscape Evolution and Approval Processes |
|
Role of Artificial Intelligence (AI) in Neurology Devices Market
Artificial intelligence is revolutionizing the neurology devices market by enabling faster, more accurate diagnostics, personalized treatments, and real-time brain monitoring. AI algorithms analyze complex neurological data from EEGs and MRIs to detect conditions like epilepsy, Alzheimer’s, and stroke with greater precision. In critical care, AI-powered systems provide immediate seizure detection and support remote neurologist collaboration. Brain-computer interfaces also benefit from AI’s ability to decode neural signals and adapt stimulation therapies based on patient-specific responses. As demand for smarter neurotechnology grows, AI is becoming central to innovation in imaging, neurostimulation, and therapeutic devices, especially in regions like the U.S., China, and Europe.
For instance, in May 2025, Natus Neuro launched BrainWatch, an AI-powered EEG system designed for rapid neurological assessment in critical care. Integrated with Persyst AI algorithms and NeuroWorks software, the wearable device enables real-time seizure detection and remote neurologist collaboration. This innovation enhances point-of-care diagnostics, marking a significant advancement in AI-driven neurology devices.
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Segmental Insights

Neurology Devices Market Insights, By Device Type: CSF Management Devices See Rising Demand Due To Increasing Cases of Hydrocephalus and Brain Injuries
In terms of device type, the CSF management devices segment is expected to lead the market with 43% share in 2026, due to the rising incidence of neurological conditions such as hydrocephalus, traumatic brain injuries, and CNS infections. The aging global population and increased use of diagnostic imaging have amplified the need for timely cerebrospinal fluid regulation. Technological advancements in shunt systems and drainage devices further support this growing demand.
For instance, in August in 2026, Plus Therapeutics unveiled promising results from its CNSide CSF assay platform, designed to detect and monitor central nervous system cancers using cerebrospinal fluid samples. Presented at the 2025 SNO Annual Meeting, the platform demonstrated high sensitivity and specificity, marking a significant advancement in CSF-based diagnostics and enhancing precision oncology for CNS malignancies.
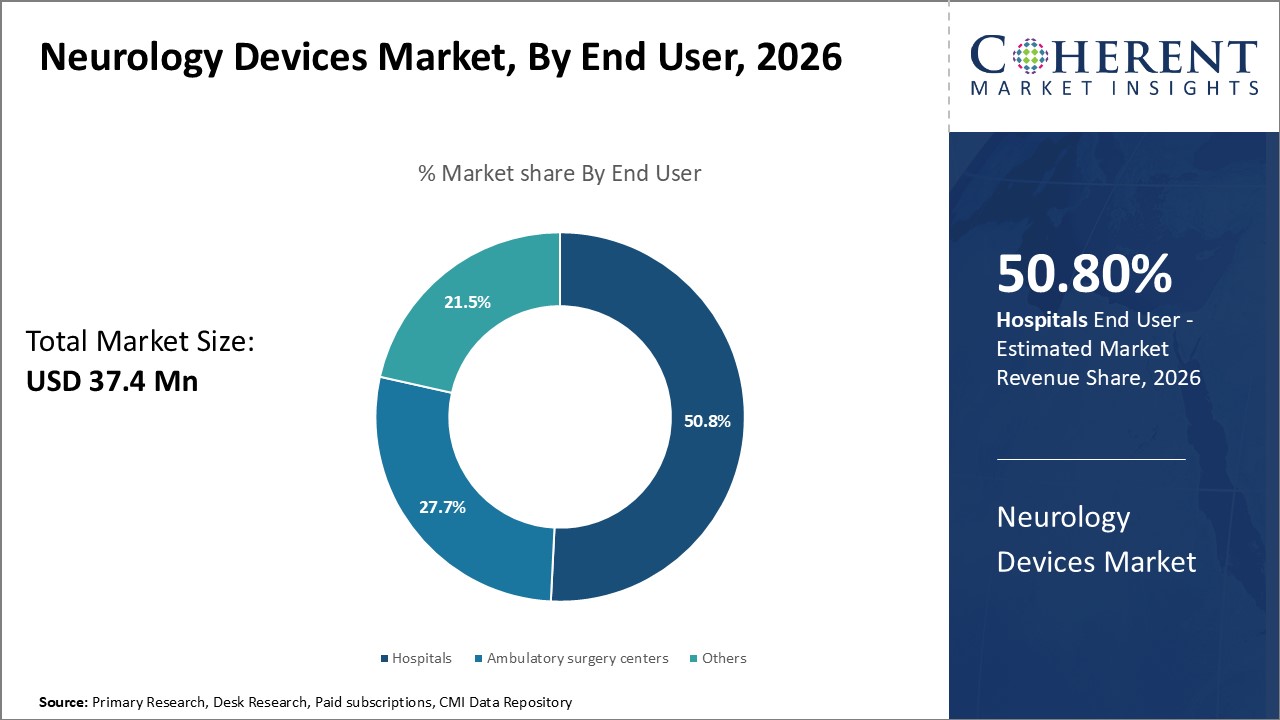
Neurology Devices Market Insights, By End User: Hospitals Lead Is Due to Advanced Infrastructure and High Patient Volume
In terms of end user, the hospital segment is projected to dominate the market with the largest share in 2026, due to their advanced infrastructure, skilled neurology professionals, and capacity to perform complex procedures. Rising neurological disorders and increased patient admissions for stroke, epilepsy, and neurodegenerative diseases further boost device utilization. Hospitals also benefit from favorable reimbursement policies and rapid adoption of cutting-edge technologies.
For instance, in June 2026, KEM Hospital in Pune launched a state-of-the-art Neurosciences Department, offering integrated care for neurological, psychiatric, stroke, and rehabilitation needs. This one-stop facility is equipped with advanced neurology devices and aims to enhance diagnosis and treatment outcomes. The initiative reflects growing hospital-based demand for comprehensive neurological services in India’s evolving healthcare landscape.
Regional Insights
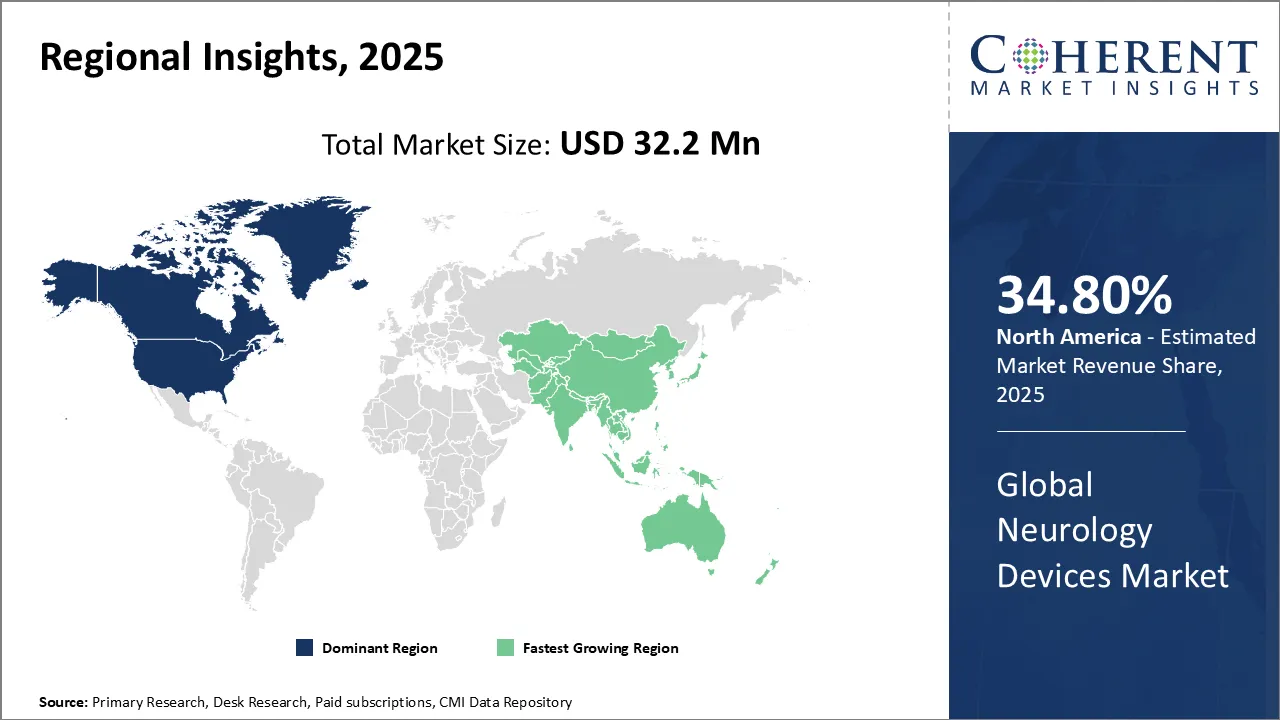
North America Neurology Devices Market Analysis & Trends
North America, holding 34.8% share in 2026, is leading the neurology devices market, due to rising neurological disorders, advanced healthcare infrastructure, and strong investment in medical technology. The region benefits from early adoption of neurostimulation and interventional devices, robust R&D, and favorable reimbursement policies. Aging populations and increased awareness of neurological health further drive market expansion.
For instance, in November 2024, Nihon Kohden acquired U.S.-based Ad-Tech Medical Instrument Corporation, expanding its neurology device portfolio with specialized electrodes for epilepsy treatment and brain monitoring. The move strengthens its presence in North America and enhances capabilities in EEG systems, SEEG, and intraoperative neuromonitoring, reinforcing its commitment to advancing neurological care through innovative technologies.
Asia Pacific Neurology Devices Market Analysis & Trends
Asia Pacific region is expected to be the fastest growing region over the forecast period, due to rising neurological disorders, expanding healthcare infrastructure, and growing awareness of neurodegenerative conditions. Aging populations, increased stroke incidence, and improved access to advanced diagnostics and treatments are driving adoption. Government initiatives and rising investments in medical technology further accelerate market growth across emerging economies.
For instance, in February 2026, Johnson & Johnson MedTech launched the CEREGLIDE 9.2 Catheter System, designed to treat acute ischemic stroke. Developed by CERENOVUS, the device enhances navigation through delicate cerebral vessels, aiming to improve procedural efficiency and patient outcomes. This innovation marks a significant advancement in neurovascular care and stroke intervention technology.
Neurology Devices Market Outlook Country-Wise
The U.S. Neurology Devices Market Trends
The U.S. neurology devices market is highly demanding due to a growing aging population, rising prevalence of neurological disorders like stroke and Alzheimer’s, and strong healthcare infrastructure. High adoption of advanced technologies and increased investment in neurovascular research further drive demand, making the U.S. a global leader in neurology device innovation and usage.
For instance, in June 2026, Hyperfine received FDA clearance for its next-generation Swoop® system, a portable MRI device powered by OptiVu™ AI software. Designed for bedside brain imaging, the system delivers enhanced image quality and faster diagnostics for neurological conditions. Headquartered in Connecticut, USA, Hyperfine’s innovation marks a major advancement in accessible neuroimaging technology.
China Neurology Devices Market Trends
China’s neurology devices market is booming due to its aging population, rising cases of stroke, Alzheimer’s, and Parkinson’s disease, and increased healthcare investment. The integration of AI-driven diagnostic tools and growing demand for advanced neurostimulation and imaging technologies are accelerating market growth, making China a key player in global neurotech innovation.
For instance, in October 2026, China launched a cutting-edge magnetic resonance platform in Tianjin, integrating MRI and EEG technologies to advance brain-computer interface research. Developed by Tianjin University and Shanghai United Imaging Healthcare, the system enables real-time brain observation and regulation, supporting neurological diagnostics, mental health evaluation, and rehabilitation. This marks a major leap in China’s neurotechnology innovation.
Market Report Scope
Neurology Devices Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 37.4 Mn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 16.1% | 2033 Value Projection: | USD 106.3 Mn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | B. Braun Melsungen AG, Boston Scientific Corporation, BIONIK Laboratories Corp., Integra LifeSciences Holdings Corporation, Johnson and Johnson, Magstim Co Ltd., Braintale SAS, Medtronic, Abbott, Zimmer Biomet, Stryker Corporation, Helius Medical Technologies, Inc., Avanos Medical, Inc., W.L. Gore & Associates, Inc., HeadsafeIP Pty Ltd., Cerus Endovascular Ltd., and Cyberonics, Inc | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Global Neurology Devices Market Drivers
Increase in the product approval by the regulatory bodies
The neurology devices market size is witnessing significant growth, driven in part by the rising number of product approvals from global regulatory bodies such as the FDA and EMA. These approvals accelerate the introduction of innovative technologies like neurostimulation systems, thrombectomy devices, and advanced imaging tools. Regulatory support enhances market accessibility, boosts investor confidence, and shortens time-to-market for novel solutions. As a result, manufacturers are increasingly investing in R&D to meet evolving clinical needs. This trend not only expands therapeutic options for neurological disorders but also contributes to the overall expansion and competitiveness of the neurology devices market globally.
An increase in the adoption of inorganic growth strategies such as acquisition by the key players in the market
The rising adoption of inorganic growth strategies, particularly acquisitions, is reshaping the neurology devices market growth landscape. Key players are acquiring specialized firms to expand their product portfolios, access advanced technologies, and enter new geographic markets. These strategic moves accelerate innovation and streamline regulatory approvals, enabling faster deployment of cutting-edge neurology solutions. Acquisitions also foster synergies in R&D and distribution, enhancing competitiveness and responsiveness to clinical needs. As neurological disorders become more prevalent, such consolidation efforts are crucial for meeting the growing demand for minimally invasive, high-precision devices. This trend significantly boosts the overall momentum of the neurology devices market.
Global Neurology Devices Market: Key Trends
Increase prevalence of neurology disorder
The increasing prevalence of neurological disorders such as Alzheimer’s, Parkinson’s, epilepsy, and stroke is significantly driving demand for advanced diagnostic and therapeutic tools. As global populations age and lifestyle-related risk factors rise, the burden of brain-related conditions is escalating. This surge necessitates the development and deployment of innovative neurology devices, including EEG systems, neurostimulation implants, and portable imaging technologies. According to neurology devices market research, this trend is expected to fuel substantial market growth, encouraging investment in AI integration, wearable solutions, and minimally invasive technologies. The growing need for early detection and continuous monitoring further amplifies the market’s expansion potential.
According to World Health Organization (WHO), more than one in three people worldwide, over 3 billion individuals are living with a neurological condition, making these disorders the leading cause of illness and disability across the globe.
Neurology Devices Market Opportunity
Wearable and Portable Neuro Devices
Wearable and portable neuro devices are transforming neurological care by enabling real-time, remote monitoring and diagnostics. These compact tools, such as portable EEGs and MRIs, allow clinicians to assess brain activity at the bedside or in non-hospital settings, improving access and response time. Innovations like AI-powered seizure detection and wireless brain imaging enhance precision and usability. As demand for accessible neurotechnology rises, especially in emergency and rural care, these devices are expected to drive significant growth. According to neurology devices market forecast reports, the sector will expand rapidly, fueled by technological advancements and increasing prevalence of neurological disorders worldwide.
Analyst Opinion (Expert Opinion)
The global neurology devices market value is entering a phase of strategic maturation, where innovation and differentiation outweigh sheer scale. Established segments like neurostimulation and interventional neurology are being reshaped by adaptive deep-brain stimulation, flow-diverter implants, and wearable seizure monitoring. In 2024, neurostimulation accounted for approximately 54.6% of revenue, highlighting the importance of IP depth and regulatory validation in maintaining competitive advantage.
A key structural shift is occurring from hospital-based acute interventions to chronic and home-based care, with home-care devices projected to grow faster, emphasizing recurring service and data-driven revenue models. Simultaneously, pricing pressure and reimbursement complexities are rising, particularly in mature segments like spinal-cord stimulators, requiring manufacturers to demonstrate clear health-economic value.
Strategically, leadership will favor firms integrating software, analytics, and connected services into their devices. Success will hinge on interoperability, lifecycle value, regional nuance, and service-oriented models. The market now rewards companies capable of delivering comprehensive neuro-care ecosystems, rather than standalone hardware, ensuring patient outcomes and health-system efficiency drive long-term growth.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Global Neurology Devices Market: Key Developments
- In November 2025, INBRAIN Neuroelectronics, based in Spain, partnered with Microsoft to advance Agentic AI for precision neurology and brain-computer interface therapeutics. The collaboration aims to enhance real-time neural data processing and personalized neurostimulation using graphene-based implantable devices. This cross-regional initiative marks a breakthrough in intelligent neurotechnology across Europe and the U.S.
- In June 2025, Fujirebio launched a fully automated neuro testing solution, expanding its portfolio of neurological diagnostics. The new platform enables high-throughput analysis of biomarkers like tau and amyloid proteins, crucial for detecting neurodegenerative diseases. This innovation enhances lab efficiency and supports early, accurate diagnosis, reinforcing Fujirebio’s commitment to advancing neuro testing technologies.
- In September 2024, ZEISS unveiled a robotic visualization system designed for neurosurgery, enhancing precision and workflow efficiency. The system integrates advanced optics with robotic-assisted positioning, allowing surgeons to maintain optimal visualization during complex procedures. This innovation marks a significant step in surgical technology, supporting minimally invasive techniques and improving outcomes in neurological care.
- In February, 2023, LivaNova PLC, a medical technology and innovation company, launched SenTiva DUO, an implantable pulse generator (IPG) with a dual-pin header to provide Vagus Nerve Stimulation (VNS) Therapy for the treatment of drug-resistant epilepsy. The dual-pin header distinguishes this latest IPG from the original SenTiva, which is only available in a single-pin format. Now, with SenTiva DUO, patients considered “the pioneers of VNS Therapy” who were originally implanted with a dual-pin lead and IPG can receive the benefits of the latest VNS Therapy technology.
Market Segmentation
- Global Neurology Devices Market, By Device Type (Revenue, USD Mn, 2021 - 2033)
- CSF Management devices
- CSF Shunt Devices
- CSF Drainage Devices
- Interventional Neurology Devices
- Neuro Thrombectomy
- Cerebral Balloon Angioplasty & Stents
- Aneurysm Coiling
- Support Devices
- Neuro-surgery Devices
- Neuro-endoscopes
- Sterotactic Systems
- Ultrasonic Aspirators
- Aneurysm Clips
- Neuro-stimulation Devices
- Spinal Cord Stimulation
- Deep Brain Stimulation
- Sacral Nerve Stimulation
- Vagus Nerve Stimulation
- Gastric Nerve Stimulation
- CSF Management devices
- Global Neurology Devices Market, By End User (Revenue, USD Mn, 2021 - 2033)
- Hospitals
- Ambulatory Surgery Centers
- Others
- Global Neurology Devices Market, By Region (Revenue, USD Mn, 2021 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC Countries
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
- North America
- Global Neurology Devices Market: Key Players
- Braun Melsungen AG
- Boston Scientific Corporation
- BIONIK Laboratories Corp.
- Integra LifeSciences Holdings Corporation
- Johnson and Johnson
- Magstim Co Ltd.
- Braintale SAS
- Medtronic
- Abbott
- Zimmer Biomet
- Stryker Corporation
- Helius Medical Technologies, Inc.
- Avanos Medical, Inc.
- L. Gore & Associates, Inc.
- HeadsafeIP Pty Ltd.
- Cerus Endovascular Ltd.
- Cyberonics, Inc
Sources
Primary Research Interviews from the following stakeholders
Stakeholders
- Interviews with neurologists, neurosurgeons, hospital administrators, clinical researchers, biomedical engineers, and procurement heads across leading global markets.
Specific stakeholders
- Heads of neurology departments at hospitals and medical centers (e.g., Mayo Clinic, AIIMS, Cleveland Clinic, Charité – Berlin)
- Clinical research leads at neuroscience research institutes (e.g., Max Planck Institute for Brain Research, National Institute of Neurological Disorders and Stroke – NINDS)
- Biomedical engineers and device specialists at hospitals and rehabilitation centers
- Procurement and operations managers at hospital networks and healthcare systems (e.g., Apollo Hospitals, Cleveland Clinic, NHS Trusts)
- R&D managers at medical device manufacturing units focusing on neurology (e.g., MRI, EEG, TMS, and neurostimulation devices)
- Product development leads at device component suppliers (e.g., neuroimaging coils, electrodes, sensors)
Databases
- World Health Organization (WHO) Global Health Observatory
- U.S. Food & Drug Administration (FDA) Medical Device Databases
- European Medicines Agency (EMA) Device Registries
- gov (U.S.)
- National Center for Biotechnology Information (NCBI)
- PubMed
- Japan External Trade Organization (JETRO) – Medical Devices Section
- Ministry of Health and Family Welfare (MoHFW), India
Magazines
- Neurology Today
- Neurotech Reports
- Medical Device and Diagnostic Industry (MD+DI)
- MedTech Insight
- IEEE Pulse – Biomedical Engineering Section
Journals
- Journal of Neurology, Neurosurgery, and Psychiatry
- Brain: A Journal of Neurology
- Frontiers in Neurology
- Neuromodulation: Technology at the Neural Interface
- IEEE Transactions on Neural Systems and Rehabilitation Engineering
Newspapers
- The Wall Street Journal – Health & Technology
- The New York Times – Health & Science
- The Hindu – Health & Science
- Financial Times – Medical Technology
- Nikkei Asia – Healthcare & Devices
Associations
- World Federation of Neurology (WFN)
- International Brain Research Organization (IBRO)
- American Academy of Neurology (AAN)
- European Academy of Neurology (EAN)
- Neurotechnology Industry Organization (NIO)
- Indian Medical Association (IMA) – Neurology Section
Public Domain Sources
- U.S. National Institutes of Health (NIH)
- Centers for Disease Control and Prevention (CDC), U.S.
- Ministry of Health and Family Welfare (MoHFW), India
- National Institute of Neurological Disorders and Stroke (NINDS)
- European Union Public Health Portal – Medical Device Reports
- NITI Aayog – Healthcare Technology Reports
- Health Ministry and Medical Device Authority (Thailand, Malaysia, Japan, China)
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of information for last 8 years
Definition: Neurological devices are medical devices that are used to diagnose, monitor, or treat conditions that affect the nervous system. Neurological devices can help diagnose, prevent, and treat a variety of neurological disorders and conditions such as Alzheimer’s disease, Parkinson’s disease, major depression, epilepsy, spinal cord injury, and traumatic brain injury.
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Neurology Devices Market is estimated to be valued at USD 37.4 Mn in 2026, and is expected to reach USD 106.3 Mn by 2033.
The CAGR of the Neurology Devices Market is projected to be 16.1% from 2026 to 2033.
Increase in the product approval by the regulatory bodies and an increase in the adoption of inorganic growth strategies such as acquisition by the key players in the market are expected to drive the market growth.
CSF Management devices are the leading device type segment in the market.
The major factors that can hamper growth of the market include high cost of neurology devices.
Major players operating in the market B. Braun Melsungen AG, Boston Scientific Corporation, BIONIK Laboratories Corp., Integra LifeSciences Holdings Corporation, Johnson and Johnson, Magstim Co Ltd., Braintale SAS, Medtronic, Abbott, Zimmer Biomet, Stryker Corporation, Helius Medical Technologies, Inc., Avanos Medical, Inc., W.L. Gore & Associates, Inc., HeadsafeIP Pty Ltd., Cerus Endovascular Ltd., and Cyberonics, Inc