

Neurostimulation Devices Market Size and Forecast – 2026 to 2033
The Neurostimulation Devices Market is anticipated to grow at a CAGR of 10.3% with USD 6.9 Bn in 2026 and is expected to reach USD 14.2 Bn in 2033. The Neurostimulation Devices Market grows as chronic neurological disorders become more prevalent, and manufacturers advance implantable technologies. Neurological conditions affect more than 3 Bn people worldwide, accounting for over 40% of the global population and representing the leading cause of illness and disability globally.
Key Takeaways
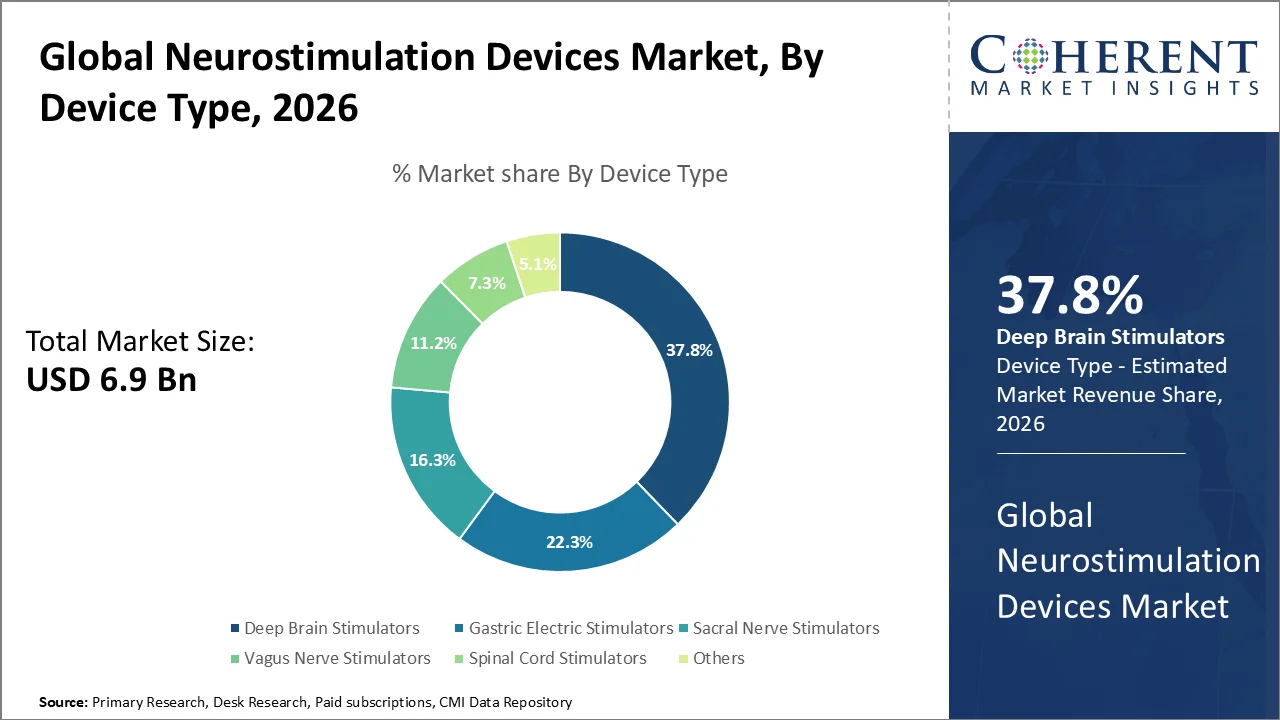
- Deep Brain Stimulators hold the largest market share of 37.8% in 2026 owing to the rising prevalence of parkinson’s disease. Parkinson’s disease affects more than 1.1 million people in the United States, with nearly 90,000 new cases diagnosed annually.
- Parkinson's Disease expected to hold largest market share of 38.9% in 2026 owing to its increasing incidence of motor fluctuations and dyskinesia. In 2025, the total number of prevalent tardive dyskinesia cases across the 7MM was approximately 1.7 million.
- Hospitals acquired the prominent market share of 42.8% in 2026 owing to the availability of advanced surgical infrastructure.
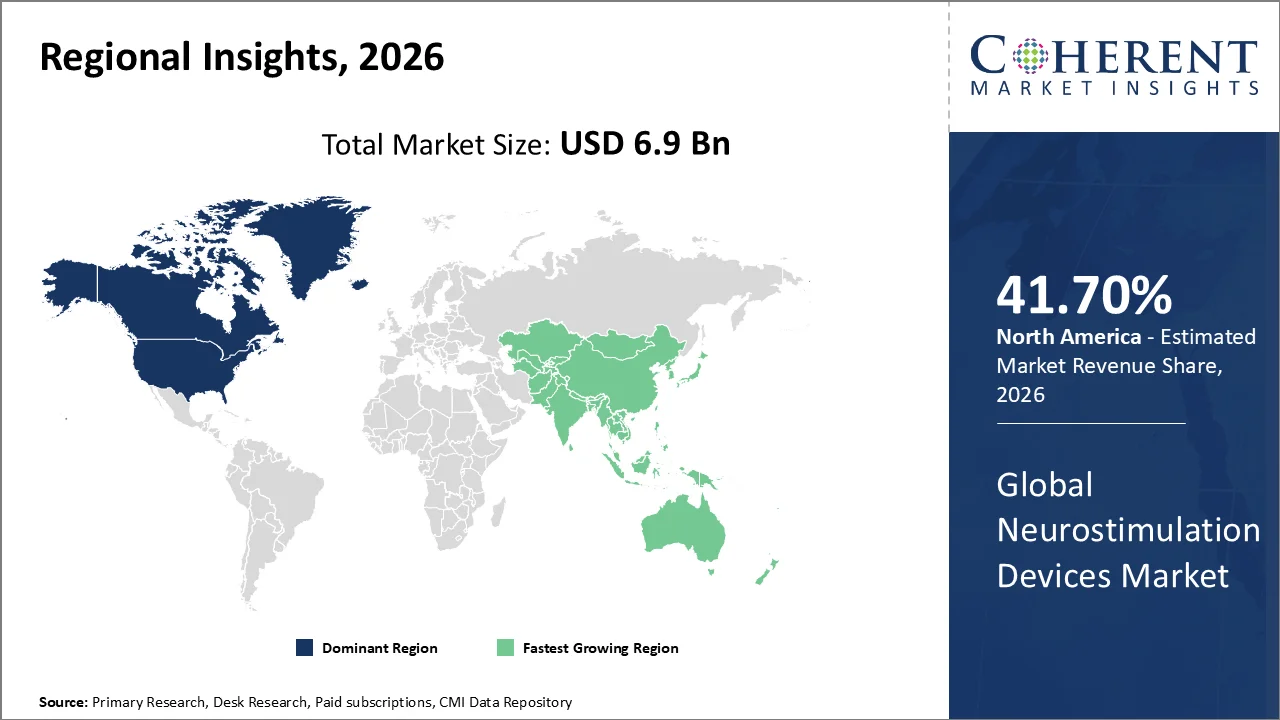
- North America is expected to acquire the dominant share of 41.7% in 2026 owing to its high prevalence of neurological disorders. Neurological conditions are the leading cause of ill health and disability worldwide, affecting more than one-third of the global population.
Current Events and Their Impact on the Neurostimulation Devices Market
Current Event | Description and its Impact |
CMS Introduces New HCPCS Codes for Hypoglossal Nerve Neurostimulators |
|
Mandatory EUDAMED Implementation in the European Union |
|
Segmental Insights
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Why is Deep Brain Stimulators Acquiring the Largest Market Share?
Deep Brain Stimulators hold the largest market share of 37.8% in 2026. The rising prevalence of Parkinson’s disease, essential tremor, and other movement disorders drives demand for deep brain stimulators, particularly as patients seek alternatives when medications fail to provide adequate symptom control. Greater clinical acceptance of DBS, improved patient selection, and innovations such as rechargeable, directional, sensing-enabled, and adaptive stimulation systems continue to accelerate adoption. Recent FDA approvals of adaptive DBS technologies highlight ongoing advances in personalized treatment. Growing specialist expertise, stronger healthcare infrastructure, and established reimbursement pathways further support the expansion of the deep brain stimulators market. Medtronic, a global healthcare technology leader, unveiled its Adaptive Deep Brain Stimulation (aDBS) system in India. The innovative technology builds on conventional DBS by providing a more advanced approach to brain stimulation, with the goal of improving the quality of life for people living with Parkinson’s disease.
Parkinson's Disease expected to hold largest market share
Parkinson's Disease expected to hold largest market share of 38.9% in 2026 owing to its increasing awareness and earlier referral for DBS. Parkinson’s disease affects more than 10 million people globally, making it the second most common neurodegenerative disorder. In the United States, approximately 1.1 million people live with the disease, with nearly 90,000 new cases diagnosed annually. The Parkinson’s disease segment of the Neurostimulation Devices Market grows as patients and clinicians seek more effective ways to manage motor symptoms such as tremor, rigidity, and bradykinesia. Long-term levodopa therapy can cause motor fluctuations and dyskinesia, encouraging clinicians to consider deep brain stimulation when medications no longer provide sufficient control. Zambon announced that the European Commission approved Hopledo (modified-release levodopa/carbidopa) for adults with Parkinson’s disease and moderate to severe motor fluctuations inadequately controlled with oral levodopa/DDC inhibitor therapy.
Which End User segment dominates the market?
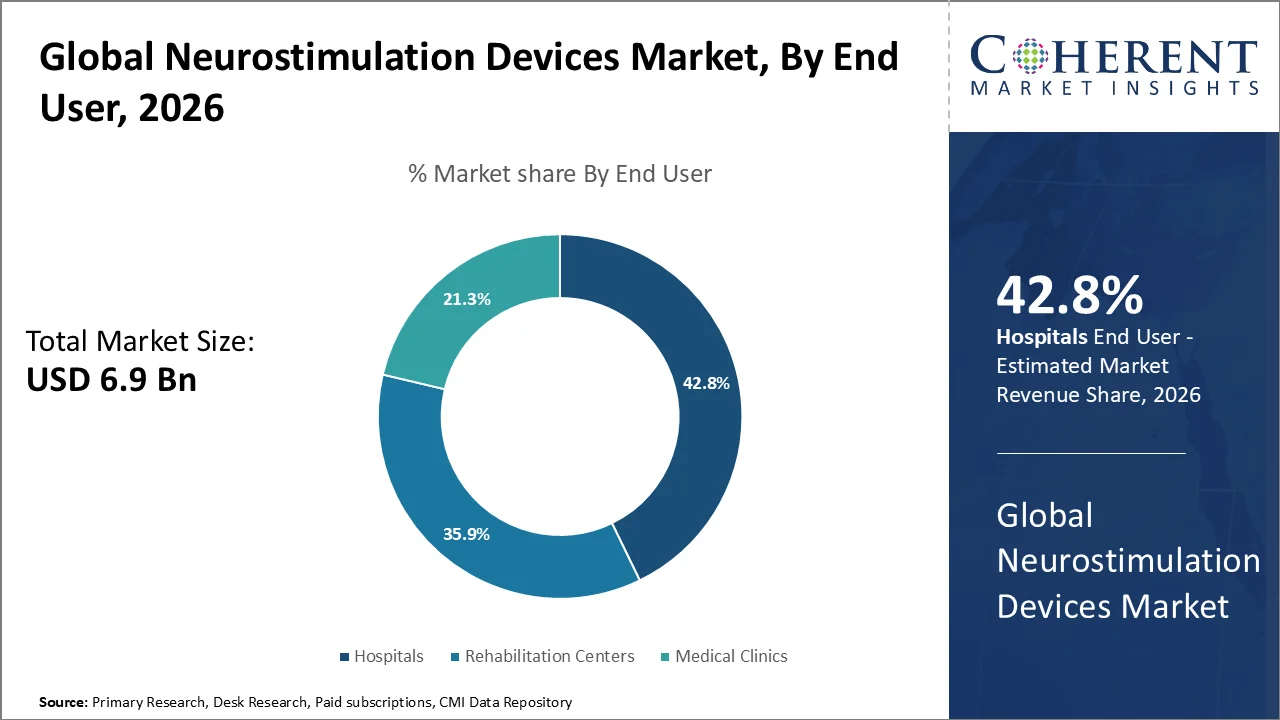
Hospitals acquired the prominent market share of 42.8% in 2026. Hospitals drive the Neurostimulation Devices Market by performing more neurostimulation procedures and investing in advanced infrastructure for complex device implantation. They employ specialized neurosurgeons and neurologists and provide advanced imaging systems, operating facilities, and comprehensive postoperative care to support effective treatment. The rising prevalence of neurological disorders, growing preference for minimally invasive therapies, technological innovations, favorable reimbursement policies, and expansion of multidisciplinary care programs further encourage hospitals to adopt and integrate neurostimulation technologies into clinical practice.
Neurostimulation Devices Market Trends
- Rising adoption of minimally invasive and non-pharmacological therapies such as deep brain stimulation (DBS), spinal cord stimulation (SCS), and vagus nerve stimulation (VNS) is increasing as patients and clinicians seek alternatives to long-term medication and conventional surgery. The growing neurological disease burden supports this demand: the World Health Organization (WHO) reported that more than 3 billion people, over one-third of the global population were living with a neurological condition in 2021, with neurological conditions identified as the leading cause of ill health and disability worldwide.
- Personalized and adaptive neurostimulation is gaining momentum, with directional leads, sensing-enabled systems, and closed-loop stimulation enabling more individualized therapy. A specific regulatory milestone supporting this trend occurred in February 2025, when the U.S. FDA approved an adaptive deep brain stimulation (aDBS) programming feature for Medtronic’s DBS Therapy for Parkinson’s disease. The approval allows stimulation to be adjusted based on patient-specific neural signals, supporting the shift toward adaptive and personalized neuromodulation.
- Advancements in rechargeable and wireless neurostimulation technologies are improving long-term device management and reducing dependence on repeated battery-replacement procedures. The FDA continued to approve updates to rechargeable neurostimulation systems; for example, in August 2026, the FDA approved manufacturing controls for rechargeable lithium-ion batteries used in Medtronic’s Intellis neurostimulation systems. Such regulatory approvals support continued development and availability of rechargeable implantable systems.
Regional Insights
North America dominates owing to rapid technological innovation
North America is expected to acquire the dominant share of 41.70% in 2026. The rising prevalence of neurological disorders and chronic pain drives North America’s Neurostimulation Devices Market, while growing demand for minimally invasive treatments and advanced healthcare infrastructure further strengthens adoption. Robust reimbursement frameworks, increasing physician and patient awareness, and the presence of leading neurostimulation device manufacturers support market expansion. Healthcare organizations and manufacturers continue investing in research and development, accelerating the adoption of closed-loop and MRI-compatible technologies and expanding specialized neurology centers across the United States and Canada. In July 2026, NeuroSigma launched U.S. sales of its second-generation Monarch eTNS System, an FDA-cleared, non-drug treatment for pediatric ADHD.
Asia Pacific Neurostimulation Devices Market Trends
The Asia Pacific neurostimulation devices market is expanding as neurological disorders, chronic pain, Parkinson’s disease, epilepsy, and spinal cord injuries become more prevalent. An aging population in countries such as Japan and China is increasing demand for advanced neurological treatments. Healthcare providers are expanding infrastructure and investing more in healthcare, while greater patient and physician awareness is encouraging adoption. Technological advances in minimally invasive, implantable, and personalized neurostimulation devices, combined with government support and stronger clinical evidence, are further driving market growth across the region. Sychedelic raised USD 3.5 million in seed funding from Cultadvisors LLP, TurboStart, and IdeaBaaz to launch closed-loop neurostimulation headphones designed to promote calm, focus, or sleep within 20 minutes.
United States Neurostimulation Devices Market Trends
In the United States, the neurostimulation devices market benefits from the growing prevalence of chronic pain and neurological disorders such as Parkinson’s disease, epilepsy, and diabetic neuropathy. An aging population drives demand for advanced treatment options, while patients increasingly favor minimally invasive therapies over conventional drug-based approaches. Manufacturers continue to advance spinal cord stimulation, deep brain stimulation, and peripheral nerve stimulation technologies, improving treatment precision and patient outcomes. Supportive reimbursement policies, robust healthcare infrastructure, expanding clinical evidence, and FDA approvals further encourage healthcare providers to adopt neurostimulation devices. Neuros Medical completed the first U.S. commercial implantation of its FDA-approved Altius Direct Electrical Nerve Stimulation System, offering a non-opioid treatment for chronic post-amputation pain in lower-limb amputees.
Japan Neurostimulation Devices Market Trends
Japan’s neurostimulation devices market is growing as its aging population and rising incidence of neurological disorders, including Parkinson’s disease, epilepsy, essential tremor, and chronic pain, increase demand for advanced treatments. Patients and healthcare providers increasingly favor minimally invasive and non-pharmacological therapies, driving the adoption of spinal cord, deep brain, and peripheral nerve stimulation technologies. Technological innovations, better clinical outcomes, higher healthcare spending, favorable reimbursement policies, and greater awareness among patients and physicians further support market growth. Japan’s advanced healthcare infrastructure and research collaborations also accelerate adoption.
Who are the Major Companies in Neurostimulation Devices Industry
Some of the major key players in Neurostimulation Devices are Virtual Medical Centre Inc., Neurosigma, Boston Scientific Corporation, St. Jude Medical Inc. (Abbott), NDI Medical, electroCore LLC, Electro Medics, Endostim Inc., and NeuroPace, Inc.
Key News
- In August 2025, Nalu Medical Inc. introduced a next-generation external Therapy Disc for its micro-implantable peripheral nerve stimulation (PNS) system. The redesigned device is 39% smaller in volume than its predecessor, improving portability and patient comfort while potentially expanding access to PNS therapy.
Market Report Scope
Neurostimulation Devices Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 6.9 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 10.3% | 2033 Value Projection: | USD 14.2 Bn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | Virtual Medical Centre Inc., Neurosigma, Boston Scientific Corporation, St. Jude Medical Inc. (Abbott), NDI Medical, electroCore LLC, Electro Medics, Endostim Inc., and NeuroPace, Inc. | ||
Analyst Opinion
- Neurostimulation is increasingly becoming a treatment decision rather than a last-resort intervention. More than 8 million people worldwide live with Parkinson’s disease, while epilepsy affects around 50 million people globally. In my view, this expanding neurological disease burden is creating a durable clinical need for technologies that can modulate abnormal neural activity when conventional drug therapy provides inadequate control.
- Deep brain stimulation (DBS) has already demonstrated that neurostimulation can deliver clinically meaningful outcomes in complex neurological disorders. Clinical studies have reported motor improvements of roughly 50% or more in appropriately selected Parkinson’s patients following DBS. This established efficacy is one of the strongest arguments for continued physician adoption, particularly as neurologists increasingly seek therapies that provide sustained symptom control beyond medication alone.
- Spinal cord stimulation (SCS) is moving toward more precise, patient-specific therapy, and this is where we see the strongest technological momentum. High-frequency and closed-loop stimulation systems can adjust therapy according to physiological feedback rather than relying entirely on fixed settings. For example, clinical studies of 10-kHz SCS have reported substantial reductions in chronic pain and improvements in quality of life. This shift toward adaptive stimulation should make neurostimulation more clinically attractive and expand its use beyond traditional indications.
- The most important market opportunity is not simply adding more implants—it is improving outcomes through smarter devices. Rechargeable systems, directional leads, wireless programming, sensing capabilities, and AI-assisted optimization are reducing some of the limitations associated with conventional neurostimulators. As these technologies improve precision while simplifying programming and follow-up, We expect clinicians to become more confident in treating patients who previously would have been considered marginal candidates.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- By Device type (Revenue, USD Bn, 2021-2033)
- Deep Brain Stimulators
- Gastric Electric Stimulators
- Sacral Nerve Stimulators
- Vagus Nerve Stimulators
- Spinal Cord Stimulators
- Others
- By Application (Revenue, USD Bn, 2021-2033)
- Parkinson's Disease
- Depression
- Essential Tremor
- Urinary and Fecal Incontinence
- Gastroparesis
- Others
- By End User (Revenue, USD Bn, 2021-2033)
- Hospitals
- Rehabilitation Centers
- Medical Clinics
- By Region (Revenue, USD Bn, 2021-2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Rest of Latin America
- Europe
- Germany
- U.K.
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- South Africa
- Central Africa
- North Africa
- North America
Sources
Primary Research interviews
- Neurologists and neurosurgeons specializing in deep brain stimulation (DBS) and movement disorders
- Pain management specialists and interventional pain physicians
- Neurostimulation device specialists and clinical engineers
- Hospital procurement managers and neuromodulation program directors
- Clinical researchers involved in spinal cord stimulation (SCS), vagus nerve stimulation (VNS), and responsive neurostimulation (RNS)
- Regulatory and reimbursement experts specializing in neurological medical devices
Databases
- U.S. Food and Drug Administration (FDA) medical device databases, including 510(k), PMA, HDE, MAUDE, recalls, and post-approval studies
- ClinicalTrials.gov
- PubMed/MEDLINE
- National Library of Medicine databases
- World Health Organization (WHO) databases
- OECD Health Statistics
- World Bank health and demographic databases
- National Center for Biotechnology Information (NCBI) databases
Magazines
- IEEE Spectrum
- MedTech Dive
- Medical Device Network
- Neurology Today
- ScienceDaily – neuroscience and medical-device coverage
Journals
- Neuromodulation: Technology at the Neural Interface — the official journal of the International Neuromodulation Society and indexed in MEDLINE/PubMed
- Brain Stimulation — covering basic, translational, and clinical research in neuromodulation
- Neurotherapeutics
- Journal of Neurosurgery
- Neurology
- Epilepsia
- Movement Disorders
- Pain
- Journal of Neural Engineering
- Frontiers in Psychiatry – Neurostimulation
Newspapers
- The New York Times
- The Guardian
- The Wall Street Journal
- The Washington Post
- Financial Times
- Nikkei Asia
Associations
- International Neuromodulation Society (INS)
- American Academy of Neurology (AAN)
- American Association of Neurological Surgeons (AANS)
- North American Neuromodulation Society (NANS)
- International Parkinson and Movement Disorder Society (MDS)
- International League Against Epilepsy (ILAE)
- American Society of Pain and Neuroscience (ASPN)
- IEEE Engineering in Medicine and Biology Society (EMBS)
Public Domain sources
- U.S. Food and Drug Administration (FDA) neurological device and medical-device databases
- National Institutes of Health (NIH)
- National Institute of Neurological Disorders and Stroke (NINDS)
- ClinicalTrials.gov
- PubMed/MEDLINE
- Centers for Disease Control and Prevention (CDC)
- World Health Organization (WHO)
- U.S. Census Bureau
- National Center for Health Statistics (NCHS)
- European Medicines Agency (EMA)
- Japan Ministry of Health, Labour and Welfare (MHLW)
- Pharmaceuticals and Medical Devices Agency (PMDA), Japan
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of information for last 10 years
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Neurostimulation Devices Market is anticipated to grow at a CAGR of 10.3% with USD 6.9 Bn in 2026 and is expected to reach USD 14.2 Bn in 2033.
The major categories include deep brain stimulation (DBS), vagus nerve stimulation (VNS), and non-invasive brain stimulation systems such as transcranial magnetic stimulation (TMS).
Chronic pain remains a major application for neurostimulation, particularly through SCS. Neurological disorders such as Parkinson’s disease and epilepsy also provide significant opportunities.
DBS has moved beyond an experimental concept into an established treatment for movement disorders, including Parkinson’s disease, dystonia, and essential tremor.
Neurostimulation provides an alternative for patients whose seizures remain uncontrolled with medication. DBS and RNS use different approaches: DBS continuously stimulates a brain region involved in seizure propagation, whereas RNS monitors brain activity and delivers stimulation when patterns suggest seizure onset.
The strongest technological direction is toward precision and closed-loop stimulation.