
Global Powered Surgical Instruments Market Size and Trends and Forecast 2026 - 2033
Global powered surgical instruments market size is estimated at USD 2.52 Bn in 2026 and is expected to reach USD 3.48 Bn by 2033, exhibiting a compound annual growth rate (CAGR) of 4.7% from 2026 to 2033.
Key Takeaways of the Global Powered Surgical Instruments Market
- In terms of Product Type, Handpiece segment is estimated to hold the largest market share, accounting for 51.6% in 2026.
- Based on Application, Orthopedic segment is estimated to contribute the largest market share of 31.62% in 2026.
- Hospitals segment is estimated to contribute the highest market share of 36.71% in 2026.
- Asia Pacific is expected to lead the global powered surgical instruments market share, accounting for 39.7% in 2026.
Market Overview
Global powered surgical instruments market is expected to witness growth due to increasing number of medical procedures and growing geriatric population. Advancements in medical technologies have led to the development of more advanced powered surgical tools with improved accuracy, efficacy, and efficiency.
Increasing investments by key players to strengthen product portfolios through innovations can fuel the market growth. Rising demand for minimally invasive surgeries and increasing product adoption across emerging nations can offer lucrative opportunities for the market growth.

Market Concentration and Competitive Landscape
The global market for powered surgical instruments is highly consolidated, with several major manufacturers dominating the industry due to their extensive production capacities and global presence.

Current Events and Its Impact
Current Events | Description and its impact |
Escalating Geopolitical Tensions Impacting Global Trade Flows
|
|
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Manufacturing Facilities
- Medtronic possesses state-of-the-art manufacturing facilities predominantly located in the U.S. (Minneapolis), Europe (Ireland and Germany), China, Mexico, and Singapore. Its advanced production lines collectively deliver an annual capacity that exceeds millions of powered surgical units, including electric and pneumatic drills, saws, staplers, and other related surgical instruments.
- Stryker Corporation maintains modern manufacturing plants primarily in Kalamazoo, Michigan (U.S.), Cork, Ireland, Freiburg, Germany, and Suzhou, China. Across these facilities, the company maintains a combined annual production capacity ranging from two million to three million units. It specializes in electric drills, bone saws, surgical staplers, and power-driven orthopedic tools.
Impact of AI on Global Powered Surgical Instruments Market
- The integration of AI into surgical instruments is revolutionizing precision surgery, with robotic systems like Intuitive Surgical's da Vinci platform incorporating machine learning algorithms that can predict optimal incision paths and reduce human error by up to 40%.
- Smart surgical instruments equipped with AI vision systems can now identify tissue types, detect anomalies, and provide haptic feedback to surgeons, as demonstrated by systems that can distinguish between healthy and cancerous tissue with 95% accuracy during tumor removal procedures.
Market Opportunity: Healthcare infrastructure development
Powered surgical instruments have become integral to modern healthcare delivery with advantages of improved precision, reduced procedure time, and safety. Development of stronger healthcare infrastructure provides a massive opportunity to boost adoption of advanced powered surgical instruments.
For instance, the Indian government launched the Ayushman Bharat program with a budget outlay of US$ 6.19 billion until 2025 to set up 1.5 lakh health and wellness centers across the country and provide healthcare access to over 500 million citizens. Under its Healthy China 2030 plan, China has earmarked US$ 1.27 trillion until 2030 to strengthen primary care, reform public health services, and elevate medical standards nationwide.
Segmental Analysis

Powered surgical instruments Insights, by Product Type
In terms of product type, the handpiece segment is estimated to contribute the highest market share of 51.6% in 2026, owing to continual advancements and improvements in handpiece design that increase accuracy, control and ease-of-use for surgeons.
Many new handpieces integrate advanced motion-sensing, vibration dampening and torque feedback mechanisms to allow for higher precision manipulation of surgical tools. Stryker's System 8 Powered Surgical Instruments exemplify this integration of advanced motion-sensing and feedback mechanisms.
Powered surgical instruments Insights by Application
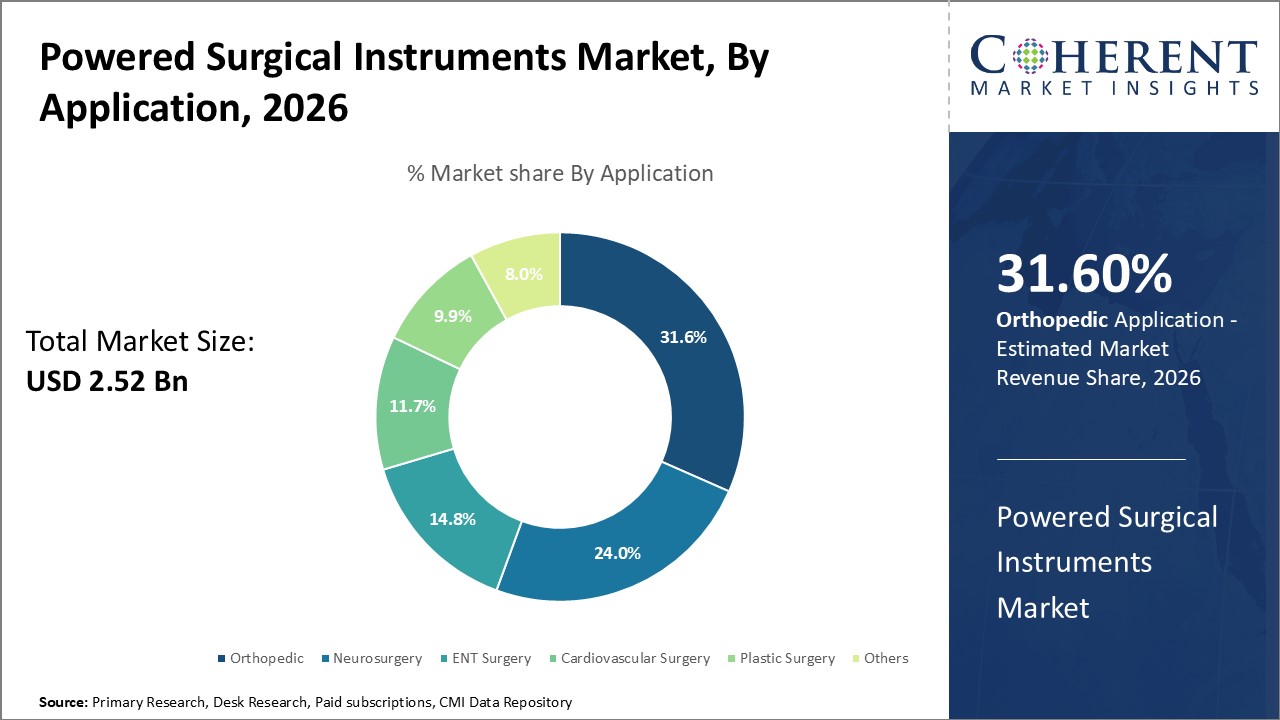
In terms of application, orthopedic segment is estimated to contribute the highest market share of 31.62% in 2026, as rapidly aging global population need joint reconstruction surgeries like hip and knee replacements.
Developments in minimally invasive techniques have also shortened recovery times and decreased patient’s discomfort. The orthopedic segment is primed for further expansion as new materials, implants and surgical robots improve outcomes for a widening range of musculoskeletal issues.
Powered surgical instruments Insights, by End User
In terms of end user, hospitals segment is estimated to contribute the highest market share of 36.71% in 2026, owing to their primacy in major surgical services.
Growing emphasis on preventative healthcare has led to rising rates of lower-risk surgeries being conducted on an outpatient basis within hospital centers rather than in independent clinics. Hospitals additionally benefit from large purchasing agreements that provide discounts on high-ticket capital equipment like powered surgical systems.
Regional Insights

Asia Pacific Powered Surgical Instruments Industry Trends and Market Analysis
Asia Pacific is currently a dominant player in the global powered surgical instruments market, contributing an estimated 39.7% market share in 2026. A burgeoning population, increasing healthcare expenditure, and growing prevalence of chronic diseases requiring surgical interventions are significant contributors to the market expansion in this region.
Additionally, the rise in medical tourism due to the availability of cost-effective and advanced healthcare procedures in countries such as India, Thailand, Singapore, and South Korea is attracting over 2.5 million medical tourists annually who specifically seek minimally invasive procedures using state-of-the-art surgical technology.
Moreover, the region's healthcare infrastructure is quickly developing, with a growing number of hospitals equipped with the latest medical devices, backed by government initiatives and investments in healthcare systems. For instance, China's healthcare infrastructure expansion includes the establishment of over 200 new tertiary hospitals between 2022 and 2024, each requiring comprehensive powered surgical instrument suites, driving market growth of approximately 18% annually in the region.
North America Powered surgical instruments industry trends and market analysis
North America is recognized as the fastest-growing market for powered surgical instruments. This can be attributed to several driving forces, including the region's well-established healthcare infrastructure, high adoption rate of advanced technologies, and strong presence of leading market players who continuously innovate and launch new products.
North America’s focus on patient safety and quality healthcare, along with its strict regulatory environment assuring the availability of quality devices, further prompts manufacturers to develop sophisticated products, making it a rapidly advancing market.
U.S. Powered surgical instruments industry trends and market analysis
The U.S. powered surgical instruments market is growing strongly due to more surgeries, especially minimally invasive ones. Advanced technologies like robotics are boosting precision and efficiency. A strong healthcare system and quick adoption of new tech support this growth. More chronic diseases and an aging population also increase demand for these instruments.
India Powered surgical instruments industry trends and market analysis
The powered surgical instruments market in India is experiencing strong growth. This is driven by increased healthcare investments and a rising number of surgeries performed across the country. There's a growing trend towards minimally invasive and robotic-assisted surgical procedures. These advanced surgeries require sophisticated powered instruments. Government support for local manufacturing is further boosting this expanding market.
India's National Health Mission has allocated a significant amount toward upgrading surgical facilities in tier-2 and tier-3 cities, mandating the procurement of advanced powered surgical instruments including endoscopic systems and orthopedic drilling platforms to meet international surgical standards.
Japan Powered surgical instruments industry trends and market analysis
Japan's aging population has accelerated adoption of powered surgical instruments in minimally invasive procedures, with the market for powered arthroscopic and laparoscopic instruments growing 22% in 2023 as hospitals invest in technology that reduces patient recovery time from 4-6 weeks to 10-14 days.
South Korea Powered surgical instruments industry trends and market analysis
South Korea's medical device manufacturing sector has emerged as a regional hub, with companies like Meditech producing locally-manufactured powered surgical handpieces that cost 30-40% less than Western alternatives while meeting international quality standards, making advanced surgical technology more accessible across Southeast Asian markets.
Market Report Scope
Powered Surgical Instruments Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 2.52 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 4.7% | 2033 Value Projection: | USD 3.48 Bn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | Stryker Corporation, Medtronic PLC , Johnson & Johnson, CONMED Corporation , Zimmer Biomet Holdings, Inc., B. Braun Melsungen AG, Smith & Nephew PLC, MicroAire Surgical Instruments, Desoutter Medical Ltd, Pro-Dex Inc., Alcon Laboratories Inc., Black & Black Surgical, De Soutter Medical, Allotech Co., Ltd., Nouvag AG, W&H Dentalwerk International, Thompson Surgical Instruments, Brasseler USA | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Global Powered Surgical Instruments Industry News
- On April 16, 2025, ZEISS India introduced its latest innovations, including the ZEISS ARTEVO 850 and 750 ophthalmic microscopes, the AT ELANA 841P trifocal Intraocular Lens (IOL), and the ZEISS CIRRUS Pathfinder AI-powered surgical planning support tool.
- In March 2025, Olympus announced the launch of its first AI-powered clinical decision tool through a partnership with Ziosoft. The initial applications focus on liver, lung, and kidney procedures, utilizing AI to transform 2D CT/MRI images into 3D models for enhanced surgical planning and precision.
- In March 2025, India’s Zydus Lifesciences announced strategic acquisition of 85.6% stake in France-based medical devices manufacturer, Amplitude Surgical, for €256.8 million (approximately US$ 280 million).
- In April 2024, Proprio, a leader in AI-powered surgical technology, announced a significant multi-phase partnership with the Biedermann Group, a company known for its cutting-edge spinal implant systems and procedural solutions. The initial phase of partnership will focus on integrating Biedermann's advanced spinal implants with Proprio's Paradigm system. This system utilizes AI, computer vision, and augmented reality to offer surgeons real-time visualization and guidance during surgical procedures.
Analyst View
- The powered surgical instruments sector is currently experiencing a dramatic technological bifurcation that will leave many established players struggling to remain relevant. Medtronic's clear failure to deliver promised software updates for their StealthStation integration has created a significant opportunity for competitors.
- Boston Scientific's launch of instruments with 68% recycled components isn't just environmentally responsible - it's strategically brilliant. With 76% of hospital procurement departments now factoring sustainability metrics into purchasing decisions, this approach creates meaningful differentiation beyond mere technical specifications.
- Global supply chain vulnerabilities remain a significant challenge for major players. ConMed's 16-day production interruption due to semiconductor shortages exemplifies the risk. Market participants without diversified component sourcing strategies are facing greater challenge, especially as 84% of specialized microcontroller units used in these instruments still originate from just three manufacturing facilities globally.
- High costs associated with powered instruments can hamper the market growth, especially in price-sensitive developing regions.
- New product launches with innovative features can offer opportunities for market players. Adoption of powered instruments in ambulatory surgery centers and office-based surgeries can also offer market growth opportunities.
Market Segmentation
- By Product Type (Revenue, USD Bn, 2021 - 2033)
- Handpiece
- Drill System
- Saw System
- Staplers
- Shaver's
- Others
- Power Source & Control
- Battery Power Instruments
- Electric Instruments
- Pneumatic Instruments
- Accessories
- Surgical Accessories
- Electrical Accessories
- Handpiece
- By Application (Revenue, USD Bn, 2021 - 2033)
- Orthopedic
- Neurosurgery
- ENT Surgery
- Cardiovascular Surgery
- Plastic Surgery
- Others
- By End User (Revenue, USD Bn, 2021 - 2033)
- Hospitals
- Specialty Clinics
- Ambulatory Surgery Centers
- Academic & Research Institutes
- Regional Insights (Revenue, USD Bn, 2021 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC Countries
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
- North America
- Company Profiles
- Stryker Corporation
- Medtronic PLC
- Johnson & Johnson
- CONMED Corporation
- Zimmer Biomet Holdings, Inc.
- Braun Melsungen AG
- Smith & Nephew PLC
- MicroAire Surgical Instruments
- Desoutter Medical Ltd
- Pro-Dex Inc.
- Alcon Laboratories Inc.
- Black & Black Surgical
- De Soutter Medical
- Allotech Co., Ltd.
- Nouvag AG
- W&H Dentalwerk International
- Thompson Surgical Instruments
- Brasseler USA
Sources
Stakeholders:
- Senior Executives from Leading Medical Device Manufacturers
- Doctors and Surgeons Specializing in Orthopaedic and Neurosurgeries
- Procurement Managers from Hospital Chains
- Key Distributors and Channel Partners
- Others
Databases:
- World Health Organization (WHO) Database
- Centers for Disease Control and Prevention (CDC) Database
- Others
Magazines:
- Medical Device & Diagnostic Industry Magazine (MDDI)
- Surgical Products Magazine
- Healthcare Technology Management (HTM) Magazine
- Others
Journals:
- Journal of Surgical Research
- International Journal of Surgery
- Journal of Medical Devices
- Others
Newspapers:
- The Wall Street Journal
- Medical News Today
- Healthcare Business News
- Others
Associations:
- American College of Surgeons (ACS)
- Association of Surgical Technologists (AST)
- Advanced Medical Technology Association (AdvaMed)
- European Surgical Association (ESA)
- Others
Public Domain Sources:
- U.S. Food and Drug Administration (FDA)
- European Medicines Agency (EMA)
- National Institutes of Health (NIH)
- Others
*Definition: Global Powered Surgical Instruments Market consists of the manufacturing, distribution, and sales of powered surgical instruments used in various surgical procedures across the world. Powered surgical instruments operate on battery power or are plugged into an electrical outlet and include powered drills, saws, resection devices and other instruments used for orthopedic, neurology, ENT, dental and other surgical procedures. The growing demand for minimally invasive surgeries and the increasing rate of target surgeries globally is expected to drive the growth of the global powered surgical instruments market in the coming years.
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The powered surgical instruments market is estimated to be valued at USD 2.52 Bn in 2026, and is expected to reach USD 3.48 Bn by 2033.
The CAGR of the powered surgical instruments market is projected to be 4.7% from 2026 to 2033.
Rising prevalence of chronic diseases and advancements in minimal access surgery are the major factors driving the demand for powered surgical instruments.
High cost of powered instruments and lack of proper sterilization are the major factors hampering the growth of the global powered surgical instruments market.
In terms of product type, the handpiece segment is estimated to dominate the market in 2026.
Stryker Corporation, Medtronic PLC, Johnson & Johnson, CONMED Corporation , Zimmer Biomet Holdings, Inc., B. Braun Melsungen AG, Smith & Nephew PLC, MicroAire Surgical Instruments, Desoutter Medical Ltd, Pro-Dex Inc., Alcon Laboratories Inc., Black & Black Surgical, De Soutter Medical, Allotech Co., Ltd., Nouvag AG, W&H Dentalwerk International, Thompson Surgical Instruments, and Brasseler USA are the major players.
Asia Pacific is expected to lead the global powered surgical instruments market.