

Diabetic Kidney Disease Market Size and Forecast — 2026-2033
Global diabetic kidney disease market is estimated to be valued at USD 3.35 Bn in 2026 and is expected to reach USD 4.77 Bn by 2033, exhibiting a compound annual growth rate (CAGR) of 5.2% from 2026 to 2033.
 Increasing prevalence of diabetes across the globe is primarily driving the market growth. According to the International Diabetes Federation 2021 Report, approximately 537 million people lived with diabetes in 2021 worldwide and this number is expected to rise to 643 million by 2030 and 783 million by 2045. The market is witnessing significant growth due to rising awareness regarding diabetic kidney disease and availability of various treatment options. Furthermore, developments in areas such as diagnostic tools, drugs, and renal replacement therapies are helping patients in early detection and effective management of the disease. However, high cost of treatment devices and lack of awareness in low-income countries can hamper the market growth during the forecast period.
Rising prevalence of diabetes
Increasing prevalence of diabetes across the globe is primarily driving the market growth. Diabetes has become one of the leading causes of end-stage kidney disease due to both microvascular and macrovascular complications impacting the kidneys over the long run. As more people are diagnosed with diabetes every year due to changing lifestyle habits and lack of physical activity, the risk of developing diabetic kidney disease also increases proportionately. Early detection and treatment can help slow the progression but healthcare systems need to be better prepared to handle this growing caseload.
Insights, By Drug Class
 Insights, By Drug Class: High efficacy and lesser side effects drives angiotensin receptor blockers (ARBs) segment growth
Drug Class segment is sub-segmented into angiotensin receptor blockers (ARBs), calcium channel blockers, antioxidant inflammation modulator, angiotensin-converting enzyme (ACE) inhibitors, and others. Angiotensin Receptor Blockers (ARBs) segment is estimated to hold 35.4% share of the market in 2026. ARBs are generally well-tolerated with lesser side effects as compared to other counterparts like ACE inhibitors, which positively impacts treatment compliance. These demonstrate renal protection benefits by inhibiting actions of angiotensin II receptor and reducing proteinuria, a major risk factor for progression of kidney disease. ARBs also present cardiovascular risk reduction in diabetics by controlling blood pressure and fluid overload more efficiently. Being a once daily oral dosage form, ARBs provide convenience to patients as compared to other frequent dosing options. The availability of affordable generic versions of ARBs allows wider access and adoption rates among diabetes patients with renal complications worldwide.
Insights, By Route of Administration
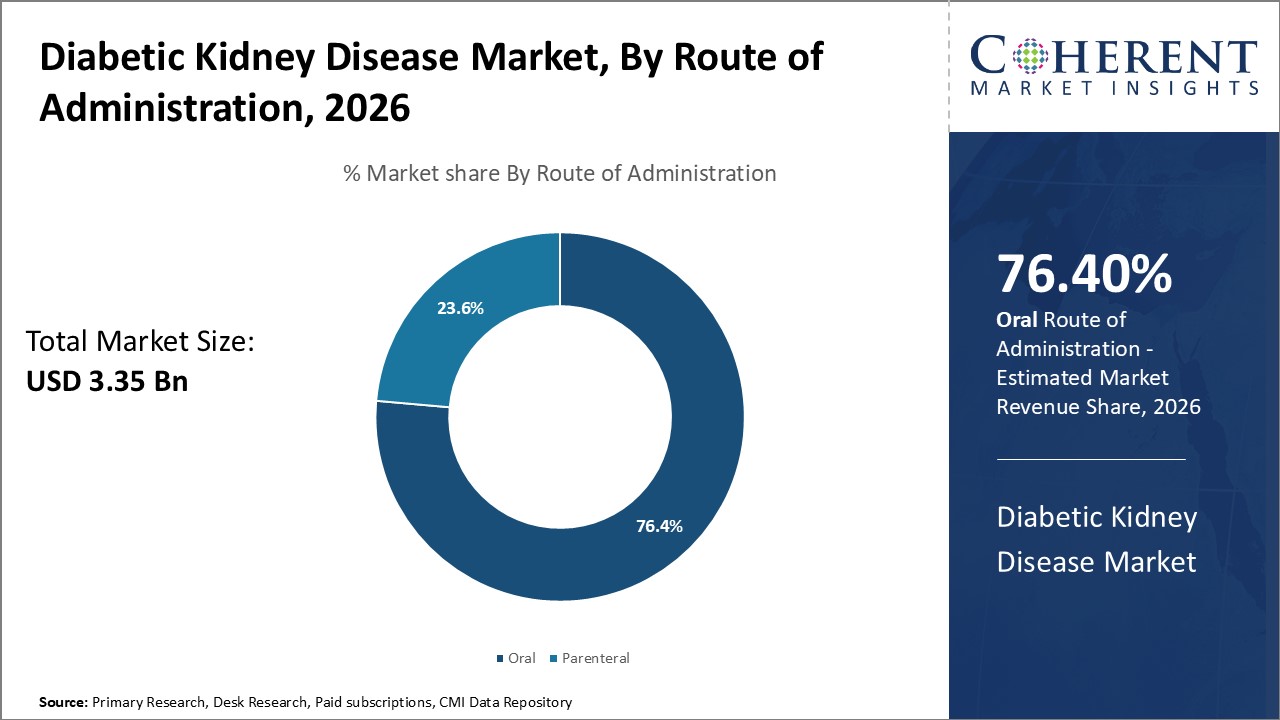
Insights, By Route of Administration: Ease of administration drives oral segment growth
Route of Administration segment is sub-segmented into oral and parenteral. Oral segment is expected to hold 76.4% of the market share in 2026. Oral route enables self-administration of medications without any medical supervision or professional assistance. This promotes better compliance to treatment among kidney disease patients with diabetes. Being a chronic disease, oral administration eases lifelong therapy related challenges. It also avoids risks of complications from injections or intravenous therapies. Their stability at room temperature also facilitates storage and logistics with reduced cold chain requirements compared to parenteral products.
Insights, By Distribution Channel
Insights, By Distribution Channel: Ease of access drives retail pharmacies growth
Distribution Channel segment is sub-segmented into hospital pharmacies, retail pharmacies, and online pharmacies. Retail pharmacies segment is expected to hold 43.4% of the market share in 2026. Retail pharmacies are in close proximity across urban, semi-urban and even rural locations, allowing patients to conveniently purchase medications near their homes or workplaces. This eases fulfillment of frequent prescription refills while managing chronic kidney diseases arised due to diabetes. Being a one-stop shop for all healthcare and nutrition needs, retail outlets promote medication adherence through continued customers' visits.
Regional Insights
 North America region has been dominating the global diabetic kidney disease market over the years and is projected to hold 38.7% of the market share in 2026. The U.S. accounts for the largest share primarily due to t rising prevalence of diabetes as well as better access to healthcare and advanced treatment options in the country. The economic ability and healthcare infrastructure in the region allow for large investments in R&D which has led to the development of innovative drugs and new treatment modalities. Most of the leading pharmaceutical players have their headquarters in the U.S. and focus on drug innovation for diabetic kidney disease. This has ensured early availability and adoption of new treatment options.
The Asia Pacific region has emerged as the fastest growing market for diabetic kidney disease treatment globally. Countries like China, India and Japan are experiencing rapid economic development and growth of medical infrastructure. While Asia has a lower rate of diagnosed cases currently due to lack of screening, the prevalence of diabetes is rising sharply due to expanding urbanization and lifestyle changes. Asia Pacific accounted for over 60.5% of the world's diabetic population in 2019. Rising awareness, screening programs and availability of affordable generic drugs are driving the market growth. Governments are also investing in initiatives to expand health insurance coverage thus, driving the market growth.
Market Players, Key Development, and Competitive Intelligence
 Ageing population
With improved medical care and living standards, people around the world are living longer. Longer life expectancy means the proportion of elderly population is increasing exponentially in many countries. Age is a significant risk factor for developing chronic kidney diseases including those resulting from diabetes. Older patients typically have longstanding diabetes which increases their vulnerability to kidney damage over the decades. Managing kidney health of the geriatric group is an ongoing challenge. As life expectancy increases globally, more people will live with diabetes into their old age, thus, making them prone to age-related complications like diabetic kidney disease. Healthcare systems need to gear up for the rising healthcare needs of the growing elderly diabetic population at risk of associated co-morbidities.
Key Developments
- On March 05, 2024, Novo Nordisk, a multinational pharmaceutical company announced the results from the kidney outcomes trial FLOW. The double-blind trial compared injectable semaglutide 1.0 mg with placebo as an adjunct to standard of care for prevention of progression of kidney impairment and risk of kidney and cardiovascular mortality in people with type 2 diabetes and chronic kidney disease (CKD). In the trial, semaglutide 1.0 mg appeared to have a safe and well-tolerated profile in line with previous semaglutide 1.0 mg trials.
- In February 2023, The European Commission approved a label extension for Kerendia (finerenone) in the European Union (EU) that includes cardiovascular (CV) outcomes from the Phase III FIGARO-DKD research. The study found that Kerendia lowered the risk of cardiovascular events in a large sample of patients with CKD stages 1-4 and T2D. Kerendia is currently recommended for the treatment of chronic kidney disease (albuminuria) in individuals with type 2 diabetes.
- In January 2023, Boehringer Ingelheim, a pharmaceutical company, and Eli Lilly and Company, a pharmaceutical company, announced that the U.S. Food and Drug Administration (FDA) had accepted a supplemental New Drug Application (sNDA) for Jardiance (empagliflozin) tablets, which are being investigated as a potential treatment to reduce the risk of kidney disease progression and cardiovascular death in adults with chronic kidney disease (CKD)
- In April 2021, AstraZeneca, a global pharmaceutical company, announced that Farxiga (dapagliflozin), a sodium-glucose cotransporter 2 (SGLT2) inhibitor, had been approved in the U.S. by FDA to reduce the risk of sustained estimated glomerular filtration rate (eGFR) decline, end-stage kidney disease (ESKD), cardiovascular (CV) death, and heart failure hospitalization (hHF) in adults with CKD at risk of progression
*Definition: Diabetic Kidney Disease Market covers products and services used in the diagnosis and treatment of kidney disease caused by diabetes. This includes drugs for slowing the progression of kidney damage such as ACE inhibitors and SGLT2 inhibitors. It also involves products for renal replacement therapy like dialysis machines, dialyzers, vascular access products and consumables. The market covers equipment and technologies used for kidney biopsy, diagnostic tests to check kidney function and stage of disease.
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Market Report Scope
Diabetic Kidney Disease Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 3.35 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 5.2% | 2033 Value Projection: | USD 4.77 Bn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | AstraZeneca, Boehringer Ingelheim, Janssen Pharmaceuticals, Bristol Myers Squibb, GSK, Novo Nordisk, Eli Lilly and Company, Merck & Co., Sanofi, AbbVie, Sun Pharmaceutical Industries Ltd, Teva Pharmaceutical Industries Ltd, Lupin, Aurobindo Pharma, Takeda Pharmaceutical Company Limited, Biogen, Vertex Pharmaceuticals Incorporated | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Analyst Opinion (Expert Opinion)
 Market Challenges – Lack of awareness about the disease among general population
One of the major challenges faced by the diabetic kidney disease market is lack of awareness about the disease among general population as well as physicians. Late diagnosis results in poor treatment outcomes. Affordability of existing treatment options is another barrier as drugs and dialysis are very costly. Rising healthcare costs can limit access to care for underprivileged patients.
Market Opportunities – Increasing diabetic patient pool driven by sedentary lifestyles
Increasing diabetic patient pool driven by sedentary lifestyles and obesity pandemic creates lucrative opportunities for market development over the forecasted period. More focus on early screening programs can help detect kidney disease beforehand. Novel drug delivery methods and new molecular entities in development promise better efficacy and convenience. Growth in healthcare investment and spending across regions like Asia Pacific and Latin America will boost the scope for affordable therapies.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- Drug Class Insights (Revenue, USD BN, 2021 - 2033)
- Angiotensin Receptor Blockers (ARBs)
- Calcium Channel Blockers
- Antioxidant Inflammation Modulator
- Angiotensin-Converting Enzyme (ACE) Inhibitors
- Others
- Route of Administration Insights (Revenue, USD BN, 2021 - 2033)
- Oral
- Parenteral
- Distribution Channel Insights (Revenue, USD BN, 2021 - 2033)
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Regional Insights (Revenue, USD BN, 2021 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
- North America
- Key Players Insights
- AstraZeneca
- Boehringer Ingelheim
- Janssen Pharmaceuticals
- Bristol Myers Squibb
- GSK
- Novo Nordisk
- Eli Lilly and Company
- Merck & Co.
- Sanofi
- AbbVie
- Sun Pharmaceutical Industries Ltd
- Teva Pharmaceutical Industries Ltd
- Lupin
- Aurobindo Pharma
- Takeda Pharmaceutical Company Limited
- Biogen
- Vertex Pharmaceuticals Incorporated
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Diabetic Kidney Disease Market is estimated to be valued at USD 3.35 Bn in 2026, and is expected to reach USD 4.77 Bn by 2033.
The CAGR of the Diabetic Kidney Disease Market is projected to be 5.2% from 2026 to 2033.
Rising prevalence of diabetes and ageing population are the major factor driving the growth of global diabetic kidney disease market.
Lack of awareness about the disease among general population and alternative treatment methods are the major factor hampering the growth of global diabetic kidney disease market.
In terms of drug class, angiotensin receptor blockers (ARBs) segment is estimated to dominate the market in 2026.
AstraZeneca, Boehringer Ingelheim, Janssen Pharmaceuticals, Bristol Myers Squibb, GSK, Novo Nordisk, Eli Lilly and Company, Merck & Co., Sanofi, AbbVie, Sun Pharmaceutical Industries Ltd, Teva Pharmaceutical Industries Ltd, Lupin, Aurobindo Pharma, Takeda Pharmaceutical Company Limited, Biogen, Vertex Pharmaceuticals Incorporated are the major players.
North America is expected to lead the global diabetic kidney disease market.