

GLP-1 Receptor Agonist Market Size and Trends Forecast: 2026 - 2033
GLP-1 receptor agonist market is estimated to be valued at USD 31.71 Bn in 2026 and is expected to reach USD 72.33 Bn by 2033, exhibiting a compound annual growth rate (CAGR) of 12.5% from 2026 to 2033.
Key Takeaways of the GLP-1 Receptor Agonist Market
- Based on drug class, the liraglutide segment is projected to dominate, holding a share of 26.5% in 2026.
- Based on route of administration, the parenteral segment is projected to dominate in 2026.
- Based on application, the type 2 diabetes mellitus segment is projected to dominate in 2026.
- North America is expected to dominate the GLP-1 receptor agonist market, accounting for 40.7% of the market share in 2026.
Market Overview
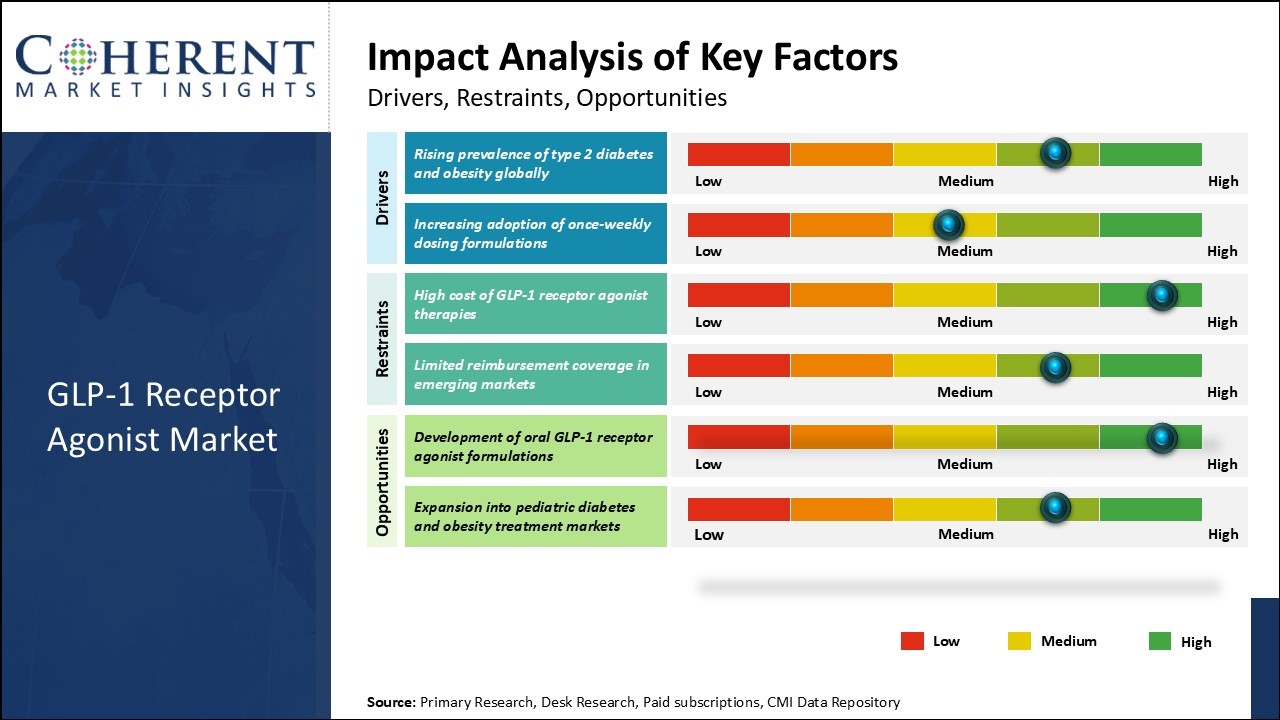
The market growth can be attributed to factors such as rising prevalence of type 2 diabetes and obesity across countries. Global GLP-1 receptor agonist market is expected to witness lucrative growth over the forecast period as increasing number of patients are opting for GLP-1 drugs due to their greater efficacy and lesser side effects compared to conventional diabetes medications. Furthermore, rising launch of novel formulations such as long-acting therapies with dosing convenience can drive the market growth.
However, the high development cost of GLP-1 drugs can hamper the global GLP-1 receptor agonist market growth.
Market Concentration and Competitive Landscape

Current Events and Their Impact on the GLP-1 Receptor Agonist Market
Current Events | Description and its impact |
U.S. FDA and Regulatory Expansion Initiatives |
|
Global Supply Chain and Manufacturing Disruptions |
|
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Market Trends
Rising Prevalence of Type 2 Diabetes and Obesity Globally
The world is witnessing an alarming surge in the prevalence of type 2 diabetes and obesity, which is a major catalyst for the rapid expansion of the GLP‑1 receptor agonist market. Type 2 diabetes—marked by insulin resistance and disrupted glucose metabolism—poses one of the most pressing public health challenges. GLP‑1 receptor agonists offer a therapeutic breakthrough by mimicking the glucagon‑like peptide‑1 hormone, boosting insulin secretion and suppressing glucagon release, thereby enhancing glycemic control.
For instance, according to the latest International Diabetes Federation (IDF) Diabetes Atlas (2025), approximately 11.1% of adults aged 20–79 years—about 1 in 9 people—are living with diabetes globally, and more than 4 in 10 of those individuals remain undiagnosed.
Segmental Insights
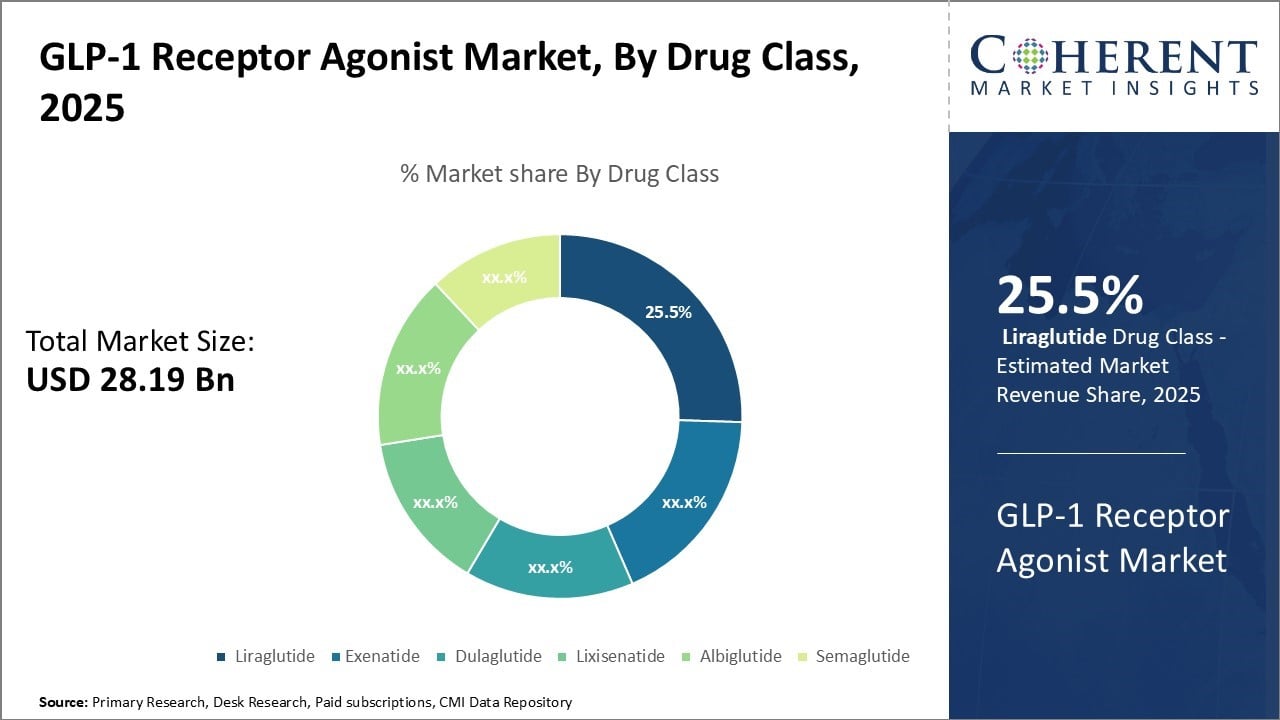
GLP-1 Receptor Agonist Market Insights, By Drug Class: Liraglutide Contributes the Highest Share of the Market Owing to its Effectiveness and Superior Efficacy
In terms of drug type, liraglutide is expected to contribute 26.5% share of the market in 2026, as its once-daily subcutaneous administration provides consistent glycemic control throughout the day.
Clinical trials have demonstrated Liraglutide's ability to lower HbA1c levels by up to 25.5% on an average, with weight loss of 2-3 kg observed as an added benefit. The drug also helps reduce cardiovascular risks in Type 2 diabetes patients. These therapeutic advantages have led to increasing prescriptions by clinicians for glycemic management.

GLP-1 Receptor Agonist Market Insights, By Route of Administration: Parenteral Contributes the Highest Share of the Market Due to its Convenience
By route of administration, the parenteral segment is estimated to contribute the highest market share owing to its unparalleled convenience. While oral formulations offer non-invasive dosing, their low bioavailability and potential gastrointestinal side effects have remained major limitations.
Injectable GLP-1 receptor agonists provide predictable absorption of the active drug directly into systemic circulation, resulting in consistent glucose-lowering activity. Prefilled multi-dose pens and autoinjector devices have further elevated the ease of self-administration via the subcutaneous route. This improved convenience has led to greater patient acceptance and better treatment compliance compared to other complex anti-diabetes regimens.
GLP-1 Receptor Agonist Market Insights, By Application: Type 2 Diabetes Mellitus Contributes the Highest Share of the Market Due to Increased Efficacy in Disease Management
By application, type 2 diabetes mellitus segment is estimated to contribute the highest market share of, due to their augmented effectiveness in diabetes care. These drugs aid glycemic control through multiple mechanisms like enhancing insulin secretion, suppressing glucagon levels, and reducing appetite to induce weight loss.
Studies have shown that GLP-1 receptor agonists provide better glycemic control and lower the risks of hypoglycemia compared to other anti-diabetes medications. Weight reduction achieved through these agents facilitates management of other diabetes co-morbidities and reduces cardiovascular complications. Furthermore, GLP-1 receptor agonists allow greater treatment customization based on individual patient's disease progression and therapeutic response.
Emerging Innovations in the GLP-1 Receptor Agonist Market
- Diversification of Indications
- GLP-1 RAs are now widely used for type 2 diabetes and increasingly for chronic weight management; cardiovascular and renal benefits observed in trials have broadened clinician interest. Shift toward non-daily dosing and non-injectable routes: weekly injectables, oral tablets and pipeline transdermal/patch approaches are reducing treatment burden.
- Convergence with Combination Biology
- Dual and multi-agonist molecules combining GLP-1 activity with GIP and/or glucagon receptor activity are emerging and driving superior metabolic efficacy in clinical studies. Improved patient experience and adherence tools: smarter injection devices, connected apps, and adherence support are being paired with therapies to improve long-term outcomes.
Regional Insights
North America GLP-1 Receptor Agonist Market Analysis and Trends
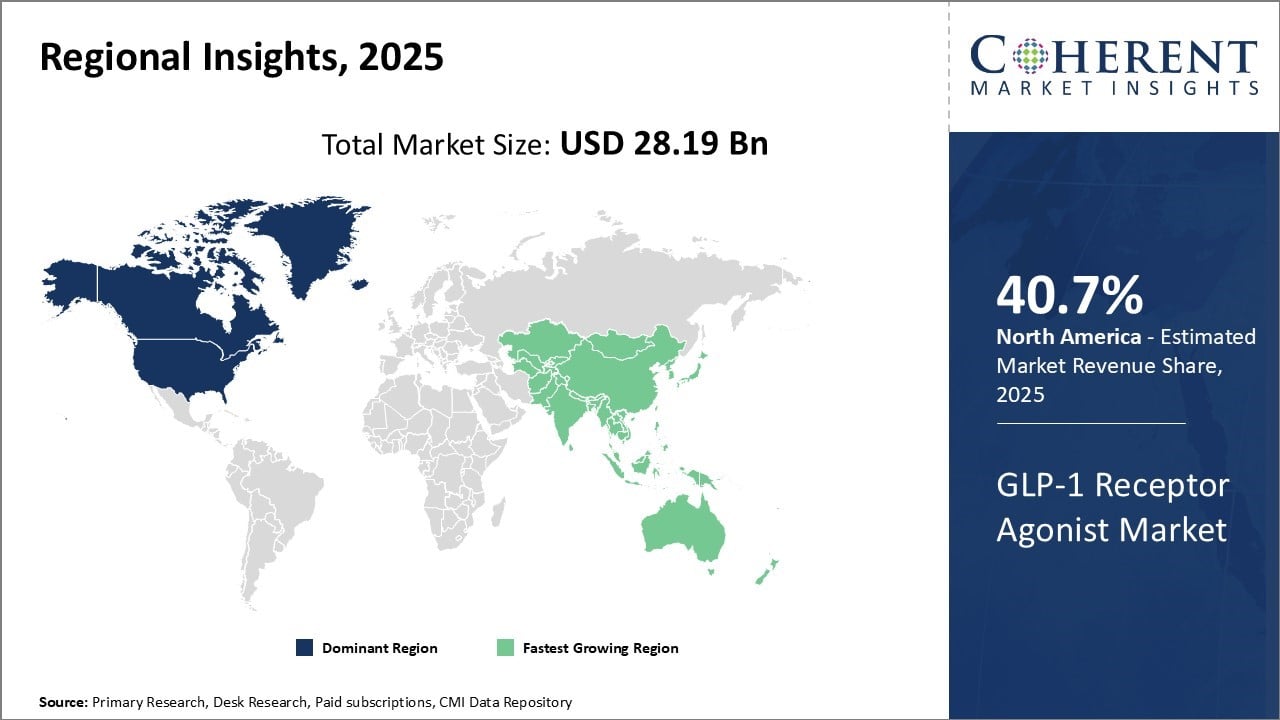
North America dominates the global GLP-1 receptor agonist market over with an estimated market share of 40.7% in 2026. The region has a highly developed healthcare infrastructure and availability of advanced treatment options. Healthcare expenditure is also higher in the U.S. and Canada compared to other parts of the world, enabling more patients to access costly drugs such as GLP-1 receptor agonists.
For instance, a specific RAND survey isn't publicly validated, but a 2024 poll by the American Medical Association estimates that about 16% of U.S. adults—roughly 1 in 8—have used GLP‑1 medications such as Ozempic or Wegovy.
Asia Pacific GLP-1 Receptor Agonist Market Analysis and Trends
Asia Pacific is poised to register the fastest growth in the global GLP-1 receptor agonist market during the forecast period. Rapid economic development, rising healthcare expenditure, growing diabetes epidemic and increasing focus of international players on emerging Asian markets can drive the market growth.
For instance, according to the International Diabetes Federation Diabetes Atlas (2021 edition), China and India were estimated to have 140.9 million and 74.2 million adults with diabetes in 2021, and these numbers are projected to increase to 174.4 million and 124.9 million, respectively, by 2045.
GLP-1 Receptor Agonist Market Outlook for Key Countries
U.S. GLP-1 Receptor Agonist Market Analysis and Trends
The U.S. stands as the foremost national market for GLP‑1 receptor agonists, fueled by its sophisticated healthcare infrastructure, effective reimbursement mechanisms, and aggressive public awareness campaigns. Direct-to-consumer advertising has elevated patient demand, while robust clinical and prescribing ecosystems make the U.S. the global engine of GLP‑1 adoption.
China GLP-1 Receptor Agonist Market Analysis and Trends
China represents a major emerging market, driven by an increasing diabetes burden, expanding healthcare access, and supportive government initiatives. Major drug manufacturers have actively engaged with local partners, establishing production and distribution channels tailored to the country’s needs.
India GLP-1 Receptor Agonist Market Analysis and Trends
India’s market for GLP‑1 receptor agonists is gaining significant momentum, driven by unmet clinical demand, rising awareness, and a steadily expanding healthcare ecosystem. The introduction of generics, such as Glenmark’s liraglutide biosimilar launched at dramatically lower prices, reflects the push toward affordability and broader access in a cost-conscious market.
Japan GLP-1 Receptor Agonist Market Analysis and Trends
Japan remains a key regional player, distinguished by its strong healthcare infrastructure and universal insurance coverage. Key GLP‑1 therapies are integrated into national insurance schemes, and the country’s aging population underscores its strategic importance in diabetes and obesity management.
Market Report Scope
GLP-1 Receptor Agonist Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 31.71 Bn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 12.5% | 2033 Value Projection: | USD 72.33 Bn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | Eli Lilly and Company, Sanofi, Novo Nordisk A/S, AstraZeneca, Perrigo Company PLC, 3M Company, Bausch Health, Taro Pharmaceutical Industries, Novan Inc., Serum Institute of India Pvt. Ltd., Orgenesis biotech company, Verrica Pharmaceuticals, AbbVie Inc., Lee's Pharmaceutical Holdings Ltd, and Cassiopea, and Glenmark Pharmaceuticals | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
GLP-1 Receptor Agonist Industry News
- In July 2025, PolyPid Ltd. ("PolyPid" or the "Company"), unveiled its long-acting GLP-1 receptor agonists (glucagon-like peptide-1 RA) delivery platform which aims to subcutaneously release GLP-1 RA for approximately 60 days, significantly longer than current weekly injection regimens.
- In May 2025, Septerna, Inc. and Novo Nordisk collaborated and agreed for a license agreement to discover, develop and commercialize oral small molecule medicines for obesity, type 2 diabetes and other cardiometabolic diseases.
- In May 2025, Illumina, Inc., and Ovation.io, Inc., announced the development of the largest commercially available clinical multiomic dataset from 25,000 patients treated with glucagon-like peptide-1 (GLP-1) receptor agonist therapies. This collaboration is the latest in a series of efforts to partner across the ecosystem, and deploy multimodal data to advance a deeper understanding of biology.
- In April 2025, Pfizer Inc. announced the decision to discontinue the development of danuglipron (PF-06882961), an oral glucagon-like peptide-1 (GLP-1) receptor agonist, which was being investigated for chronic weight management.
- In February 2025, Gan & Lee Pharmaceuticals (hereafter referred to as "Gan & Lee," stock code: 603087.SH) unveiled that the first participant was successfully dosed in a large-scale Phase 3 clinical trial (OPTIMUM-2) of Bofanglutide, a bi-weekly glucagon-like peptide-1 receptor agonist (GLP-1RA) independently, in Chinese participant with type 2 diabetes mellitus (T2DM). This milestone marks the initiation of the first Phase 3 clinical trial of Bofanglutide injection worldwide for the treatment of T2DM.
Analyst View
- The GLP-1 receptor agonist market represents one of the most dynamic therapeutic segments in modern healthcare, driven by the escalating global diabetes epidemic and rising obesity prevalence. These innovative biologics have revolutionized diabetes management by offering superior glycemic control alongside significant weight loss benefits, positioning them as preferred treatment options over traditional therapies.
- The recent U.S. FDA approvals for obesity indications have substantially expanded the addressable patient population beyond diabetes, creating unprecedented commercial opportunities.
- However, significant restraints persist, particularly the premium pricing of these therapies and limited insurance coverage in emerging markets, which restricts patient access. Manufacturing complexity and cold-chain storage requirements present additional operational challenges for market penetration.
- North America dominates the market landscape, supported by favorable reimbursement policies, advanced healthcare infrastructure, and high treatment adoption rates. However, Asia-Pacific emerges as the fastest-growing region, fueled by rapidly increasing diabetes prevalence, expanding middle-class populations, and improving healthcare access in countries like China and India.
- The competitive landscape intensifies as pharmaceutical giants invest heavily in next-generation GLP-1 analogs with improved efficacy profiles. Strategic partnerships between established players and regional distributors will likely accelerate global market penetration.
Market Segmentation
- Drug Class Insights (Revenue, USD Bn, 2021 - 2033)
- Exenatide
- Liraglutide
- Dulaglutide
- Lixisenatide
- Albiglutide
- Semaglutide
- Route of Administration Insights (Revenue, USD Bn, 2021 - 2033)
- Parenteral
- Oral
- Application Insights (Revenue, USD Bn, 2021 - 2033)
- Type 2 Diabetes Mellitus
- Obesity
- Liver Cirrhosis
- Non-alcoholic Steatohepatitis
- Others
- Distribution Channel Insights (Revenue, USD Bn, 2021 - 2033)
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Regional Insights (Revenue, USD Bn, 2021 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC Countries
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
- Key Players Insights
- Eli Lilly and Company
- Sanofi
- Novo Nordisk A/S
- AstraZeneca
- Perrigo Company PLC
- 3M Company
- Bausch Health
- Taro Pharmaceutical Industries
- Novan Inc.
- Serum Institute of India Pvt. Ltd.
- Orgenesis biotech company
- Verrica Pharmaceuticals
- AbbVie Inc.
- Lee's Pharmaceutical Holdings Ltd.
- Cassiopea
- Glenmark Pharmaceuticals
Sources
Primary Research Interviews
- Pharmaceutical manufacturers and drug developers
- Healthcare providers and endocrinologists
- Regulatory affairs specialists
- Pharmaceutical distributors and retailers
- Others
Magazines
- Pharmaceutical Executive
- BioPharma Dive
- Diabetes Care Magazine
- Drug Discovery & Development
- Others
Journals
- Pharmaceutical Executive
- BioPharma Dive
- Diabetes Care Magazine
- Drug Discovery & Development
- Others
Newspapers
- Financial Times
- The Wall Street Journal
- Reuters Health News
- Bloomberg Healthcare
- Others
Associations
- American Diabetes Association (ADA)
- European Association for the Study of Diabetes (EASD)
- International Diabetes Federation (IDF)
- Pharmaceutical Research and Manufacturers of America (PhRMA)
- Others
Public Domain Sources
- World Health Organization (WHO) publications
- Centers for Disease Control and Prevention (CDC) reports
- European Medicines Agency (EMA) publications
- National Institute of Diabetes and Digestive and Kidney Diseases (NIDDK)
- Others
Proprietary Elements
- CMI Data Analytics Tool – GLP-1 Receptor Agonist Market
- CMI Existing Repository of Information for the Last 8 Years
*Definition: Global GLP-1 receptor agonist market involves pharmaceutical products that mimic the effects of naturally occurring glucagon-like peptide-1 (GLP-1). GLP-1 receptor agonists work by stimulating the release of insulin from the pancreas in a glucose-dependent manner. These are used as treatment options for type 2 diabetes by helping to control blood sugar levels. These have also been shown to promote weight loss in overweight/obese individuals with diabetes. The market includes drugs like exenatide, liraglutide, semaglutide, lixisenatide, and albiglutide.
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The GLP-1 receptor agonist market is estimated to be valued at USD 31.71 Bn in 2026, and is expected to reach USD 72.33 Bn by 2033.
The CAGR of the GLP-1 receptor agonist market is projected to be 12.5% from 2026 to 2033.
Rising prevalence of diabetes and growing popularity of once-weekly dosing GLP-1 RA drugs are the major factors driving the growth of global GLP-1 receptor agonist market.
High development cost of GLP-1 drugs and stringent regulatory requirements are the major factors hampering the growth of the global GLP-1 receptor agonist market.
In terms of drug class, the liraglutide segment is estimated to dominate the market in 2026.
Eli Lilly and Company, Sanofi, Novo Nordisk A/S, AstraZeneca, Perrigo Company PLC, 3M Company, Bausch Health, Taro Pharmaceutical Industries, Novan Inc., Serum Institute of India Pvt. Ltd., Orgenesis biotech company, Verrica Pharmaceuticals, AbbVie Inc., Lee's Pharmaceutical Holdings Ltd, Cassiopea, and Glenmark Pharmaceuticals are the major players operating in the market.
North America is expected to lead the GLP-1 receptor agonist market in 2026.