

Stomach Cancer Drugs Market Size and Trends - 2026 to 2033
The Stomach Cancer Drugs Market is estimated to be valued at USD 5,600 Mn in 2026 and is expected to reach USD 9,100 Mn by 2033, growing at a compound annual growth The rate (CAGR) of 7.2% from 2026 to 2033.
Key Takeaways
- Based on Therapy Type, the Kinase Inhibitors segment is expected to lead the market with 19.20% share in 2026, due to its precision oncology adoption.
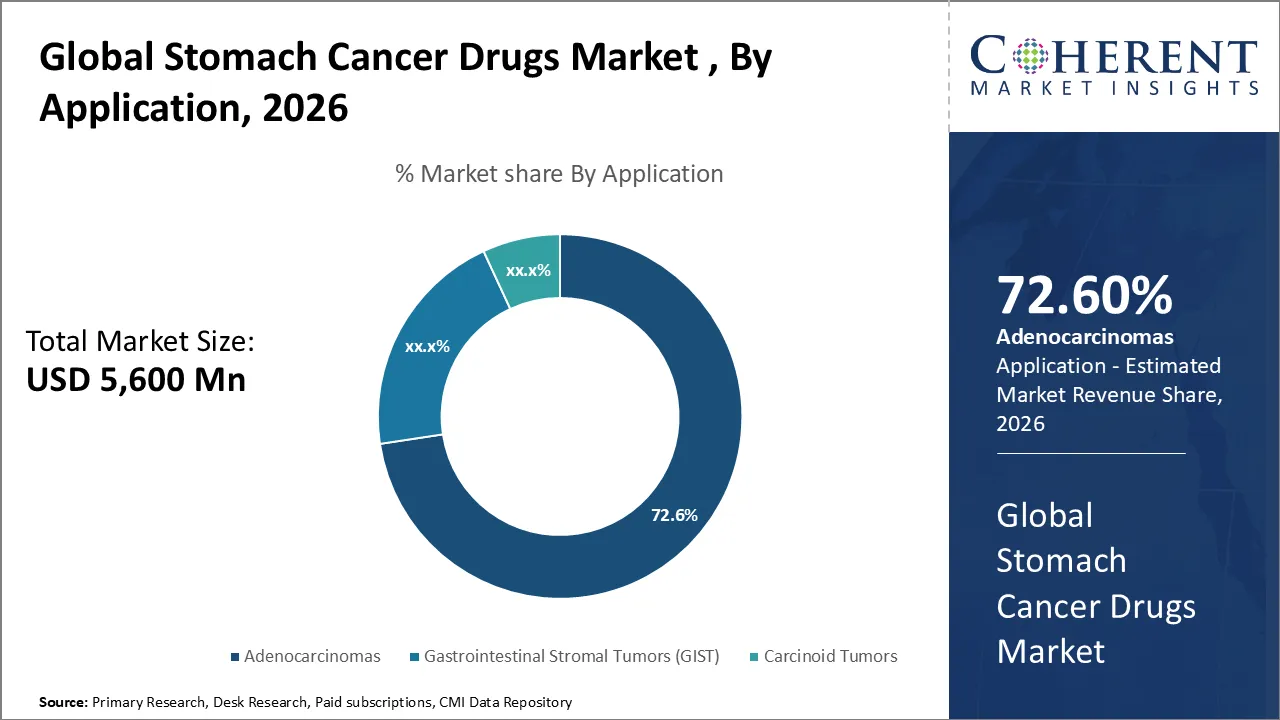
- Based on Application, the Adenocarcinoma segment is expected to hold 72.60% share of the market in 2026 driven by its high prevalence among stomach cancer cases.
- Based on Distribution Channel, Hospital Pharmacy segment is expected to hold 47.30% share of the market in 2026 supported by inpatient infusion therapies and specialist dispensing.
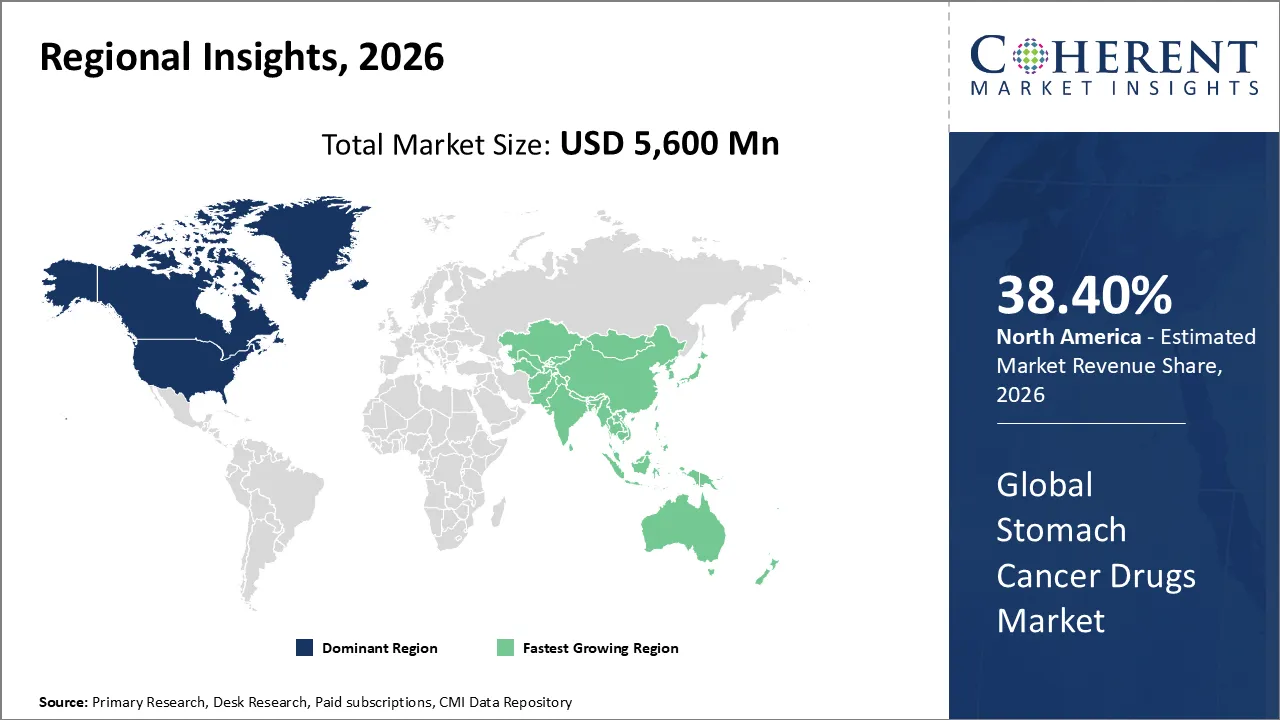
- Based on Region, North America is set to lead the market with 38.40% share in 2026. While, Asia Pacific is anticipated to be the fastest growing region.
Market Overview
The Stomach Cancer Drugs Market is advancing significantly as it transitions from traditional chemotherapy to highly specialized targeted therapies and immunotherapies. This pharmaceutical sector is driven by its critical role in addressing the global incidence of gastric malignancies through the commercialization of precision medicines like HER2 antagonists and PD-1 inhibitors. The increasing demand for personalized treatment plans and the expansion of early screening programs are expected to drive market growth over the forecast period.
These therapeutic agents deliver concentrated and often molecularly targeted solutions to the tumor site, allowing clinicians to distinguish between various genetic expressions with a superior role in efficacy and patient survival. These drugs are crucial in contemporary cancer treatment, particularly in gastrointestinal medicine and surgical oncology, as they can prolong survival and minimize the overall side effects associated with traditional therapies.
The ongoing innovation in antibody drug conjugates and integrated companion diagnostics is reshaping the oncology industry. The demand for flexible and high-performance drug regimens is increasing across hospitals and specialized cancer centers. These advancements have broadened the functional scope of cancer care by improving tumor reduction and ensuring compatibility with emerging biomarkers like Claudin 18.2. The top players operating in the industry are forming strategic acquisitions and launching biologics and biosimilars designed mainly for streamlined clinical workflows and personalized medicine interventions.
Current Events and Its Impacts on the Stomach Cancer Drugs Market
Current Event | Description and the Impact |
Advances in Medical Research and Technology
|
|
Regional Epidemiological Trends and Public Health Initiatives |
|
Segmental Insights
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Stomach Cancer Drugs Market Insights, By Application – Adenocarcinomas Leads with its High Prevalence Among Stomach Cancer Cases
In terms of application, the adenocarcinomas segment contributes the highest share of 72.60% in the market in 2026. The segment comprises the vast majority of gastric cancer cases diagnosed globally. Because this histological subtype originates in the glandular cells of the stomach lining, it serves as the primary target for drug development and regulatory approvals. The increasing prevalence of this condition ensures that it remains the focal point for large-scale clinical trials and pharmaceutical R&D. The demand in this segment is consistently owing to high global incidence rates and the continuous introduction of specialized immunotherapies and targeted agents specifically optimized for adenocarcinoma pathology.
For instance, in November 2022, Merck announced encouraging topline results from the pivotal Phase 3 KEYNOTE-859 trial. This study evaluated the effectiveness of Merck's anti-PD-1 therapy, KEYTRUDA, used alongside chemotherapy as a first-line treatment for patients with locally advanced, metastatic, or unresectable gastric or gastroesophageal junction (GEJ) adenocarcinoma that is HER2-negative.
Stomach Cancer Drugs Market Insights, By Therapy Type – Kinase Inhibitors Leads Due to its Precision Oncology Adoption
In terms of therapy type, the kinase inhibitors segment contributes the highest share of 19.20% in 2026 of the market. This is owing to the ongoing shift toward molecularly targeted therapies. These agents are preferred for their capacity to selectively disrupt signaling pathways such as HER2 and VEGFR2 which play a pivotal role in tumor cell proliferation. In contrast to traditional cytotoxic treatments, they produce a more targeted therapeutic effect by blocking vital enzymes that fuel cancer. A strong clinical pipeline of small molecule inhibitors coupled with the expanded use of companion diagnostics to identify responsive patients are propelling the segment’s growth.
Stomach Cancer Drugs Market Insights By, Distribution Channel – Hospital Pharmacy Leads Due to Inpatient Infusion Therapies
In terms of distribution channel, hospital pharmacy segment contributes the highest share of 47.30% in 2026 of the market due to the clinical complexity of oncology treatment. The administration of most advanced therapies, such as complex biologics and intravenous chemotherapies, is dependent on clinical supervision due to their complexity and potential risks. These settings serve as the essential hub for managing these high-cost, temperature-sensitive medications and ensuring patient safety during infusion procedures. In addition, the centralized nature of hospital-based cancer care facilitates integrated treatment planning and the immediate management of potential adverse reactions, cementing the hospital pharmacy’s leading position.
For instance, in July 2025, Bayer Vietnam and PTHo Chi Minh City Oncology Hospital have signed a Memorandum of Understanding (MoU) to work together to improve cancer care in Vietnam, with a special emphasis on gastrointestinal cancers.
Regional Insights
North America Stomach Cancer Drugs Market Analysis & Trends
North America has remained the dominant region with 38.40% in 2026 of the global Stomach Cancer Drugs Market over the past decade. The robust healthcare systems and sustained research and development funding are the main contributors to the growth in the region. As a result, the region demonstrates early adoption of biologics and immunotherapy-based treatments. In addition, widespread access to genomic profiling and biomarker testing allows for a precision medicine approach, thus ensuring that high-value treatments are utilized effectively. The strong support from both private and public reimbursement systems facilitates access to these expensive medical regimens. The presence of major pharmaceutical headquarters and a dense network of clinical trial sites are also propelling the region's leading position in the global industry.
For instance, in July 2025, Adcentrx Therapeutics made an announcement that ADRX-0405 has received orphan drug designation from the U.S. Food and Drug Administration (FDA) for the treatment of gastric cancer.
Asia Pacific Stomach Cancer Drugs Market Analysis & Trends
The Asia Pacific region market is growing at a fast rate due to widespread disease prevalence and increased availability of medical services. The region accounts for the majority of global stomach cancer cases, particularly in populations affected by aging demographics and diet-related risks. The immense patient need has resulted in a surge in diagnostic screening programs, which in turn increases the volume of patients requiring patient therapy. The governments across the region are implementing healthcare reforms to lower the cost of treatment, thereby encouraging the use of biosimilars and locally manufactured generics. In addition, strong clinical trial infrastructure and favorable regulatory conditions have established the region as a global clinical research hub. These factors significantly shorten development timelines and speed the commercialization of oncology breakthroughs.
For instance, in March 2025, AstraZeneca and Daiichi Sankyo are continuing to gain patient support with their leading antibody-drug conjugate, Enhertu, following a Phase III readout that indicates the drug's significant potential in gastric cancer.
Stomach Cancer Drugs Market Outlook Country-Wise
The US Stomach Cancer Drugs Market Trends
The US remains a central hub for stomach care drug innovation, emphasizing a shift toward highly specialized targeted therapies. Although gastric cancer incidence is comparatively lower than in other regions, the market is distinguished by exceptionally high per-patient treatment expenditure. This financial footprint is owing to the rapid adoption of breakthrough biologics such as HER2 targeted agents and PD L1 inhibitors, which have redefined the standard of care. A sophisticated regulatory landscape coupled with intensive R&D activity from major pharmaceutical players is speeding up the progression of successful clinical trials into commercial-stage therapies. In addition, comprehensive insurance coverage for molecular profiling allows physicians to prescribe personalized treatment plans. This position the country as a high-value leader in the ecology sector.
For instance, in February 2025, Hanmi Pharmaceutical has highlighted the novel potential of its selective oral CCR4 antagonist, Tivumecirnon, which is a new treatment for gastric cancer, in combination with the anti-PD-1 therapy KEYTRUDA® (pembrolizumab). A Phase 1/2 study in partnership with MSD and RAPT Therapeutics, a US-based company, led to this advancement.
China Stomach Cancer Drugs Market Trends
China continues to drive market growth with its vast patent population and proactive public sector support. In response to its significant gastric cancer burden, national health initiatives have prioritized early detection and broader drug accessibility. The market is undergoing structural change due to the National Reimbursement Drug List (NRDL) and centralized procurement initiatives, which have substantially lowered the cost of innovative immunotherapies and chemotherapies, improving nationwide accessibility. This surge in volume is complemented by a booming domestic biotech sector that is producing cost-effective biosimilars and novel inhibitors. Consequently, the combination of increased healthcare spending and a streamlined approval process is transforming China into a global focal point for large-scale clinical application.
For instance, in January 2025, Astellas Pharma Inc. announced that VYLOYTM (zolbetuximab) has received approval from China's National Medical Products Administration (NMPA) for use as a first-line treatment for patients with locally advanced, metastatic, or unresectable HER2-negative gastric or gastroesophageal junction (GEJ) adenocarcinomas that are claudin (CLDN) 18.2 positive.
Market Report Scope
Stomach Cancer Drugs Market Report Coverage
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year: | 2025 | Market Size in 2026: | USD 5,600 Mn |
| Historical Data for: | 2020 To 2024 | Forecast Period: | 2026 To 2033 |
| Forecast Period 2026 to 2033 CAGR: | 7.2% | 2033 Value Projection: | USD 9,100 Mn |
| Geographies covered: |
| ||
| Segments covered: |
| ||
| Companies covered: | Pfizer Inc., Eli Lilly and Company, GlaxoSmithKline Plc., Kuhnil Pharmaceutical Co. Ltd., Daiichi Sankyo Co. Ltd., Merck KGaA, AstraZeneca Plc, Otsuka Holdings Co. Ltd., Sanofi S.A., and F. Hoffmann-La Roche Ltd, Ono Pharmaceutical Co. Ltd., Bristol-Myers Squibb (BMS), Jiangsu HengRui Medicine Co. Ltd., Gilead Science Inc., Celgene Corporation, Taiho Pharmaceutical, Boston Biomedical Inc., and Merck & Co. | ||
| Growth Drivers: |
| ||
| Restraints & Challenges: |
| ||
Stomach Cancer Drugs Market Drivers
Increasing incidence of stomach cancer
The global stomach cancer drug market is evolving in response to the rising disease incidence and the increasing adoption of advanced therapies. The expansion is due to the aging population, the high prevalence of chronic infections like H. pylori, and lifestyle risks such as high-sodium diets and smoking. The industry is moving away from conventional chemotherapy toward personalized treatment strategies in response to the growing disease burden. The market is now driven by the increasing adoption of immunotherapies and targeted biologics that address genetic markers, including HER2 and Claudin 18.2. The improvements in diagnostic technologies and molecular profiling are allowing for earlier disease detection, thereby increasing the number of patients eligible for these high-value, sophisticated therapies. All these factors together are fostering continual market growth.
Increasing FDA approvals of biosimilars for treatment of stomach cancer
The stomach cancer drugs market revenue is anticipated to grow due to the increasing number of FDA approvals for biosimilars. The adoption of biosimilars has surged in the past five years, primarily because they are priced lower than biologic treatments for stomach cancer. Additionally, reimbursement policies for stomach cancer medications significantly contribute to the market's growth. Both government and private healthcare plans cover the costs of stomach cancer drugs, which further enhances the adoption of these treatments.
Analyst Opinion (Expert Opinion)
The stomach cancer drugs market is undergoing a notable transformation, supported by rising disease prevalence, improved diagnostic accuracy, and the increasing integration of advanced therapeutic modalities. Gastric cancer remains among the leading causes of cancer-related mortality worldwide, with incidence rates particularly high across East Asia, Eastern Europe, and parts of Latin America. This epidemiological burden continues to drive sustained demand for effective pharmacological interventions.
Treatment paradigms are progressively shifting away from conventional chemotherapy toward targeted therapies and immunotherapies. Agents targeting HER2, VEGF, and PD-1/PD-L1 pathways are increasingly incorporated into standard treatment regimens, supported by clinical evidence demonstrating improved progression-free survival in biomarker-defined patient populations. Clinical trial activity remains robust, with a significant proportion of ongoing studies focused on combination therapies aimed at enhancing response durability and overcoming resistance mechanisms.
Regionally, Asia Pacific represents the largest contributor to treatment demand, reflecting both higher incidence rates and expanding access to oncology care. North America and Europe continue to benefit from early adoption of novel therapies, strong regulatory pipelines, and established reimbursement frameworks. Meanwhile, emerging markets are witnessing gradual uptake as healthcare infrastructure and oncology awareness improve.
Overall, the market outlook is characterized by innovation-led growth, increasing emphasis on personalized medicine, and intensifying competition driven by new product approvals and pipeline advancements.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Stomach Cancer Drugs Industry News
- In January 2026, Cancer Research UK and Stand Up To Cancer® (SU2C) have announced new funding for a team focused on preventing stomach cancer in its early stages.
- In October 2024, Roche announced that the VENTANAⓇ CLDN18 (43-14A) RxDx Assay is the first FDA-approved immunohistochemistry (IHC) companion diagnostic in the US.
- In October 2024, Takeda announced that it, along with Innovent Biologics, has signed a licensing and collaboration agreement for the research, production, and global distribution of two late-stage cancer medications, IBI363 and IBI343, outside of Greater China. IBI343 is under evaluation for pancreatic and stomach cancers.
- In September 2021, Curing Stomach Cancer (DDF) and the American Association for Cancer Research (AACR) are working together to advance and improve research in the field of gastric cancer through a USD 200,000 research grant.
Market Segmentation
- Therapy Type Insights (Revenue, USD Mn, 2026 - 2033)
- Kinase Inhibitors
- Nucleoside Metabolic Inhibitors
- Anthracyclines
- VEGF Antibodies
- HER2 Receptor Antagonists
- Car T Cell Therapy Trastuzumab
- Trastuzumab
- Application Insights (Revenue, USD Mn, 2026 - 2033)
- Adenocarcinomas
- Gastrointestinal Stromal Tumors
- Carcinoid Tumors
- Distribution Channel Insights (Revenue, USD Mn, 2026 - 2033)
- Endoscopic Surgery
- Surgical Suite
- Dental Surgery
- Others
- Regional Insights (Revenue, USD Mn, 2026 - 2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- U.K.
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- North Africa
- Central Africa
- South Africa
- Key Players Insights
- Pfizer Inc.
- Eli Lilly and Company
- GlaxoSmithKline Plc.
- Kuhnil Pharmaceutical Co. Ltd.
- Daiichi Sankyo Co. Ltd.
- Merck KGaA
- AstraZeneca Plc.
- Otsuka Holdings Co. Ltd.
- Sanofi S.A.
- F. Hoffmann-La Roche Ltd.
- Ono Pharmaceutical Co. Ltd.
- Bristol-Myers Squibb (BMS)
- Jiangsu HengRui Medicine Co. Ltd.
- Gilead Science Inc.
- Celgene Corporation
- Taiho Pharmaceutical
- Boston Biomedical Inc.
- Merck & Co.
Sources
Primary Research Interviews
- Oncologists & Gastroenterologists
- Medical Oncologists Specializing in Gastrointestinal Cancers
- Oncology Drug Manufacturers
- Biopharmaceutical R&D Executives
- Hospital Pharmacy & Procurement Heads
- Clinical Trial Investigators
- Key Opinion Leaders (KOLs) in Oncology
- Others
Databases
- Bloomberg Terminal
- IQVIA MIDAS & Pharmetrics
- Clarivate Cortellis
- EvaluatePharma
- GlobalData Pharma Intelligence
- S&P Global Market Intelligence
- Others
Magazines
- Oncology Times
- Cancer Therapy Advisor
- Pharmaceutical Executive
- BioPharma Dive
- Nature Reviews Drug Discovery (Magazine Section)
- Others
Journals
- The Lancet Oncology
- Journal of Clinical Oncology (JCO)
- Gastric Cancer Journal
- Annals of Oncology
- European Journal of Cancer
- Others
Newspapers
- The Wall Street Journal
- Financial Times
- Reuters
- Bloomberg News
- The New York Times – Health Section
- Others
Associations
- American Society of Clinical Oncology (ASCO)
- European Society for Medical Oncology (ESMO)
- World Gastroenterology Organisation (WGO)
- International Gastric Cancer Association (IGCA)
- Union for International Cancer Control (UICC)
- Others
Public Domain Sources
- World Health Organization (WHO) – Cancer Program
- National Cancer Institute (NCI)
- U.S. Food & Drug Administration (FDA) – Oncology Drug Approvals
- European Medicines Agency (EMA)
- ClinicalTrials.gov
- GLOBOCAN (IARC)
- Others
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of Oncology & Pharmaceutical Market Intelligence (Last 8+ Years)
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The Stomach Cancer Drugs Market is estimated to be valued at USD 5,600 Mn in 2026, and is expected to reach USD 9,100 Mn by 2033.
The CAGR of the Stomach Cancer Drugs Market is projected to be 7.2% from 2026 to 2033.
Increasing FDA approvals of biosimilars for the treatment of stomach cancer is one of the major factors driving the growth of the Stomach Cancer Drugs Market.
Serious side effects associated with the drugs such as nausea and vomiting, loss of appetite and weight loss, fatigue, and diarrhea, among others is one of the major factors hampering the growth of the Stomach Cancer Drugs Market.
In terms of therapy type, the kinase inhibitors segment is estimated to dominate the market revenue share in 2026.
Pfizer Inc., Eli Lilly and Company, GlaxoSmithKline Plc., Kuhnil Pharmaceutical Co. Ltd., Daiichi Sankyo Co. Ltd., Merck KGaA, AstraZeneca Plc, Otsuka Holdings Co. Ltd., Sanofi S.A., and F. Hoffmann-La Roche Ltd, Ono Pharmaceutical Co. Ltd., Bristol-Myers Squibb (BMS), Jiangsu HengRui Medicine Co. Ltd., Gilead Science Inc., Celgene Corporation, Taiho Pharmaceutical, Boston Biomedical Inc., and Merck & Co. are the major players.
North America is expected to lead the Stomach Cancer Drugs Market in 2026.