
Thrust Vector Control System Market Size and Share Analysis- Growth Trends and Forecasts (2026–2033)
The global Thrust Vector Control System Market size is estimated to reach USD 12.50 Bn by 2033, growing at a CAGR of 4.3% from USD 9.28 Bn in 2026. The key drivers for growth include the rising demand for advanced missile guidance systems, increasing adoption of thrust vectoring technologies in military aircraft, growing investments for space exploration programs and growing commercial satellite launch activities. According to the Federal Aviation Administration (FAA) reported the United States had 204 licensed commercial space operations in FY 2025, an increase of nearly 38% from FY 2024.
Key Takeaways
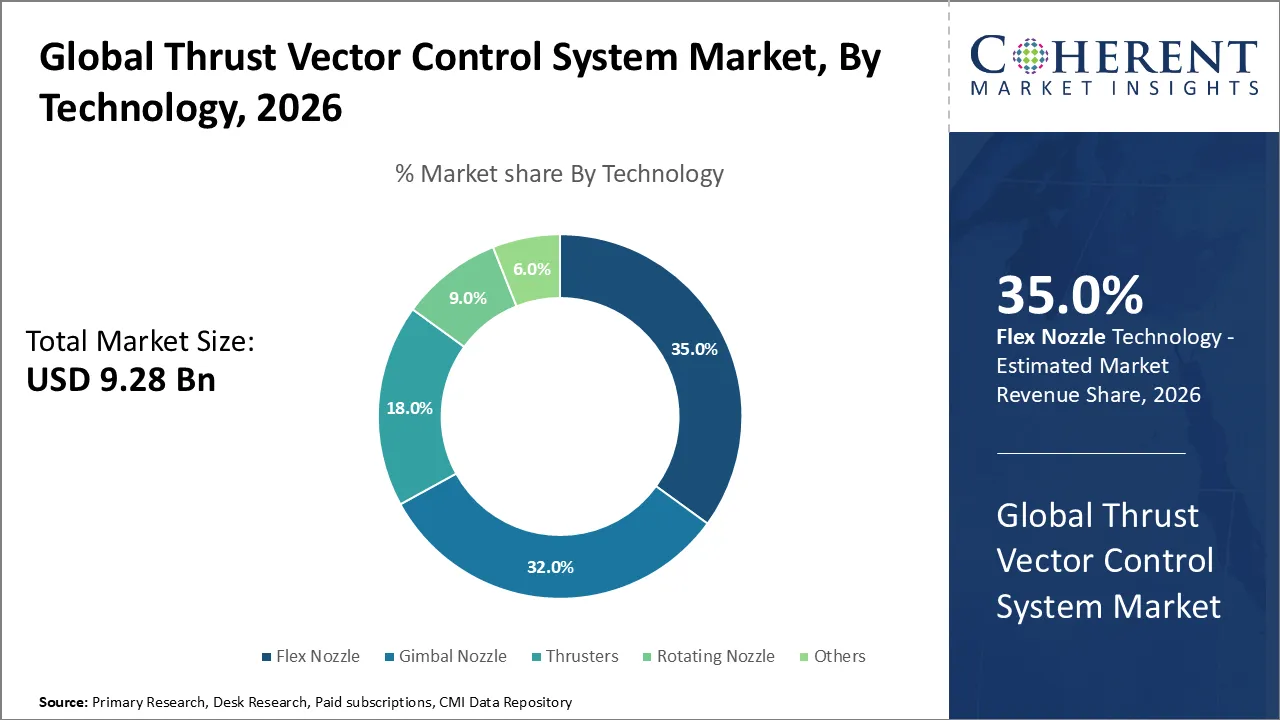
- The Flex Nozzle segment is projected to lead the market with an estimated share of 35.0% in 2026. The growth of this segment is attributed to the ability of the segment to provide accurate control over the thrust direction, support vehicle maneuverability and meet the stringent aerospace propulsion demands. According to NASA, each Space Launch System (SLS) solid rocket booster creates about 3.6 million pounds of thrust and an integrated thrust vector control system directs the nozzle in flight.
- The Missiles segment is expected to dominate the market with an estimated 38.0% share in 2026. Growth is supported by increasing defense modernization spending, demand for precision-guided missiles and development of advanced missile maneuvering capabilities. In September 2026, the U.S. Army announced that Lockheed Martin had been awarded a contract worth as much as USD 1.2 Bn to produce Precision Strike Missile Increment 2, a sign of continued investment in next-gen missile technologies.
- The Thrust Vector Actuation System segment is expected to dominate with a valuation of 52.0% in 2026. The growth is propelled by demand for accurate propulsion control, electromechanical actuators and advanced guidance technologies in missiles and launch vehicles. According to Moog, Moog’s thrust vector control technologies guided NASA’s Artemis II Space Launch System stages during its April 2026 mission, highlighting the importance of advanced actuation systems in space launch operations.
- The Defense segment is anticipated to grab largest market share of around 65.0% in 2026. The segment is being driven by increased procurement of advanced missile systems, modernization of military aircraft and investment in precision propulsion technologies. The U.S. Department of Defense also said plans to raise the U.S. homeland missile defense interceptor fleet to 64 interceptors, including 44 Ground-Based Interceptors and 20 Next Generation Interceptors, potentially by the end of the decade, were part of the FY 2026 budget request.
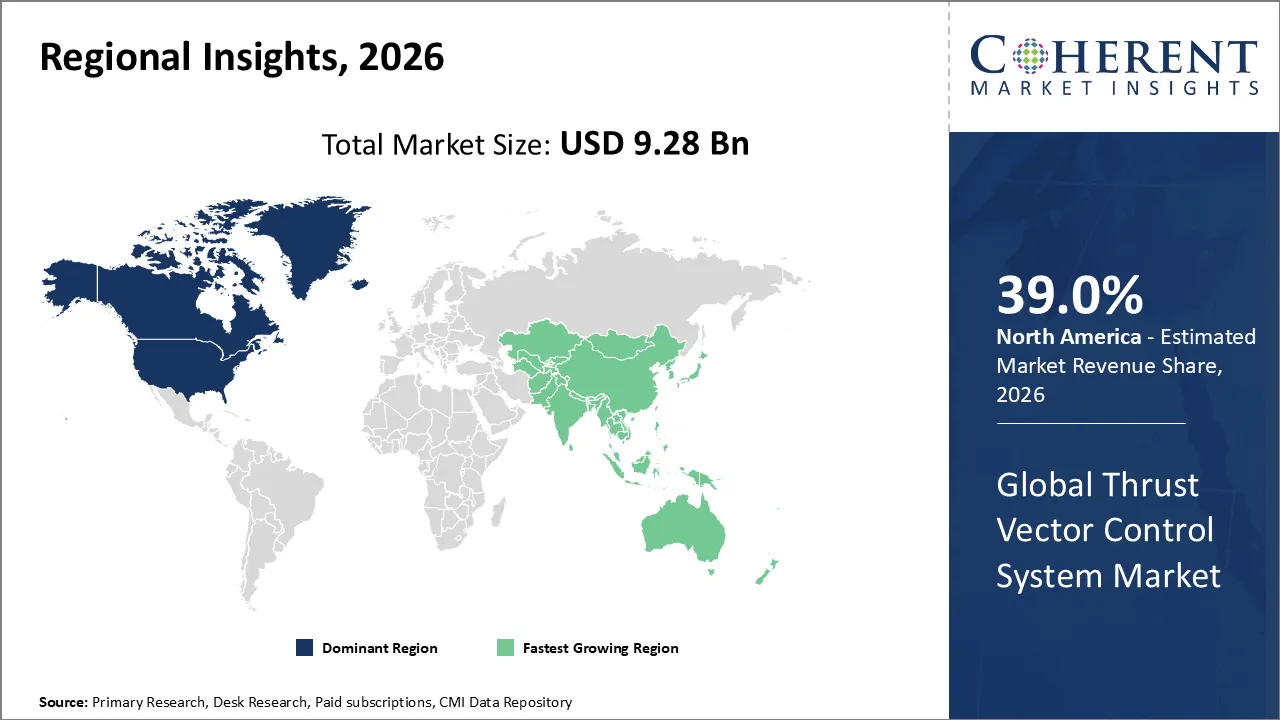
- North America is expected to dominate the market with a share of 39.0% in 2026. Regional growth is supported by established aerospace and defense manufacturers, enhanced propulsion research and growing commercial space launch activities. Florida’s Eastern Range hosted a record 109 space launches in 2025, demonstrating the growing launch infrastructure in the area and the associated demand for propulsion and flight-control technologies, according to the U.S. Space Force.
Market Drivers
Increasing Investments in Space Exploration and Commercial Launch Programs are Driving the Thrust Vector Control System Market
The global market for Thrust Vector Control Systems is expected to grow at a steady pace. The market is driven by growing investments in space exploration, growing commercial launch activities and growing demand for advanced propulsion technologies. The need for reliable thrust vector control systems is driven by the rise of reusable launch vehicles, satellite constellations and next generation rockets. These systems allow precise trajectory corrections, vehicle stabilization and improved maneuvering capabilities during launch operations.
In November 2025, ESA’s member states endorsed €22.3 billion in contributions, a record amount and a 31% nominal increase on the funding commitments made at the previous ministers’ meeting in 2022. These investments support European space exploration, transportation infrastructure and technology development programs, providing opportunities for advanced propulsion and launch vehicle control technologies.
In July 2026, the U.S. government awarded contract modifications under the National Security Space Launch (NSSL) Phase 3 Lane 1 program, increasing the total ceiling value of contracts by USD 11.4 billion among participating launch service providers. NASA also added Relativity Space's Terran R and Blue Origin's New Glenn 9x4 to its Launch Services II contracting framework in September 2026.
Rising Development of Advanced Missile Systems and Hypersonic Weapons is Accelerating Market Growth
The global Thrust Vector Control System Market is fueled by the rising defense spending and the development of advanced missile technologies. s. Defense organizations are investing in precision-guided missiles, advanced interceptor systems and maneuverable hypersonic weapons to enhance military capabilities. Thrust vector control technologies are of special importance for powered flight applications which necessitate rapid direction changes, better control over trajectory and high precision maneuverability.
According to the U.S. Congressional Research Service, the Department of Defense requested about USD 13.4 billion in FY 2026 for procurement and research, development, testing, and evaluation of hypersonic warfare programs related to offensive and defensive capabilities. These investments reflect a growing emphasis on advanced missile technologies and propulsion control capabilities, and provide opportunities for thrust vector control system manufacturers.
Current Events and Their Impact on the Thrust Vector Control System Market
Current Event | Description and its Impact |
U.S. Federal Aviation Administration Introduces Commercial Space Launch Licensing Reforms (October 2026) |
|
U.S. Government Introduces National Space Transportation Policy to Strengthen Launch Infrastructure (August 2026) |
|
- Current Industry Events of 2026
- Market Size Estimation
- Regional Breakdown
- Competitive Landscape
- Customer Intelligence
- Segmental Analysis
- Pricing Analysis
- Key Market Drivers, Challenges & Future Trends
- Customized Insights Section
Segmental Insights
Why is the Flex Nozzle Segment Acquiring the Largest Market Share?
On the basis of technology, the Flex Nozzle segment is projected to account for the largest Thrust Vector Control System Market share of 35.0% in 2026. This segment is projected to rise due to its capability to provide precise control of the direction of thrust, facilitate angular motion of the nozzles, and enable maneuverability in solid-propellant rocket systems. Flexible nozzle technologies are particularly appealing for aerospace and defense applications requiring compact propulsion control mechanisms, high reliability and accurate trajectory correction.
In March 2026, Kratos Defense announced that it was awarded a USD 49 million contract by the U.S. Naval Surface Warfare Center for the production and delivery of up to 36 Oriole solid rocket motors and three thrust vector control nozzle kits. The contract highlights continued government buys of specialized rocket propulsion and nozzle-control technologies.
Why is the Missiles Segment Holding the Largest Market Share?
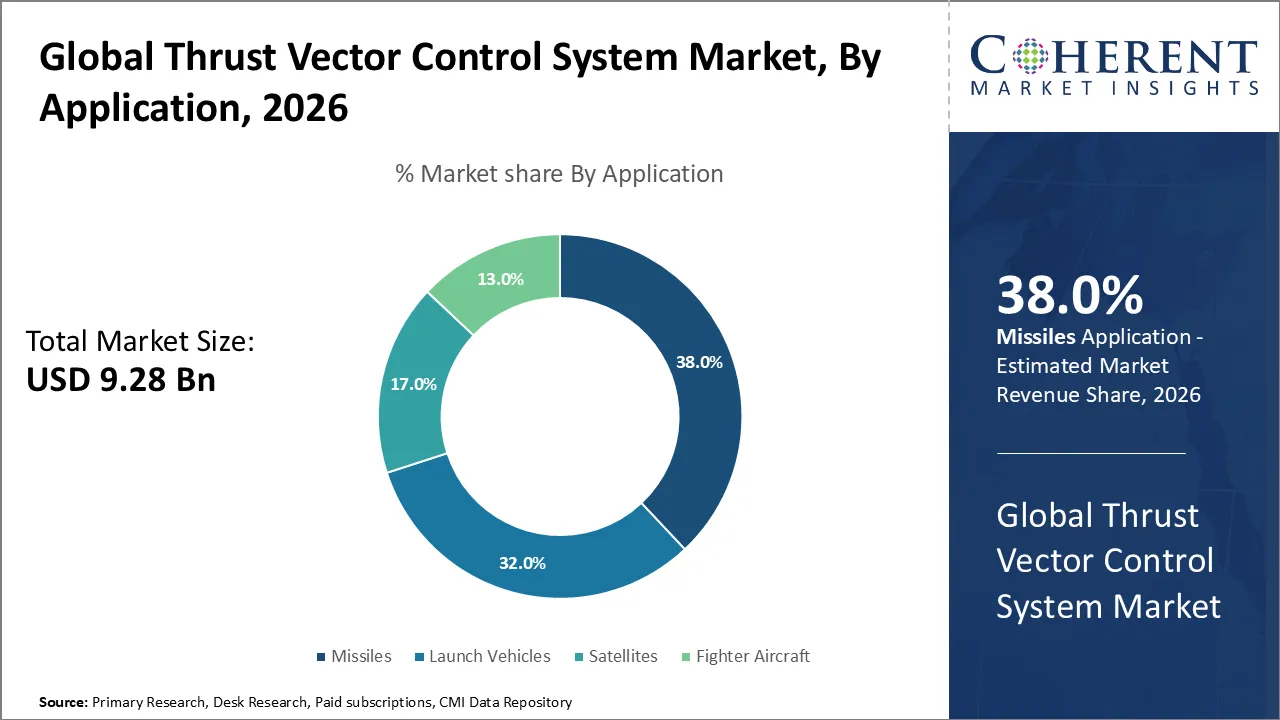
Based on application, the missiles segment is projected to hold the largest share of 38.0% in the thrust vector control system market by 2026. The segment is driven by rising investments in precision-guided munitions, advanced missile defense systems and next-generation tactical weapons. TVAC systems allow precise trajectory corrections and greater maneuverability during the powered flight phase of the missile.
According to the U.S. Army says Lockheed Martin has been awarded a USD 9.8 billion contract for Fiscal Year 2024-2026 to produce 1,970 PAC-3 Missile Segment Enhancement interceptors and associated hardware for U.S. and international defense needs. This is in line with increasing acquisition of sophisticated guided missile systems and requirements for precision propulsion and flight-control technologies.
In January 2026, Lockheed Martin announced a seven-year framework agreement with the U.S. government to increase annual PAC-3 MSE production capacity from approximately 600 to 2,000 interceptors. The expansion is consistent with ongoing investments in missile manufacturing infrastructure and in advanced propulsion components.
Why is the Thrust Vector Actuation System Segment Dominating the Market?
Based on system the Thrust Vector Actuation System segment is expected to dominate the market and is projected to reach 52.0% share in 2026. The segment growth is attributed to the increasing adoption of electromechanical and electrohydraulic actuation technologies in launch vehicles, missiles and aerospace propulsion systems. These systems provide accurate nozzle positioning, rapid directional changes and dependable thrust control, all critical for advanced flight control applications.
According to the Indian Space Research Organization (ISRO) has successfully conducted a static test of an improved third-stage solid rocket motor for its Small Satellite Launch Vehicle (SSLV) in December 2025. The system incorporated a fault-tolerant electromechanical actuation mechanism with low-power control electronics for nozzle control.
Why is the Defense Segment Accounting for the Largest Market Share?
On the basis of end user, the Defense segment is projected to account for the largest Thrust Vector Control System Market share of approximately 65.0% in 2026. This segment’s dominance is due to increasing procurement of advanced missile systems, growing investments in military propulsion technologies and rising demand for precision-guided weapons. The defense organizations are working on improving the missile’s maneuverability, interception accuracy, and reliability of the propulsion system using advanced thrust-control technologies.
In September 2026, L3Harris Technologies announced USD 4.7 billion contract award over seven years from Lockheed Martin to manufacture propulsion systems for the PAC-3 Missile Segment Enhancement program. The agreement supports the expansion of production capacity for advanced solid rocket propulsion technologies for missile defense applications.
In July 2026 L3Harris announced a seven-year framework agreement for advanced two-pulse solid rocket motors, attitude control motors and lethality-enhancement components for the PAC-3 MSE program.
Thrust Vector Control System Market Trends
- The increasing penetration of electromechanical thrust vector control systems is driving demand for lightweight, energy efficient and highly responsive propulsion actuation technologies. In April 2026, Relativity Space announced that the initial development of its thrust vector control actuators for the Terran R launch vehicle was complete and flight-unit production is underway.
- Reusable launch vehicles and differential thrust control are becoming increasingly important, and new propulsion systems are needed to provide precise maneuvering without the use of conventional engine gimbaling. In September 2026, Stoke Space announced USD 1B in Series E financing to scale up its Nova reusable launch vehicle program, including differential-throttle thrust vector control technology.
- Thrust-vectoring nozzles are becoming more sophisticated and are being added to military aircraft that use propulsion technologies to improve maneuverability and allow vertical takeoff and landing. In July 2026, GE Aerospace and Shield AI successfully completed integration, actuation, and engine light-off testing of the Axisymmetric Vectoring Exhaust Nozzle (AVEN) with the F110-GE-129E engine for the X-BAT autonomous aircraft.
Regional Insights
North America Dominates Owing to Strong Aerospace Manufacturing Capabilities and Advanced Defense Infrastructure
North America is predicted to account for the largest Thrust Vector Control System Market share of about 39.0% in 2026. The region is expected to dominate the market owing to presence of established aerospace and defense manufacturing base, increasing investments in advanced missile technologies and strong presence of major propulsion system manufacturers such as Honeywell, Moog, Parker Hannifin and Northrop Grumman. The increasing pace of commercial space activities and the development of reusable launch vehicles are further fueling demand for precision actuation systems, gimbal nozzles and advanced thrust vector control technologies.
According to the U.S. Congressional Research Service, the U.S. Space Force expected to support some 173 launch operations in the Eastern and Western Ranges in FY 2026, up from 25 launches a decade earlier. This substantial increase in launch activity reflects the growing demand for robust launch vehicle propulsion and flight control technologies.
In May 2026, the U.S. Space Force awarded Blue Origin a National Security Space Launch Phase 3 Lane 1 task order to support a National Reconnaissance Office mission. The Space Systems Command also reported an annual space acquisition budget of around USD 15.6 billion, which shows continued government investment in national security space capabilities.
Asia Pacific Thrust Vector Control System Market Trends
Asia Pacific is anticipated to emerge as the fastest-growing region in the Thrust Vector Control System Market during 2026–2033. Regional growth is supported by expanding space exploration programs, increasing defense modernization investments, and rising development of indigenous launch vehicles across China, India, Japan, and South Korea. The growing participation of commercial space companies and increasing adoption of advanced propulsion control technologies are creating opportunities for thrust vector control system manufacturers.
In India, the Ministry of Science and Technology reported in 2026 that the country successfully completed 12 launch vehicle missions, launched 11 national satellites, and deployed 9 satellites for international customers between July 2023 and June 2026. The government is also developing a second launch complex at Kulasekarapattinam, Tamil Nadu, to support Small Satellite Launch Vehicle operations and private-sector launch activities.
Who are the Major Companies in Thrust Vector Control System Industry
Some of the major key players in Thrust Vector Control System Market are Honeywell International, Inc., Moog, Inc., Woodward, Inc., Jansen Aircraft Systems Control, Inc., BAE Systems, Wickman Spacecraft & Propulsion Company, Parker Hannifin, Inc., Sierra Nevada Corporation, Dynetics, Inc., and SABCA.
Key News
- In June 2026, BAE Systems Australia highlighted the expansion of specialized manufacturing capabilities supporting the Evolved SeaSparrow Missile (ESSM) program. The company identified Ronson Gears as a supplier of precision gear kits for thrust vector control units, strengthening the supply chain for advanced missile guidance and maneuvering technologies.
- In October 2025, ArianeGroup awarded SABCA a major supply contract for thrust vector control nozzle actuation systems for Ariane 6 launch vehicles 16 to 42. The agreement strengthens Europe’s space launch capabilities and strengthens SABCA’s position in advanced propulsion actuation technologies.
Market Report Scope
Thrust Vector Control System Market Report Coverage
Report Coverage | Details | ||
Base Year: | 2025 | Market Size in 2026: | USD 9.28 Bn |
Historical Data for: | 2020 to 2024 | Forecast Period: | 2026 to 2033 |
CAGR: | 4.3% | 2033 Value Projection: | USD 12.50 Bn |
Geographies covered: |
| ||
Segments covered: |
| ||
Companies covered: | Honeywell International, Inc., Moog, Inc., Woodward, Inc., Jansen Aircraft Systems Control, Inc., BAE Systems, Wickman Spacecraft & Propulsion Company, Parker Hannifin, Inc., Sierra Nevada Corporation, Dynetics, Inc., and SABCA. | ||
Growth Drivers: |
| ||
Restraints & Challenges: |
| ||
Analyst Opinion
- The Thrust Vector Control System Market is strongly supported by expanding commercial space launch programs and increasing demand for advanced propulsion technologies. Ariane 6’s maiden flight was in July 2024 and there were four commercial launches in 2025, the French National Center for Space Studies (CNES) said. In the two-booster and four-booster versions, the progression shows the growing demand for adaptable propulsion and precise thrust vector control systems for various launch requirements.
- Government-sponsored aerospace programs are speeding up the development of next-generation launch vehicles and advanced flight-control technologies. In August 2026, the European Space Agency (ESA) awarded the first contracts under its European Launcher Challenge initiative to support new European launch service providers. The initiative should increase competition, stimulate propulsion system innovation and provide opportunities for thrust vector control system manufacturers supporting commercial and institutional launch programs.
- Growing interest in propulsion reliability, precision steering and flight safety is generating opportunities for advanced thrust vector control technologies. In June 2026, the four-booster configuration of Ariane 6 successfully deployed 36 satellites for Amazon’s Leo constellation, demonstrating the technical requirements growing in high-capacity launch missions. The ongoing progress in nozzle steering, electromechanical actuation and propulsion control is likely to increase the adoption of reliable thrust vector control systems in aerospace and defense applications.
Speak to the analyst
Want personalized insights?
Take the findings above to one of our principal consultants, or have the report rebuilt around the segments, geographies and competitors you actually track.
Market Segmentation
- By Technology (Revenue, USD Bn, 2021-2033)
- Gimbal Nozzle
- Flex Nozzle
- Thrusters
- Rotating Nozzle
- Others (Injection, Jet Vanes, and Tabs)
- By Application (Revenue, USD Bn, 2021-2033)
- Launch Vehicles
- Missiles
- Satellites
- Fighter Aircraft
- By System (Revenue, USD Bn, 2021-2033)
- Thrust Vector Actuation System
- Thrust Vector Injection System
- Thrust Vector Thruster System
- By End User (Revenue, USD Bn, 2021-2033)
- Space Agencies
- Defense
- By Region (Revenue, USD Bn, 2021-2033)
- North America
- U.S.
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Rest of Latin America
- Europe
- Germany
- U.K.
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- South Africa
- Central Africa
- North Africa
- North America
Sources
Primary Research Interviews
- Thrust vector control system manufacturers
- Aerospace propulsion and rocket engine engineers
- Missile guidance and control system developers
- R&D heads from aerospace and defense manufacturing companies
- Electromechanical and hydraulic actuation system manufacturers
- Space agencies and commercial launch vehicle operators
- Aerospace and defense procurement managers
- Key opinion leaders (KOLs) in propulsion systems and flight-control technologies
Databases
- World Bank
- Organisation for Economic Co-operation and Development (OECD)
- National Aeronautics and Space Administration (NASA)
- European Space Agency (ESA)
- Federal Aviation Administration (FAA)
- U.S. Department of Defense (DoD)
- Stockholm International Peace Research Institute (SIPRI)
- United Nations Office for Outer Space Affairs (UNOOSA)
Magazines
- Aviation Week & Space Technology
- Aerospace America
- SpaceNews
- Defense News
- Air & Space Forces Magazine
- FlightGlobal
- Military & Aerospace Electronics
Journals
- Journal of Propulsion and Power
- Aerospace Science and Technology
- Acta Astronautica
- Journal of Spacecraft and Rockets
- CEAS Space Journal
- Aerospace
- International Journal of Aerospace Engineering
Newspapers
- The New York Times
- The Wall Street Journal
- Financial Times
- Reuters
- The Guardian
- The Economic Times
Associations
- American Institute of Aeronautics and Astronautics (AIAA)
- Aerospace Industries Association (AIA)
- National Defense Industrial Association (NDIA)
- Satellite Industry Association (SIA)
- Space Foundation
- International Astronautical Federation (IAF)
- Aerospace, Security and Defence Industries Association of Europe (ASD)
Public Domain Sources
- Company Annual Reports and Investor Presentations
- NASA, ESA, ISRO, and Other Space Agency Publications
- Government Defense Budgets and Aerospace Procurement Reports
- Commercial Space Launch Statistics and Mission Reports
- Company Product Catalogs and Technical Specifications
- University Research Publications and Aerospace Engineering Studies
- Patent Databases such as WIPO, USPTO, and Google Patents
- Regulatory and Standards Publications Related to Aerospace Propulsion and Flight-Control Systems
- Publicly Available Missile Defense and Space Launch Program Reports
Proprietary Elements
- CMI Data Analytics Tool
- Proprietary CMI Existing Repository of Information for the Last 10 Years
Get access to 250+ pages report
Every segment, forecast, competitor profile and data table behind the analysis above — available for instant download.
- ESOMAR Member
- ISO 9001:2015 Certified
- D-U-N-S Registered
- GDPR & CCPA Compliant
Missing comfort of reading report in your local language? Find your preferred language:
Transform your Strategy with Exclusive Trending Reports
Frequently Asked Questions
The global Thrust Vector Control System Market is expected to reach USD 12.50 Bn by 2033, compared to USD 9.28 Bn in 2026.
Major players operating in the global Thrust Vector Control System Market include Honeywell International, Inc., Moog, Inc., Woodward, Inc., Jansen Aircraft Systems Control, Inc., BAE Systems, Wickman Spacecraft & Propulsion Company, Parker Hannifin, Inc., Sierra Nevada Corporation, Dynetics, Inc., and SABCA.
High development and manufacturing costs, complex system integration requirements, stringent aerospace and defense regulations, and technical reliability challenges are the major factors hampering market growth.
Increasing investments in space exploration programs, rising demand for advanced missile guidance systems, expanding commercial satellite launch activities, and growing adoption of precision propulsion technologies are driving market growth.
The Thrust Vector Control System Market is anticipated to grow at a CAGR of approximately 4.3% between 2026 and 2033.
North America is expected to dominate the global Thrust Vector Control System Market, accounting for an estimated 39.0% market share in 2026.
Asia Pacific is anticipated to witness the fastest growth during the forecast period, driven by expanding space exploration programs, increasing defense investments, and growing development of indigenous launch vehicles in China, India, Japan, and South Korea.